
Plenty of people assume they’re financially healthy because they earn well or have a comfortable checking account balance. But financial stability is made up of several moving parts — cash flow, debt, savings, emergency protection, and long-term direction — not one number. This article walks through a 7-part scoring framework you can use to check your own financial position, spot the areas under the most pressure, and improve them one at a time.
This framework is an educational personal-finance tool, not an official government score, credit score, bank rating, or universal financial standard.
Quick Answer
A Financial Stability Score is a self-assessment framework that scores your finances across seven areas — cash flow, emergency savings, debt pressure, savings consistency, net worth direction, income resilience, and financial protection — out of 100 total points. It answers a more useful question than income alone: how well would your finances hold up if life got more expensive or your income changed? The goal is to identify your weakest category and improve it before it becomes a bigger problem.
The Real Question: Are You Financially Stable?
Financial stability is easy to confuse with income. Picture two people who each earn $150,000 a year. One has a large mortgage, two expensive car loans, growing credit card balances, and less than a month of emergency savings. The other has manageable housing costs, positive monthly cash flow, steady savings, and a growing emergency fund. Same income — very different financial stability.
Income Isn’t the Same as Financial Security
A higher salary creates opportunity, but it doesn’t automatically create security. When expenses rise every time income does, the stress of feeling financially stretched can persist no matter how much you earn — a pattern often called lifestyle inflation.
A Bank Balance Doesn’t Tell the Whole Story
A checking account showing $10,000 looks reassuring on its own. It looks very different next to $25,000 in credit card debt and $6,000 in monthly expenses. A balance is one data point, not the full picture.
Good Credit Isn’t Overall Financial Health
A credit score is useful when you’re borrowing money, but it says nothing about whether you have an emergency fund, positive cash flow, or a growing net worth. Credit and financial stability are related, but they’re not the same measurement.
Assets Can Hide Financial Pressure
A valuable home or investment account doesn’t guarantee short-term security. If you can’t cover essential expenses or absorb an unexpected bill, your position may still be fragile despite what your net worth statement shows.
What a Financial Stability Score Actually Measures
Instead of asking how much you earn, the framework asks a more useful question: how strong is my financial position if life becomes more expensive or my income changes? Think of it like a car dashboard — it doesn’t just show speed, it shows fuel, temperature, and warning lights, because a single number can’t capture the vehicle’s full condition.
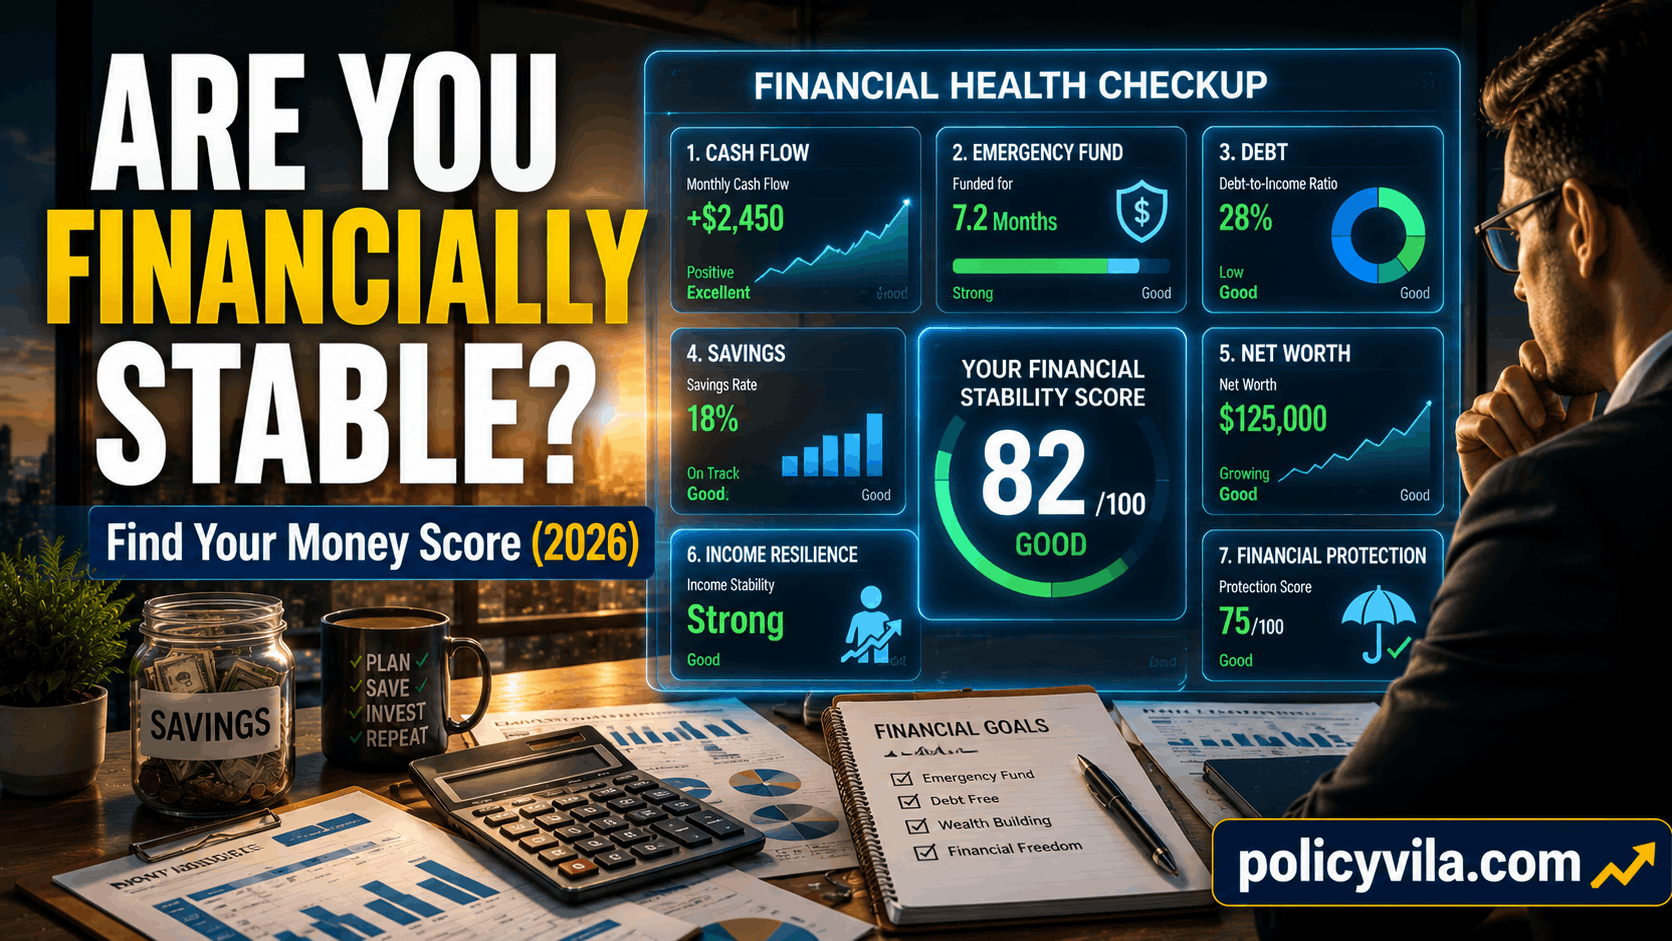
A meaningful money health check looks at cash flow, emergency savings, debt pressure, savings consistency, net worth direction, income resilience, and financial protection. The scoring system below totals 100 points across these seven areas.
The 7-Part Scoring Framework
Cash Flow Strength — 20 Points
Cash flow is what’s left after income meets expenses each month. Positive cash flow gives you flexibility — room to save, invest, pay down debt, or absorb a surprise cost. Negative cash flow creates pressure, since you’re spending beyond what your income supports.
Someone earning $8,000 a month but spending $8,500 has a cash flow problem. Someone earning $4,000 and consistently keeping $800 after expenses may actually have the stronger foundation. Consider whether your monthly cash flow is positive, whether expenses are creeping up, and whether you’re relying on credit to cover regular costs — a stronger position earns more points.
Emergency Fund Protection — 15 Points
An emergency fund exists for the unplanned: job loss, a major repair, a medical bill, urgent travel, a family need. There’s no single “right” target — a single person with stable income has different needs than a family with children or a self-employed worker with irregular income. Instead of chasing a universal number, weigh your emergency savings against your essential monthly expenses and ask how long that cushion would actually last if income stopped.
Debt Pressure — 15 Points
The relevant question isn’t just whether you have debt — it’s how much pressure that debt puts on your monthly finances. Review your monthly debt payments, any high-interest balances, your debt-to-income ratio, credit card debt, and loan obligations. A manageable mortgage paired with stable cash flow is a different financial position than several high-interest balances competing for the same paycheck.
Savings Consistency — 10 Points
An occasional large deposit looks impressive, but a steady monthly habit usually says more about financial discipline. Look at how often you save, whether it happens automatically, whether you save before spending the rest, and whether your savings rate is trending up. Even a small amount, saved consistently, builds a foundation worth having.
Net Worth Direction — 15 Points
Net worth is assets minus liabilities — savings, investments, property, or business ownership, minus mortgages, loans, and other debts. The number that matters most isn’t how your net worth compares to someone else’s, but which direction it’s moving. A modest net worth that’s steadily growing often reflects a healthier trajectory than a larger one that’s shrinking.
Income Resilience — 10 Points
This measures how prepared you are for a change in income — not whether you need multiple jobs or side businesses. Ask how stable your current role is, whether your skills are in demand, whether you could find other work if needed, and whether there’s room to grow your income over time. Multiple income sources can help, but they don’t guarantee security on their own.
Financial Protection and Planning — 15 Points
This covers how prepared you are for major financial risks: insurance coverage, retirement planning, organized financial documents, up-to-date beneficiary information, and clear long-term goals. What counts as adequate protection depends entirely on your situation — a young single person and a parent with several dependents will reasonably weigh this differently. The goal isn’t buying every available financial product; it’s understanding your actual risks and having a reasonable plan for them.
How to Calculate Your Score
- Review each of the seven financial areas above.
- Score yourself honestly in each category, using real numbers rather than a general impression.
- Add the points together.
- Review your total against the ranges below.
- Identify your weakest category as your starting point for improvement.
| Financial Area | Maximum Points | Your Score |
|---|---|---|
| Cash Flow Strength | 20 | |
| Emergency Fund Protection | 15 | |
| Debt Pressure | 15 | |
| Savings Consistency | 10 | |
| Net Worth Direction | 15 | |
| Income Resilience | 10 | |
| Financial Protection and Planning | 15 | |
| Total | 100 |
The score is only useful if the inputs are honest — giving yourself full marks on cash flow because you feel generally optimistic defeats the purpose. Use your actual numbers.
What Your Score Range Means
These ranges are educational categories created for this framework, not an official financial rating.
| Score | Financial Position |
|---|---|
| 85–100 | Strong Financial Foundation |
| 70–84 | Stable but Improving |
| 50–69 | Financial Pressure Zone |
| 30–49 | High Financial Vulnerability |
| Below 30 | Immediate Financial Review Needed |
85–100: Strong Financial Foundation
Your financial system is generally working — likely positive cash flow, consistent savings, manageable debt, and reasonable protection in place. The priority here is maintaining good habits while continuing to build toward longer-term goals.
70–84: Stable but Improving
Several areas are solid, but one or two are pulling the score down — healthy savings alongside high debt pressure, for example. Focus on the lowest-scoring category first.
50–69: Financial Pressure Zone
Financial strain may be starting to limit your flexibility — steady income paired with tight expenses, debt, or inconsistent savings. This isn’t a reason to panic; start by improving cash flow and identifying the single biggest source of pressure.
30–49: High Financial Vulnerability
An unexpected event could create real stress at this level, often from a combination of high debt, thin emergency savings, or negative cash flow. Basic stability is worth prioritizing here before any advanced wealth-building strategy.
Below 30: Immediate Financial Review Needed
A low score signals that several areas need attention at once — it doesn’t define your financial future. Start with essential expenses, cash flow, and the most urgent obligations first.
Why High Earners Can Still Score Low
A large paycheck can create a false sense of security. Consider a professional earning $150,000 a year who also carries a large mortgage, expensive vehicle payments, high monthly spending, and almost no emergency savings. On paper the income looks strong — but a job loss could turn that situation stressful very quickly.
This is lifestyle inflation in practice: as income rises, spending on housing, vehicles, travel, and daily habits often rises with it, until the larger paycheck becomes necessary just to maintain the new baseline. A higher income improves financial stability only when part of it actively strengthens savings, reduces financial pressure, or supports longer-term goals — not automatically just by existing.
Financial Stability vs Income vs Credit Score
| Factor | Income | Financial Stability |
|---|---|---|
| Definition | Money earned | Strength of your overall financial position |
| Main Focus | Earnings | Financial resilience |
| Key Indicators | Salary and income sources | Cash flow, debt, savings, net worth |
| Short-Term Security | Provides spending power | Helps absorb financial disruptions |
| Long-Term Impact | Depends on money management | Reflects overall financial direction |
| Feature | Financial Stability Score | Credit Score |
|---|---|---|
| Main Purpose | Review overall money health | Measure credit risk |
| Measures | Savings, cash flow, debt, resilience | Credit history and borrowing behavior |
| Used By | You | Lenders and authorized businesses |
| Includes Emergency Savings? | Yes | No |
| Includes Net Worth? | Yes | No |
| Official Universal Standard? | No | Yes, depending on the scoring model |
A credit score can’t tell you whether your emergency fund is adequate. A Financial Stability Score can’t replace a credit score when a lender is evaluating your borrowing history. Each answers a different financial question, and neither substitutes for the other.
10 Warning Signs Your Financial Stability Is Weak
- One missed paycheck creates panic. If missing a single paycheck makes essential bills unpayable, the system has little built-in flexibility.
- Credit cards cover basic expenses. Using credit occasionally for emergencies differs from relying on it for groceries or utilities — regular dependence often signals a cash flow issue.
- Savings have stopped growing. An unchanged balance for months is worth investigating — it may mean savings has quietly lost priority against other spending.
- Debt balances rise every month. Even if payments still feel affordable, a growing balance reduces future flexibility.
- You don’t know your monthly expenses. Financial health is hard to measure without a working sense of what your household actually needs each month.
- Every emergency creates new debt. If unexpected costs consistently land on a credit card or loan, emergency protection is likely too thin.
- Financial goals stay vague. “Save more money” isn’t measurable — specific goals are what let you track real progress.
- Income rises but savings don’t. This is a common sign of lifestyle inflation — worth tracing where the additional income is actually going.
- Financial documents are scattered. Missing insurance, loan, or account records adds unnecessary stress right when you need them most.
- You avoid checking your numbers. Avoidance doesn’t make a financial problem disappear — regular review is what surfaces it early enough to act on.
How to Improve Your Score, Category by Category
You don’t need to tackle every category at once — start with whichever one scored lowest.
- Cash flow: Review recurring expenses and identify spending that no longer matches your priorities. Even a modest improvement creates real flexibility.
- Emergency savings: Don’t wait until you can save a large amount at once — build a regular habit first and increase the amount as your situation allows.
- Debt: High-interest debt quietly absorbs money that could otherwise go toward savings or long-term goals. Build a realistic repayment plan rather than an aggressive one you can’t sustain.
- Savings consistency: Set a specific monthly target. A steady, smaller amount usually beats occasional large deposits for building the underlying habit.
- Net worth: Calculate assets and liabilities at least once a year, and focus on the trend rather than the exact figure.
- Income resilience: Keep developing skills that stay in demand — career flexibility is itself a form of long-term financial security.
- Financial protection: Revisit your coverage and planning as life changes — marriage, children, homeownership, and career shifts all affect what “adequate” protection looks like.
A 30-Day Financial Stability Reset
Week 1: Understand Your Numbers
Collect the basics — monthly income, essential expenses, total debt, savings, and investments — then calculate your starting score. The goal here is understanding your current position, not judging it.
Week 2: Reduce Financial Pressure
Review your monthly expenses for recurring costs that have crept up or no longer provide much value, with a focus on understanding your cash flow overall.
Week 3: Strengthen Savings
Choose a realistic savings amount you can sustain rather than an ambitious one you’ll likely abandon, and track every contribution through the week to build the habit.
Week 4: Build a Long-Term System
Set a recurring monthly review date and pick one area to focus on each time. A system you’ll actually keep up with beats one that depends on motivation.
How Often to Check Your Score
A monthly review is enough for most people — update your numbers and note what’s changed. A quarterly review can reveal deeper trends, and a full annual audit is worth doing once a year. Checking daily isn’t necessary; financial stability shows up in trends over time, not in daily fluctuations.
Common Mistakes When Measuring Financial Health
- Focusing only on income. Income matters, but it’s only one part of the full picture.
- Comparing yourself to friends. Financial responsibilities differ enough between households that comparisons rarely mean much.
- Inflating asset values. Overestimating what you own creates a score that misleads rather than informs.
- Ignoring debt. Debt meaningfully affects financial flexibility — leave it out and the score loses its purpose.
- Scoring yourself too generously. A lower, honest score is more useful than an inflated one.
- Tracking too many numbers. An overcomplicated system is hard to maintain — the seven core areas are enough.
- Judging by a single unusual month. One outlier month rarely defines your overall trajectory — look for patterns instead.
Financial Stability Checklist
- I know my monthly cash flow
- I know my total debt
- I know how much emergency savings I have
- I track my net worth
- I save consistently
- I review my financial goals
- I understand my financial protection
- I have calculated my Financial Stability Score
Frequently Asked Questions
Can my score change significantly from one month to the next?
It can if something major shifts — a job change, a large unexpected expense, or a debt payoff — but for most people the score moves gradually as habits in each category shift over time.
Should I recalculate every category every time I check my score?
Not necessarily. A monthly check can focus on cash flow and savings consistency, since those change most often, while net worth and financial protection may only need a full review quarterly or annually.
What if two categories score very differently — should I prioritize the lower one even if it’s a smaller point total?
Generally yes. A weak result in even a 10-point category, like income resilience, can create real vulnerability that a stronger cash flow score doesn’t offset.
Does this framework account for irregular or self-employed income?
The framework doesn’t assign extra points for self-employment specifically, but irregular income naturally affects several categories — emergency fund needs, income resilience, and cash flow all deserve extra scrutiny if your income varies month to month.
Is it possible to have a high score and still feel financially stressed?
Yes — the score reflects measurable financial indicators, not day-to-day feelings about money. Stress can come from factors the framework doesn’t capture, like job satisfaction or family circumstances, even when the underlying numbers look solid.
Can couples calculate a shared score, or should each person score separately?
Both approaches work. A shared score reflects household finances as a whole, while separate scores can help identify which partner’s financial habits or circumstances need the most attention.
How is this different from a net worth calculation alone?
Net worth is one category within this framework, worth 15 of the 100 points. The full score adds cash flow, debt pressure, savings habits, income resilience, and protection — areas net worth alone doesn’t capture.
Final Thoughts
Financial stability isn’t determined by income alone — it depends on several connected areas: cash flow, savings, emergency protection, debt control, net worth direction, income resilience, and financial planning.
This framework won’t predict your financial future, and a low score isn’t a permanent label any more than a high score is a guarantee against future problems. What it offers is a structured way to see your current position clearly and decide, with real numbers rather than guesswork, where improvement would matter most.