
What doesn’t show up on that lower monthly payment is the second number: how much the loan costs in total by the time it’s paid off. A longer repayment period can shrink the required monthly payment, but it also stretches out the period during which interest accrues, slows down how quickly you build equity, and can affect how a household plans for retirement and future moves. The real question isn’t whether a longer mortgage creates a smaller payment — it clearly can. It’s whether that smaller payment is worth what it costs over the life of the loan.
Quick Answer: What Is a 50-Year Mortgage?
A 50-year mortgage spreads home loan repayment over five decades instead of the more common 30 years, which can lower the scheduled monthly principal-and-interest payment but generally increases the total interest paid over the life of the loan. As of 2026, a 50-year term isn’t a standard, widely available mortgage product in the United States: the Qualified Mortgage rule under the Dodd-Frank Act caps qualified mortgages at 30 years, and Fannie Mae, Freddie Mac, FHA, and VA loans follow that same limit. A 50-year term became a subject of federal policy discussion in late 2025 and early 2026, but making it broadly available would require regulatory or legislative changes; in the meantime, it exists mainly as a non-QM product offered by a limited number of portfolio lenders, typically at a higher interest rate than a standard 30-year loan.
Table of Contents
- Is a 50-Year Mortgage Actually Available Right Now?
- When a Mortgage Gets Longer, the Math Changes
- 30, 40, and 50 Years Side by Side
- Payment Affordability vs. Total Financial Cost
- Equity Builds on a Different Timeline
- The Mortgage Payment Isn’t the Whole Housing Budget
- The Age-at-Payoff Question
- What the Lower Payment Is Actually Worth
- Pros and Cons of a Longer Mortgage Term
- Who Might Reasonably Consider It — and Who Should Be Cautious
- Myth vs. Reality
- A Worksheet for Comparing Loan Terms
- Common Mistakes When Evaluating a Longer Term
- Homebuyer Checklist
- Frequently Asked Questions
Is a 50-Year Mortgage Actually Available Right Now?
Before running the math on a 50-year loan, it’s worth understanding where the idea currently stands. In late 2025, a 50-year mortgage became part of a federal housing-affordability discussion, with officials at the Federal Housing Finance Agency (FHFA) publicly commenting on the concept. That drew both interest and criticism from lawmakers and housing economists.
The practical obstacle is regulatory. The Qualified Mortgage (QM) rule, created under the Dodd-Frank Wall Street Reform and Consumer Protection Act, generally limits qualified mortgages to a maximum 30-year term — and Fannie Mae, Freddie Mac, FHA, and VA loans all follow that same cap. Changing this on a broad scale would require regulatory or legislative action, which hadn’t happened as of this writing.
In practice, that means a 50-year term is currently offered mainly through non-QM lenders — typically portfolio lenders who keep the loan on their own books rather than selling it to Fannie Mae or Freddie Mac. Non-QM loans commonly carry higher interest rates than standard QM loans to offset the additional risk to the lender, along with stricter underwriting in some respects, such as larger down payments or documented cash reserves. That rate premium can significantly reduce — or even erase — the monthly savings a 50-year term appears to offer on paper. Availability, terms, and pricing can change, so anyone seriously considering this option should verify current terms directly with a lender rather than assuming based on marketing materials or media coverage of the policy discussion.
When a Mortgage Gets Longer, the Math Changes
A mortgage is a structured repayment agreement: you borrow money to buy a home and repay it over time through scheduled payments of principal and interest. The principal is the amount borrowed. The interest is the cost of borrowing it. The loan term determines how long that repayment period lasts.
A shorter term means fewer payments to repay the same principal, which generally means a higher monthly payment but less total interest. A longer term spreads the same debt across more payments, generally lowering the monthly amount but increasing the interest that accrues along the way.
An illustrative example
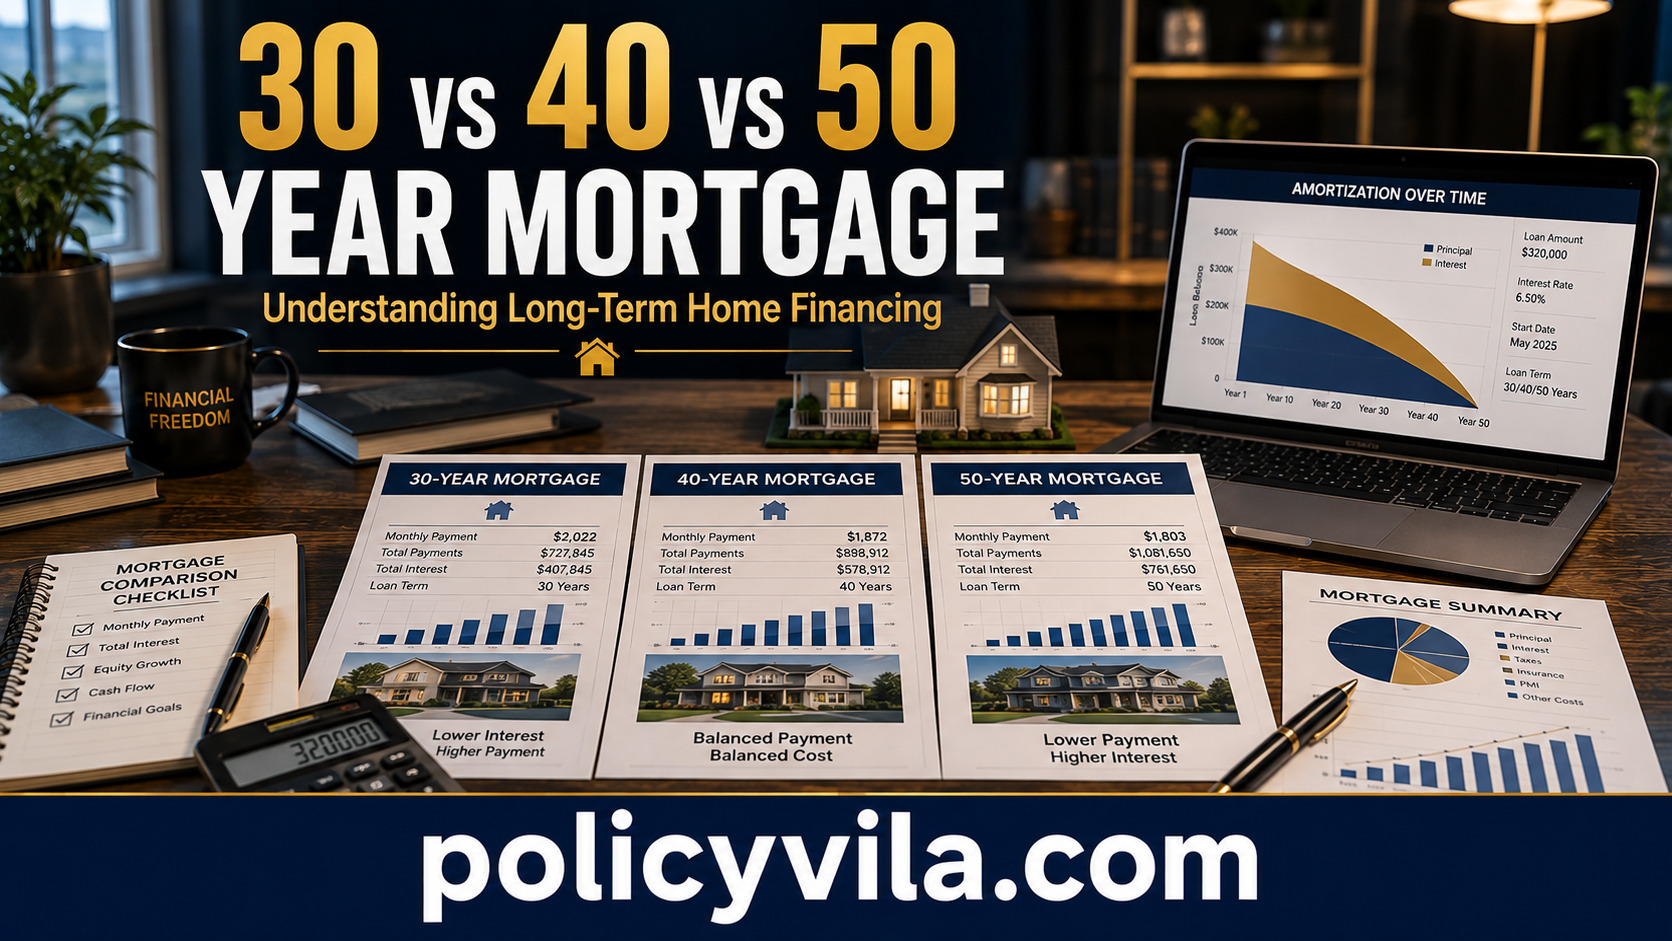
Consider a hypothetical $320,000 mortgage at a fixed 6.5% annual interest rate. These figures are mathematical illustrations only — not current mortgage quotes — and exclude property taxes, homeowners insurance, mortgage insurance, and closing costs.
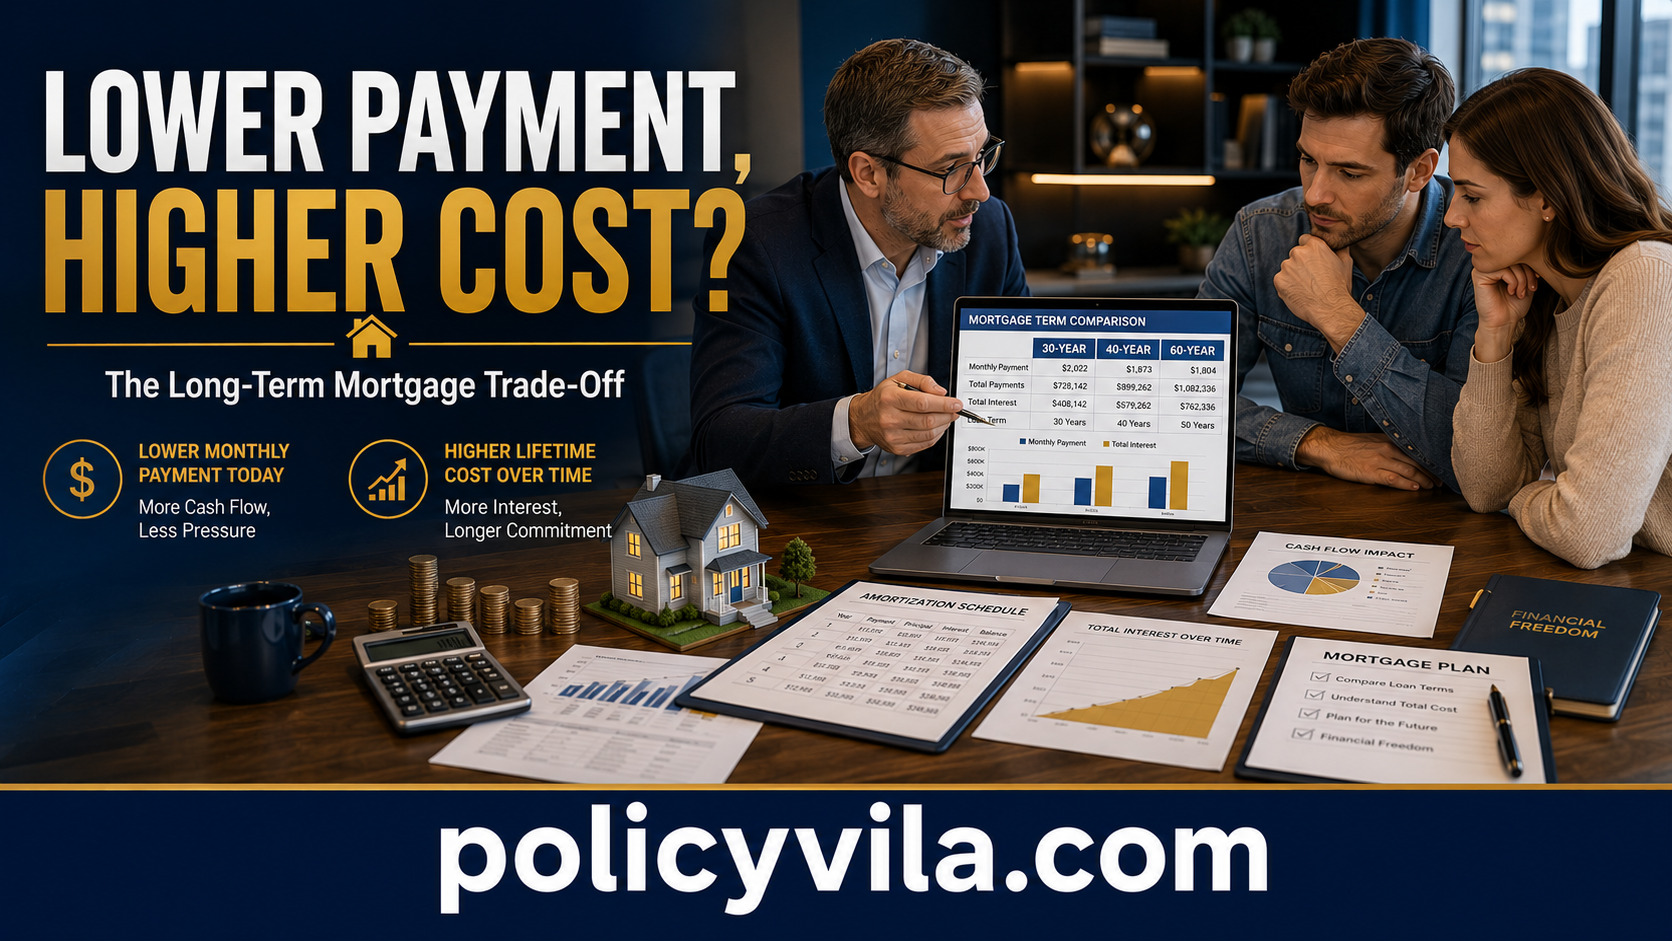
| Loan Term | Illustrative Monthly Principal & Interest | Approx. Total Payments | Approx. Total Interest |
|---|---|---|---|
| 30 years | $2,023 | $728,142 | $408,142 |
| 40 years | $1,873 | $899,262 | $579,262 |
| 50 years | $1,804 | $1,082,336 | $762,336 |
The gap between the 30-year and 50-year monthly payment here is about $219 — potentially meaningful to a household managing a tight budget. But the 50-year schedule also produces roughly $354,000 more interest than the 30-year schedule in this illustration. A lower monthly payment and a lower total cost are not the same thing, and in a real non-QM loan, a higher interest rate on the 50-year option would likely narrow the monthly savings even further than this same-rate illustration shows.
30, 40, and 50 Years Side by Side
| Factor | 30-Year | 40-Year | 50-Year |
|---|---|---|---|
| Number of payments | 360 | 480 | 600 |
| Illustrative monthly P&I | $2,023 | $1,873 | $1,804 |
| Approx. total interest | $408,142 | $579,262 | $762,336 |
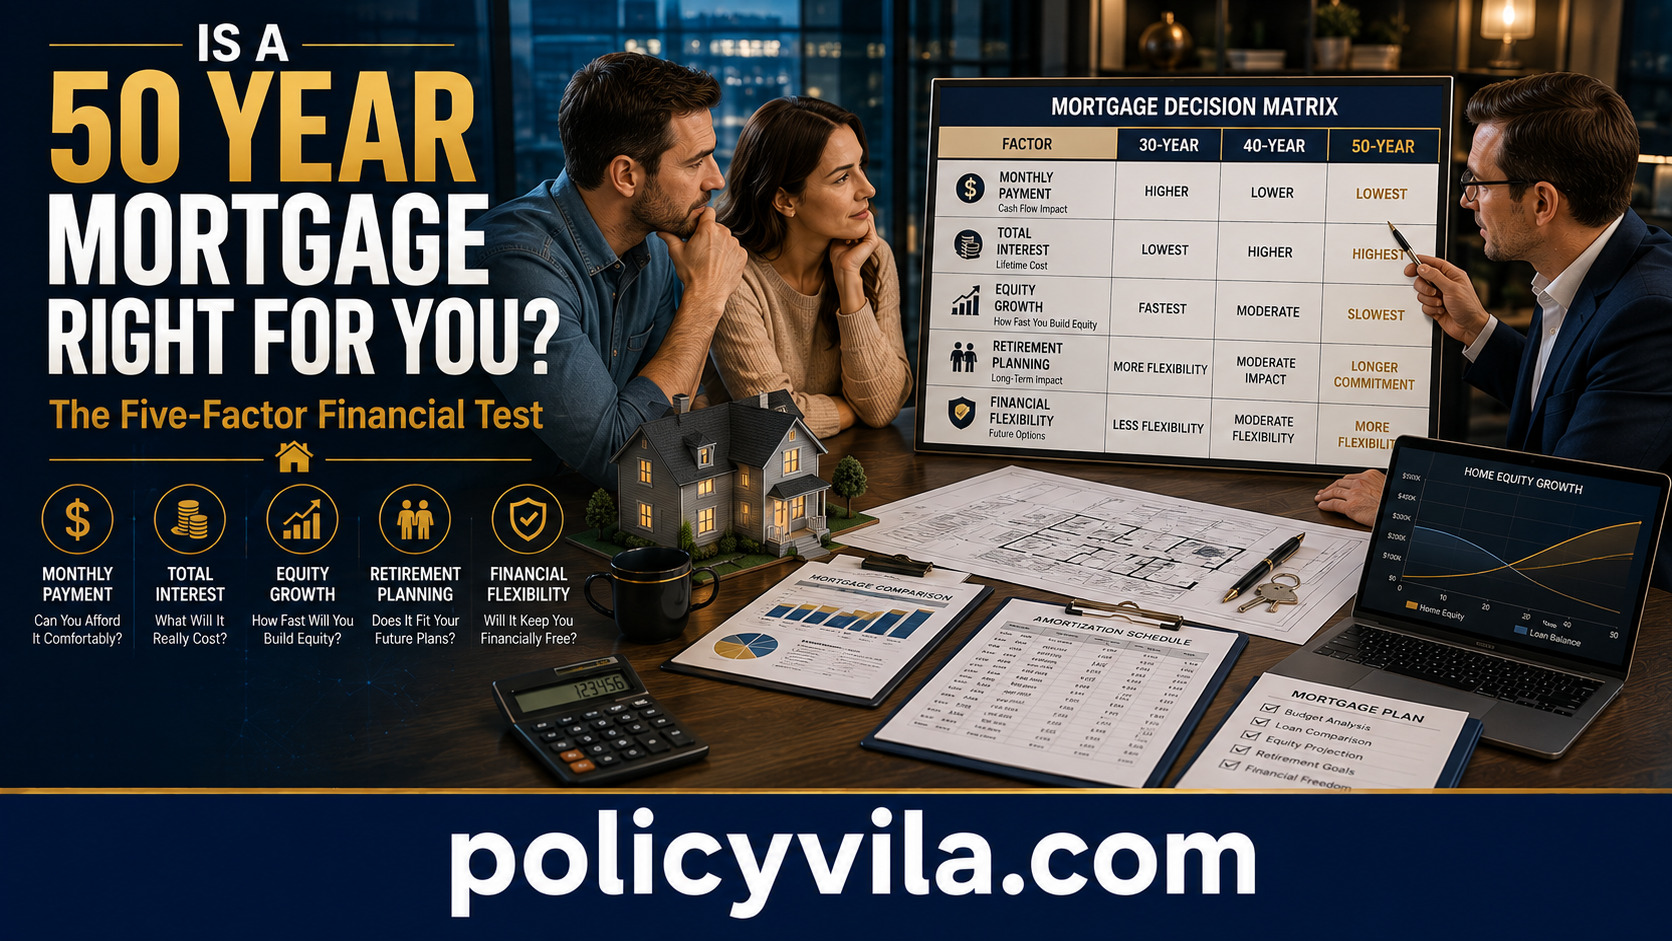
| Monthly payment | Highest | Lower | Lowest |
| Interest exposure | Lowest | Higher | Highest |
| Principal repayment pace | Fastest | Slower | Slowest |
| Standard QM/agency eligible? | Yes | Limited (some modification programs) | No — non-QM only as of 2026 |
The pattern holds regardless of the exact numbers: extending the term can reduce the required monthly payment while increasing the total cost of borrowing — and, for a 50-year term specifically, likely means accepting non-QM pricing on top of that trade-off.
Payment Affordability vs. Total Financial Cost
These are two different questions, and it’s easy to answer only the first one.
Payment affordability asks: can the household comfortably make the required monthly payment? Overall financial cost asks: how much will the household pay in total, and how does the loan fit alongside everything else — savings, retirement, other debt, and the full cost of owning the home?
A mortgage payment can look manageable on its own while property taxes, insurance, maintenance, utilities, HOA dues, and existing debt quietly stack up around it. A lower principal-and-interest payment helps with the first question. It doesn’t answer the second one.
Equity Builds on a Different Timeline
Home equity is what you actually own in the property: roughly, home value minus mortgage balance. It grows as you pay down principal and as the property’s market value changes, and a down payment provides a starting amount.
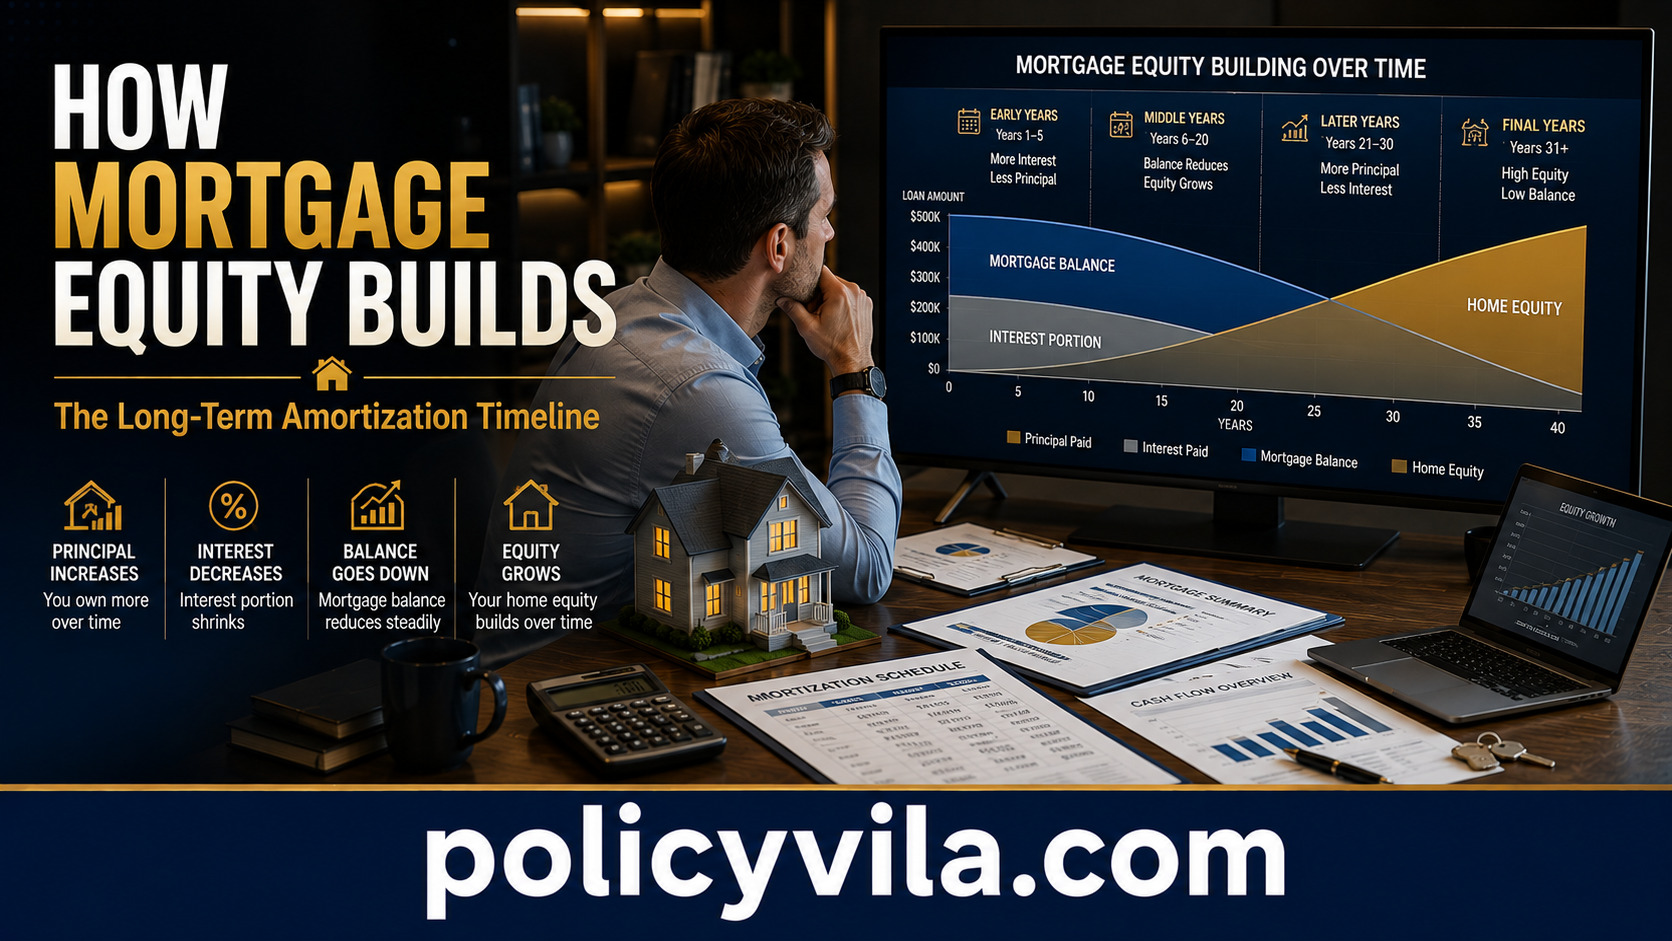
Mortgage payments aren’t split evenly between principal and interest throughout the loan. Early on, more of each payment typically goes toward interest because the outstanding balance is still high; as the balance falls, more of each payment goes toward principal. Stretch the same loan across 600 payments instead of 360, and that principal-reduction process is stretched out too — which generally means slower scheduled equity buildup through the early and middle years, when comparing loans with the same balance and rate.
That doesn’t automatically make the shorter-term borrower better off financially. A borrower with a 50-year term and a lower required payment might direct the difference toward retirement savings or an emergency fund instead. Equity accumulation and monthly affordability are related, but they’re not the same goal — and which one matters more depends on the household’s actual priorities.
The Mortgage Payment Isn’t the Whole Housing Budget
Principal and interest are only part of what it costs to own a home. Depending on the property and loan, homeowners may also face:
- Property taxes — often a substantial recurring cost tied to the property’s assessed value
- Homeowners insurance — protects against covered losses but adds an ongoing premium
- Mortgage insurance — may apply depending on the loan structure and equity position
- HOA dues or assessments — apply to some properties
- Maintenance and repairs — ongoing and sometimes unexpected, from HVAC issues to roofing
- Utilities — electricity, water, heating, and cooling
A lower mortgage payment doesn’t mean a low-cost home once these are added in. Budget for the full cost of ownership, not just the number on the amortization schedule.
[Relevant image: homeowner reviewing a full housing budget including mortgage, taxes, insurance, and maintenance costs]
The Age-at-Payoff Question
A 50-year term can stretch across multiple stages of adult life. A hypothetical 30-year-old borrower taking a full 50-year term would, on paper, carry that mortgage until around age 80 if it ran its complete scheduled course. In practice, most homeowners sell, refinance, or pay off a loan well before its final scheduled payment — but the original repayment horizon still matters for planning purposes, and it deserves particular attention for anyone approaching or already in retirement.
For a borrower nearing retirement, it’s worth thinking through how the remaining mortgage balance would interact with retirement income, Social Security, pension income, and investment withdrawals, and whether property expenses and any remaining mortgage payment would still fit comfortably. The question isn’t whether carrying a mortgage into retirement is inherently good or bad — it’s whether future income and assets can actually support it.
What the Lower Payment Is Actually Worth
A lower required payment creates optionality, not automatic financial benefit. Whether that optionality is worth anything depends entirely on what the household does with it.
If the monthly difference between a 30-year and 50-year payment simply gets absorbed into everyday spending, the lower payment provides little lasting financial value beyond short-term breathing room. If that difference is deliberately redirected toward an emergency fund, retirement contributions, or paying down higher-cost debt, the picture changes — the household is effectively trading a faster mortgage payoff for progress on other financial goals. Neither approach is automatically right; it depends on what the household is actually trying to accomplish and whether the redirected savings genuinely happen rather than just being a plan.
Pros and Cons of a Longer Mortgage Term
| Pros | Cons / Limitations |
|---|---|
| Can meaningfully lower the required monthly payment | Generally increases total interest paid over the life of the loan |
| May free up monthly cash flow for savings or other goals | Slows scheduled equity buildup compared with a shorter term |
| Can help with debt-to-income qualification in some cases | As of 2026, only available as a higher-rate non-QM product |
| Provides flexibility for borrowers with irregular income who plan extra principal payments | A longer repayment horizon may extend well into retirement years |
Who Might Reasonably Consider It — and Who Should Be Cautious
There’s no single borrower profile for whom this is automatically the right or wrong choice, but some situations call for extra scrutiny.
Worth examining for
- Households with a genuinely tight monthly budget where a lower required payment provides real breathing room
- Borrowers with strong financial discipline who plan to redirect the payment difference toward savings or investments
- Borrowers comparing several financing structures as part of a broader financial plan
Deserves particular caution for
- Borrowers near or in retirement, given the extended repayment horizon
- Households with significant existing debt, since a lower mortgage payment doesn’t erase other obligations
- Borrowers with limited emergency savings, since homeownership regularly creates unexpected expenses
- Borrowers expecting to sell relatively soon, since a slower equity buildup pace affects proceeds at sale
- Anyone assuming they’ll simply refinance later — future refinancing depends on market conditions, credit, and closing costs that aren’t guaranteed
Myth vs. Reality
| Myth | Reality |
|---|---|
| A lower monthly payment means the mortgage is cheaper overall | A lower payment often comes with a longer term and substantially more total interest |
| A 50-year mortgage means you’re locked in for 50 years | The term is the scheduled repayment period — selling, refinancing, or extra principal payments can shorten it |
| Home equity always grows at the same pace regardless of loan term | Equity buildup depends on the amortization schedule, which stretches out with a longer term |
| A longer loan automatically makes a home affordable | It may lower the mortgage payment, but taxes, insurance, and maintenance costs remain |
| 50-year mortgages are a standard, widely available product | As of 2026, they’re available mainly through non-QM portfolio lenders at higher rates, not through Fannie Mae, Freddie Mac, FHA, or VA |
| Refinancing later will always fix a high-interest-cost loan | Future refinancing depends on rates, property value, credit, and closing costs — none of which are guaranteed |
A Worksheet for Comparing Loan Terms
Before choosing between loan terms, or between a QM and non-QM lender, lay the options side by side using identical categories:
| Measure | Loan A | Loan B | Loan C |
|---|---|---|---|
| Loan amount | |||
| Interest rate | |||
| Loan term | |||
| Monthly principal & interest | |||
| Total scheduled interest | |||
| Balance after 10 years | |||
| Balance after 20 years | |||
| QM or non-QM? |
The projected balance at future milestones is often more revealing than the monthly payment alone — two loans with similar monthly payments can leave you with very different remaining balances after 10 or 20 years, which matters if you plan to sell, refinance, or borrow against home equity later.
Common Mistakes When Evaluating a Longer Term
Comparing only the monthly payment
Fix: Always pull the total scheduled interest and the projected balance at future milestones alongside the monthly number.
Assuming the same interest rate applies across all terms
Fix: Since a 50-year term is currently a non-QM product, expect a higher rate than a standard 30-year quote — ask for an actual quote rather than assuming the rate stays the same.
Assuming extra income will definitely materialize
Fix: Build a budget that works even if a promotion is delayed, a second income disappears, or expenses rise — not one that depends on optimistic assumptions.
Ignoring what happens to the “savings” from a lower payment
Fix: Decide in advance whether the monthly difference will go toward savings, investments, or debt — and follow through, since the benefit depends on it.
Treating future refinancing as guaranteed
Fix: Evaluate the loan as if refinancing might not happen, since rates, credit, and property values can all move against you.
Ignoring the full cost of homeownership
Fix: Add taxes, insurance, HOA dues, and a maintenance reserve to the mortgage payment before judging affordability.
read also: Can I Pay My Mortgage With a Credit Card
Homebuyer Checklist Before Considering a Longer Mortgage Term
- Confirm whether a 50-year term is even available through your lender, and whether it’s QM or non-QM
- Get an actual rate quote rather than assuming it matches a 30-year rate
- Calculate monthly payment, total scheduled interest, and total payments for each term you’re considering
- Compare projected mortgage balance after 10 and 20 years across terms
- Add property taxes, insurance, HOA dues, and a maintenance reserve to your affordability estimate
- Decide specifically what you’d do with any monthly savings — and whether you’ll actually follow through
- Consider how the loan term interacts with your expected retirement timeline
- Avoid assuming future refinancing will be available or advantageous
Frequently Asked Questions
Is a 50-year mortgage currently legal in the United States?
It’s not prohibited outright, but it falls outside the Qualified Mortgage rule, which caps qualified mortgages at 30 years under the Dodd-Frank Act. That means a 50-year loan is currently offered only as a non-QM product by a limited number of lenders, rather than through Fannie Mae, Freddie Mac, FHA, or VA.
Why would a lender charge a higher rate on a 50-year mortgage?
Because it falls outside the Qualified Mortgage framework, a 50-year loan is generally classified as non-QM, and non-QM loans typically carry higher interest rates to offset the additional risk lenders take on by keeping these loans on their own books rather than selling them to Fannie Mae or Freddie Mac.
Does a 50-year mortgage help with loan qualification?
It can, in some cases, since a lower required monthly payment may improve a borrower’s debt-to-income ratio. However, non-QM underwriting can also be stricter in other respects, such as requiring a larger down payment or documented cash reserves, so it’s not automatically easier to qualify overall.
How much more interest does a 50-year mortgage cost compared to a 30-year mortgage?
It depends on the loan amount, interest rate, and whether the rates are actually comparable between the two terms. In an illustrative same-rate example, a 50-year term can add several hundred thousand dollars of interest compared to a 30-year term on the same balance — and a real-world 50-year non-QM rate premium would likely make that gap larger, not smaller.
Can someone with a 50-year mortgage pay it off faster than scheduled?
Often, yes, depending on the specific loan’s terms — additional principal payments, refinancing, or selling the property can all shorten the effective repayment period. Review your specific loan documents to confirm how extra payments are applied before assuming a particular outcome.
Is a 50-year mortgage the same thing as an interest-only loan?
No. A 50-year mortgage is a fully amortizing loan spread across a longer term, where principal and interest are both paid down over time, just more slowly than a 30-year loan. An interest-only loan is structured differently, with payments initially covering only interest and no principal reduction during an interest-only period.
Will 50-year mortgages become a standard product soon?
That depends on regulatory and legislative decisions that hadn’t been finalized as of this writing. The concept has drawn both federal interest and public criticism, and expanding it into a standard, widely available product would require changes to the Qualified Mortgage rule or new legislation. Check current mortgage industry news for the latest status before assuming availability.
Does a longer mortgage term affect the mortgage interest tax deduction?
The mortgage interest deduction generally applies to interest actually paid, subject to applicable loan limits and whether you itemize deductions. A longer-term loan can mean paying more total interest over time, which could affect the deduction amount in a given year, but specific tax outcomes depend on your individual situation — consult a tax professional for guidance specific to your circumstances.
The Real Trade-Off
A 50-year mortgage is best understood as a trade: a lower required monthly payment today, in exchange for a longer repayment horizon, slower equity buildup, and — under current market conditions — a higher interest rate than a standard 30-year loan. That trade might make sense for some households and not for others; the point is understanding exactly what’s being exchanged before signing anything.
A mortgage isn’t simply a monthly bill. It’s a long-term financial commitment that interacts with savings, retirement planning, home equity, and the rest of the household budget. Before focusing on the lowest monthly payment, it’s worth asking three bigger questions: what will this loan cost over its full term, how quickly will it actually build equity, and what will the household do with whatever monthly savings it creates? The answers to those questions matter more than the number on the first line of the mortgage statement.