
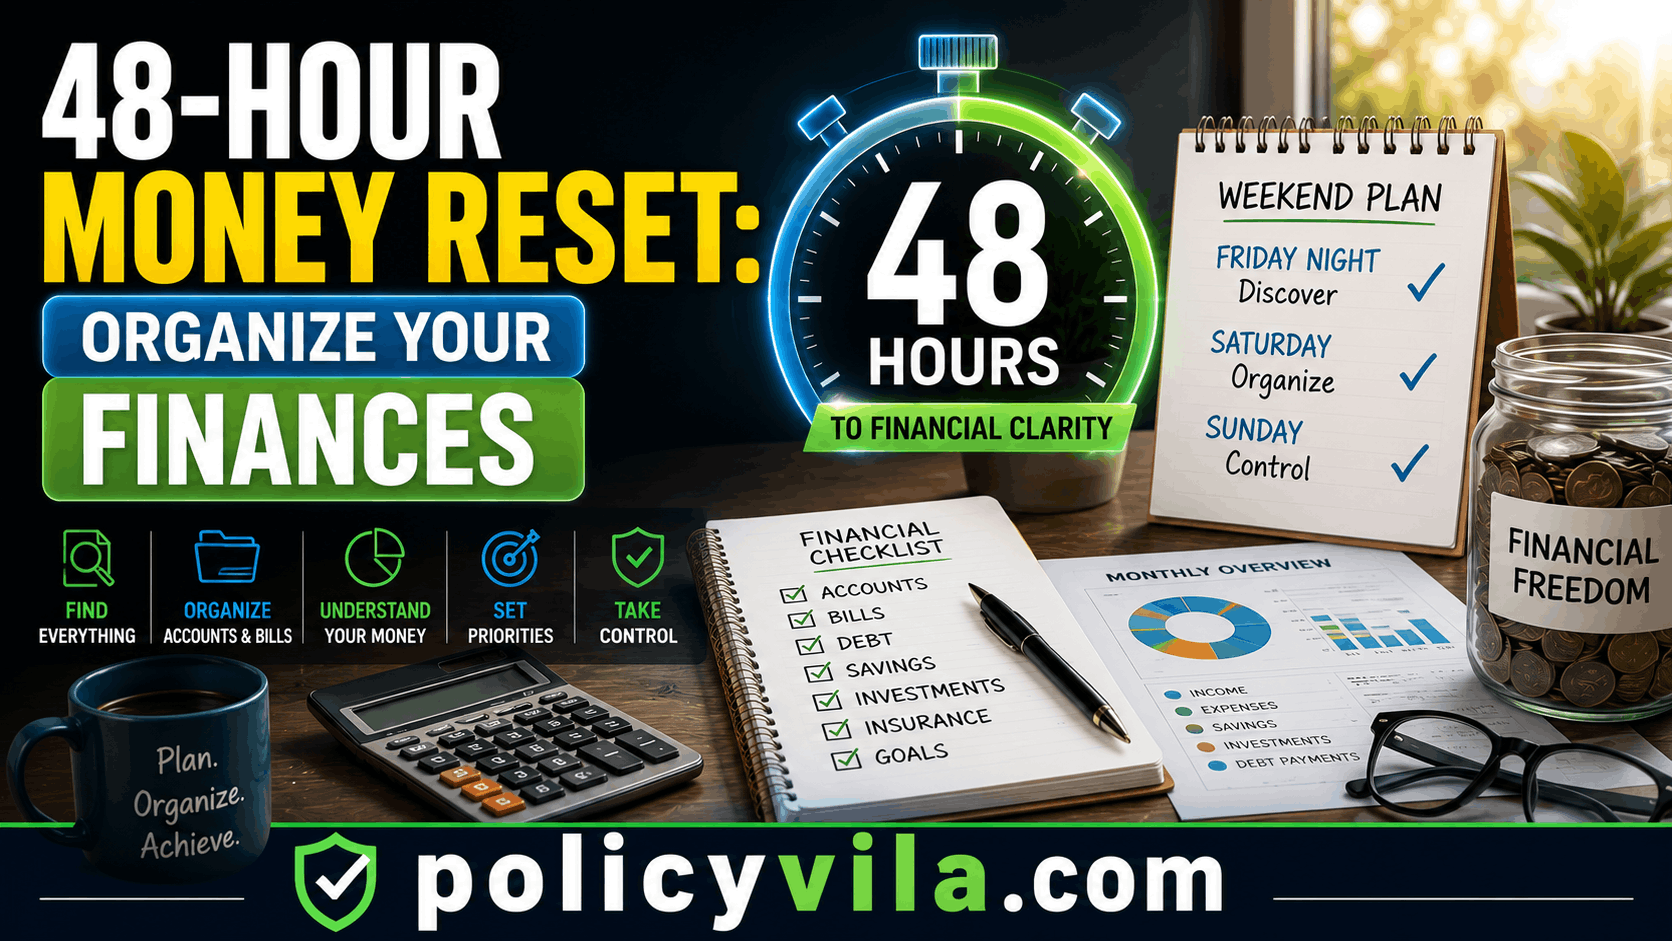
A 48-hour money reset won’t make you debt-free or wealthy by Monday. What it does is give you a clear, current picture of where your money actually stands, organized well enough that you can act on it with confidence.
Quick Answer
A 48-hour money reset is a structured weekend process for organizing your entire financial picture: Friday night you find every account, bill, and document; Saturday you organize that information into a simple money map, monthly flow, and debt list; Sunday you identify your biggest pressure points and set three financial priorities. The process follows one path — find, sort, understand, prioritize, control — and ends with a short routine for keeping things organized afterward.
Why Financial Life Feels More Complicated Than It Should
Nobody sets out to create financial chaos. It happens gradually — a bank account opened for one specific reason, a credit card taken for an introductory offer, a subscription that quietly renews, a loan payment added to the mix, a document buried under hundreds of unread emails.
The result isn’t necessarily a low income or poor decisions — it’s a lack of one clear view covering where your money actually is, what you owe, what you pay every month, what you’re saving, and which goals matter most. That’s a different problem than budgeting solves. A budget tells you how money should move; a reset helps you understand the whole system first, before you try to redirect any of it.
What a 48-Hour Money Reset Actually Involves
Think of it as a financial cleanup broken into three stages:
- Friday night — Discover. Find every account, bill, debt, and document you currently have.
- Saturday — Organize. Turn that raw information into a clear financial picture.
- Sunday — Control. Identify your priorities and set up a routine to keep things organized going forward.
The whole process follows one path: find, sort, understand, prioritize, control. It won’t resolve every financial problem in two days, but it removes the fog that makes every money decision feel harder than it needs to be.
Seven Rules to Follow Before You Start
- Use real numbers. Don’t estimate income, debt, or expenses — write down the actual figures, even the uncomfortable ones.
- Don’t hide uncomfortable information. Avoiding a credit card balance doesn’t remove it from your financial life.
- Don’t try to fix everything. This weekend is about organizing the system, not making ten major decisions at once.
- Keep one master list. A single central overview beats scattered notes across apps and papers — no special software required.
- Avoid emotional decisions. Don’t cancel insurance or make rushed changes out of stress. Understand the situation first.
- Keep the system simple. An overly detailed system is hard to maintain — the best one is whichever you’ll still be using three months from now.
- Prioritize clarity over immediate progress. You can’t improve a financial situation you don’t fully see yet.
Friday Night: Find Everything
Friday night is discovery, not fixing. Your only job is locating every important piece of your financial life — start with a blank document and build a master list as you go.
Financial Discovery Checklist
- Checking and savings accounts
- Credit cards
- Personal and student loans
- Retirement and investment accounts
- Insurance and housing documents
- Major monthly bills
- Recurring subscriptions
Don’t try to calculate net worth yet — that comes later, once you actually know what exists. It’s common to find more than expected: an old savings account you forgot about, a subscription still charging monthly, a retirement account left behind at a previous employer. None of that changes your income, but it changes how clearly you can see your own finances.
The 60-Minute Account Hunt
If you suspect there are accounts or payments you’ve lost track of, work through these in order:
- Search your email for terms like bank, statement, payment, loan, insurance, retirement, and subscription — financial emails often surface accounts you haven’t thought about in months.
- Review your phone — check financial apps and digital wallets, including the ones you rarely open.
- Check recent statements for payments, transfers, and recurring charges you might not immediately recognize.
- Review physical and digital documents for old loan paperwork, insurance policies, or account information.
Record what you find in a simple table:
| Financial Area | Account or Document | Monthly Cost | Notes |
|---|---|---|---|
| Banking | |||
| Credit | |||
| Debt | |||
| Insurance | |||
| Retirement | |||
| Subscriptions |
By the end of Friday night, you should have a considerably clearer sense of what actually exists — even before organizing any of it.
Saturday Morning: Build Your One-Page Money Map
This isn’t a traditional budget — it’s a snapshot. Fill in your best current numbers without spending an hour perfecting them:
| Money Area | Your Number |
|---|---|
| Monthly Income | |
| Essential Expenses | |
| Debt Payments | |
| Monthly Savings | |
| Emergency Savings | |
| Investments | |
| Estimated Net Worth |
The point is answering one question honestly: what does my financial life actually look like right now. This step often surprises people — a strong income paired with a weak savings system, or expenses that turn out lower than assumed. Either way, it turns vague worry into specific information you can act on.
Saturday: Map Your Monthly Money Flow
With the numbers in view, look at timing. When does income arrive? When are major bills due? Which payments are automatic, and which change month to month?
Income → Essential Bills → Debt → Savings → Flexible Spending
This isn’t a prescription for a specific budgeting method — it’s just a way to see how money actually moves through a typical month.
| Financial Problem | What It Feels Like | What to Organize |
|---|---|---|
| Bills arrive unpredictably | Constant low-grade stress | A payment calendar |
| Spending feels untracked | General confusion | An expense overview |
| Savings happen inconsistently | No visible progress | A savings schedule |
| Debt feels overwhelming | Avoidance | A consolidated debt list |
The Recurring Payment Cleanup
Recurring charges are easy to forget precisely because they don’t require a new decision each month. Review streaming services, memberships, software, cloud storage, phone plans, and annual renewals, then sort each one:
- Keep — you use it and understand what it costs.
- Review — you’re not sure it’s still worth what you’re paying.
- Cancel — you no longer use or need it.
The point isn’t eliminating every enjoyable expense — it’s awareness. A good financial system should support intentional spending, not manufacture guilt over every purchase.
read also: Gross Pay vs Take-Home Pay: Why Your Paycheck Is Smaller Than You Think
Saturday Afternoon: Create a Debt Control Sheet
Debt tends to feel heavier when the information is scattered across several statements and apps. Bringing it into one table changes that.
| Debt | Balance | Monthly Payment | Interest Information | Priority |
|---|---|---|---|---|
Include credit cards, personal loans, student loans, auto loans, and any other major obligations. You don’t need a full repayment strategy yet — understanding the complete picture comes first. Five scattered balances can feel overwhelming; the same five balances organized in one table are much easier to think through clearly.
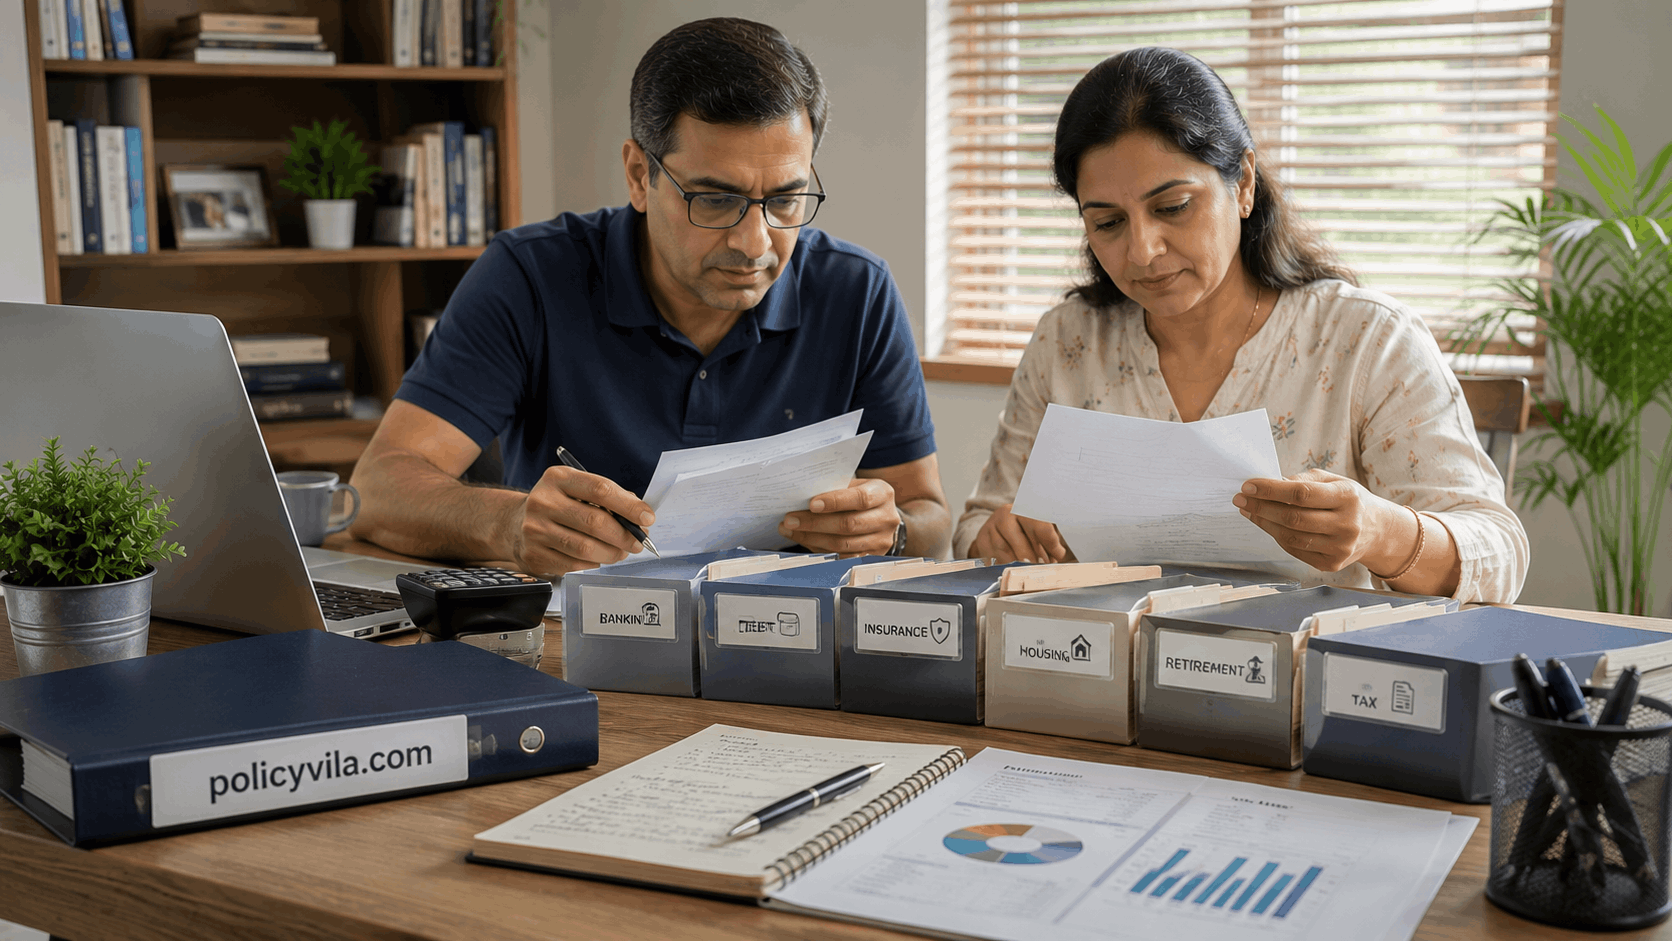
Saturday Evening: Organize Financial Documents
Paperwork is its own source of clutter. Group documents into simple categories:
- Income — pay records and income documents
- Banking — statements and account records
- Debt — loan agreements and payment documents
- Insurance — policy and coverage records
- Housing — mortgage, lease, or related records
- Retirement — account information and statements
- Taxes — tax-related records
- Family and legal — other important household documents
For digital files, a consistent naming pattern like Year – Category – Document makes everything searchable later. Keep sensitive financial information secure, and avoid storing it somewhere you wouldn’t trust with the rest of your personal data.
Sunday Morning: Find Your Pressure Points
With the information organized, Sunday is about interpreting it. Ask yourself:
- Which financial number worries me most?
- Which payment creates the most pressure?
- Where is my money system most confusing?
- What financial task do I keep avoiding?
- What financial risk would affect me most if it happened?
Sometimes the answer isn’t what you’d expect. A strong income with several financial accounts can still hide a real gap — no emergency savings system, for instance, with credit quietly covering unexpected costs instead. The goal here isn’t self-judgment; it’s identifying which area actually deserves attention next.
Sunday: Set Three Financial Priorities
Resist the urge to write twenty goals. Three is enough, organized around a simple framework:
- Protect — address risks that could create serious problems, such as inadequate emergency savings or gaps in financial protection.
- Stabilize — target whatever is creating ongoing pressure, like cash flow confusion or high-cost debt.
- Build — think ahead to longer-term goals, such as saving or building wealth over time.
The right priorities differ by household — a recent graduate and a family with children are typically working from very different starting points, and that’s expected.
The Reset Scorecard
| Financial Area | Organized? | Clear? | Next Action |
|---|---|---|---|
| Accounts | |||
| Bills | |||
| Debt | |||
| Savings | |||
| Documents | |||
| Goals |
Don’t aim for a perfect score. Where an area is still unclear, write a specific next action instead — “find old retirement account statement” is far more useful than “fix my retirement,” because a specific task is one you can actually complete.
Keeping the System Going After the Weekend
A weekend reset only pays off if it’s maintained. A short 15-minute monthly routine — checking account changes, recurring payments, savings progress, debt balances, and goal status — is usually enough. Daily monitoring tends to create stress without improving the actual decisions you make.
Every three months, go a step deeper: has income changed, have major expenses shifted, has debt moved, is the savings system working, did any accounts open or close, are the three priorities still the right ones. Financial circumstances change, and the organization system should be revisited alongside them rather than treated as permanent.
Mistakes That Undermine a Reset
- Trying to fix everything in one day. Clarity is the actual goal of the weekend — not resolution of every issue.
- Building an overly complicated spreadsheet. More columns don’t automatically create more control.
- Ignoring uncomfortable numbers. Avoidance is one of the most common drivers of ongoing financial confusion.
- Changing every financial decision at once. Give yourself time to understand the full picture before acting on it.
- Tracking too many categories. A system with excessive detail is hard to keep up.
- Copying someone else’s exact system. Financial lives differ enough that a template built for someone else rarely fits cleanly.
- Never revisiting the system. A one-time cleanup needs an ongoing, simple maintenance routine to stay useful.
If the Whole Idea Feels Overwhelming
Start smaller than the full weekend. Organize one account. Write down one number. Locate one document. Review one category of expenses. Then take a break before continuing.
The reset becomes far more manageable once you stop treating your entire financial life as a single massive problem and instead work through it in smaller, separate pieces.
Full Weekend Checklist
Friday Night
- Find all bank accounts
- Find credit cards
- Find loans
- Locate financial documents
- List recurring payments
Saturday
- Create a One-Page Money Map
- Review monthly money flow
- Sort recurring payments into keep, review, or cancel
- Create a debt control sheet
- Organize financial documents
Sunday
- Identify financial pressure points
- Choose three financial priorities
- Complete the reset scorecard
- Set up a monthly review routine
- Schedule a 90-day check-in
Frequently Asked Questions
What if I can’t finish everything in one weekend?
Spread it across two weekends if needed — the sequence matters more than the exact timing. Friday’s discovery work should come before Saturday’s organizing, but nothing requires finishing in exactly 48 hours.
Do I need budgeting software or an app for this?
No. A spreadsheet, a notebook, or even paper works fine — the reset is about visibility and structure, not the specific tool you use to track it.
What if my partner isn’t interested in doing this together?
You can complete your own portion individually and share the summarized results afterward, rather than requiring both people to sit through the entire process together.
Is this reset useful if I already use a budgeting app?
Yes — many budgeting apps track spending but don’t surface forgotten accounts, scattered documents, or old subscriptions. The reset fills in the parts a budget alone tends to miss.
What should I do if the numbers turn out worse than I expected?
Write them down accurately rather than adjusting them to feel better, and treat the discovery as the starting point for a plan rather than a verdict on your decisions so far.
How is this different from the household financial filing system?
The filing system is about long-term storage and findability for documents. The money reset is a one-time diagnostic weekend that produces a current financial snapshot — the two work well together, with the reset often revealing what the filing system should contain.
Should I repeat the full reset every year?
A full reset is most useful after a significant change — a new job, a move, a major purchase, or a shift in income — rather than on a fixed yearly schedule. Between resets, the shorter monthly and quarterly reviews are usually enough.
Final Thoughts
You don’t need to fix your entire financial life in one weekend. You need to finally see it clearly — because scattered accounts, confusing bills, and hard-to-find documents make every financial decision feel harder than it actually is.
The 48-hour money reset gives that clarity a structure: find what exists, organize it into something you can actually read at a glance, and decide what deserves attention first. Once the picture is clear, the decisions that follow tend to get a lot easier.