
This guide breaks down what each policy actually covers, who it protects, when you are required to carry it, how much it typically costs, and how to eventually stop paying for the one that can be removed. Whether you are shopping for your first home or trying to make sense of an existing mortgage statement, understanding this distinction will help you read your paperwork with more confidence and avoid costly assumptions.
Quick Answer
Homeowners insurance protects you, the property owner. It helps pay for repairs after covered events like fire, wind damage, or theft, and it can cover your liability if someone is injured on your property. Mortgage insurance protects the lender, not you. It reduces the lender’s financial exposure when a borrower makes a smaller down payment, and it does nothing to repair or replace your home or belongings. Most homeowners are required to carry homeowners insurance for as long as they own the property; mortgage insurance is often temporary and can sometimes be removed once you build enough equity.
Table of Contents
- What Homeowners Insurance Actually Covers
- What Mortgage Insurance Actually Covers
- Side-by-Side Comparison
- Why Lenders Require Different Types of Protection
- When Each Policy Is Required
- Where These Costs Fit in Your Monthly Payment
- How Much Each One Costs
- Can You Remove Mortgage Insurance?
- Common Mistakes to Avoid
- Practical Tips for Homeowners
- Frequently Asked Questions
- Final Thoughts
What Homeowners Insurance Actually Covers
Homeowners insurance is a property and liability policy built around one goal: helping you recover financially after something goes wrong with your home. A typical policy is made up of several types of coverage bundled together.
- Dwelling coverage — helps pay to repair or rebuild the structure of your home after a covered loss, such as fire or wind damage.
- Personal property coverage — helps replace belongings like furniture, electronics, and clothing that are damaged, destroyed, or stolen.
- Liability coverage — helps cover legal or medical costs if someone is injured on your property and you are found responsible.
- Additional living expenses (ALE) — helps pay for temporary housing, meals, and related costs if your home becomes uninhabitable during covered repairs.
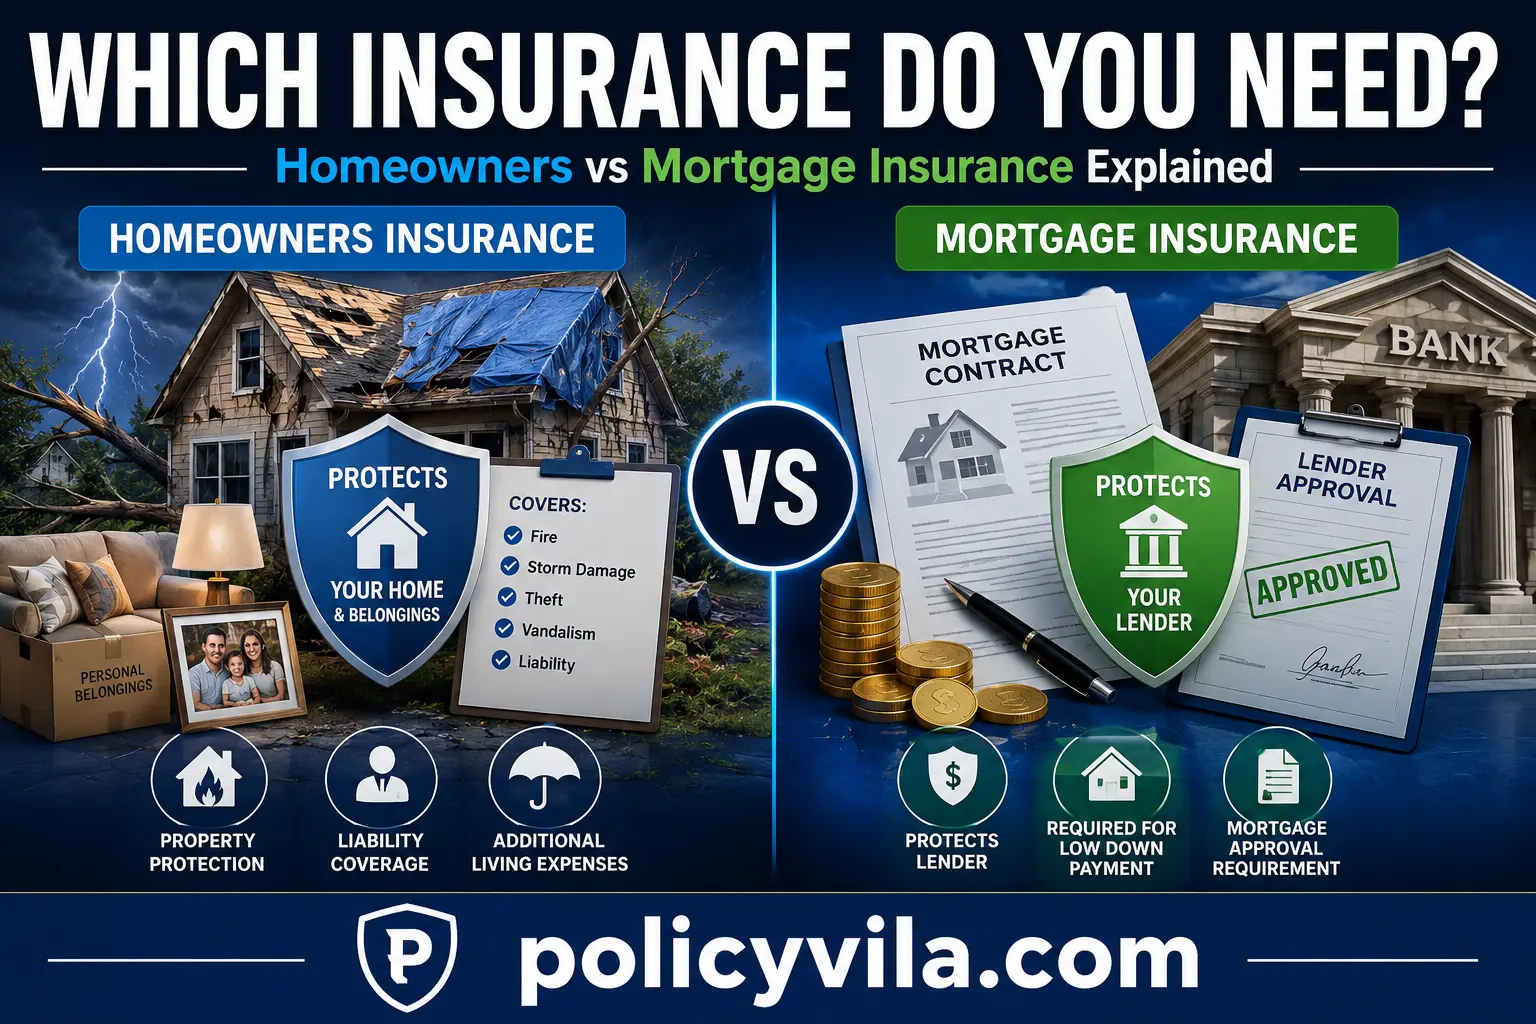
Common causes of loss that a standard policy may address include fire and smoke damage, windstorms and hail, theft and vandalism, and certain types of sudden water damage, such as a burst pipe. Coverage details, exclusions, and dollar limits vary by insurer and policy, so it is worth reading your declarations page rather than assuming a specific event is automatically covered.
[Relevant image: homeowner reviewing a homeowners insurance policy document at a kitchen table]
What Homeowners Insurance Typically Does Not Cover
Standard policies usually exclude or limit coverage for certain risks, including flood damage, earthquake damage, ordinary wear and tear, pest infestations, and damage from lack of maintenance. Homeowners in flood-prone or earthquake-prone regions often need to purchase separate policies for those specific risks.
What Mortgage Insurance Actually Covers
Mortgage insurance exists to protect the lender’s financial interest in the loan, not your home or belongings. When a borrower makes a small down payment, the lender is financing a larger share of the purchase price and taking on more risk if the loan later defaults. Mortgage insurance reduces that risk for the lender.
Even though the homeowner is usually the one paying the premium, the benefit of the policy is directed at the lender. If your roof is damaged in a storm or someone is injured on your property, mortgage insurance provides no help — that is homeowners insurance’s job.
Common Types of Mortgage Insurance
| Type | Typically Associated With | Notes |
|---|---|---|
| Private Mortgage Insurance (PMI) | Conventional loans with a down payment below a certain threshold | Can often be removed once sufficient equity is reached |
| Mortgage Insurance Premium (MIP) | Certain government-backed loan programs | Rules for removal vary and, on some loans, may last for the life of the loan |
| Guarantee or funding fees | Other government-backed loan programs | Structured differently than PMI; check program-specific rules |
Because requirements differ by loan type, lender, and program, the only reliable way to know exactly which rules apply to your mortgage is to review your loan disclosures or ask your loan officer directly.
Side-by-Side Comparison
| Feature | Homeowners Insurance | Mortgage Insurance |
|---|---|---|
| Primary purpose | Protects the home, belongings, and homeowner liability | Protects the lender’s financial interest in the loan |
| Who benefits | Homeowner | Lender |
| Who usually pays | Homeowner | Usually the borrower |
| Covers home damage | Yes, for covered perils | No |
| Covers personal belongings | Yes, for covered perils | No |
| Covers personal liability | Yes, in most policies | No |
| Required for most mortgages | Yes | Only under certain loan conditions, such as a low down payment |
| Can it be removed | Generally maintained for as long as you own the home | May be removable depending on loan type and equity |
Why Lenders Require Different Types of Protection
Homeownership involves two distinct financial interests. You want protection against physical loss to a major asset. Your lender wants protection against the possibility that a large loan will not be fully repaid. Because these are different problems, the mortgage industry uses two different tools to address them rather than combining everything into a single policy.
A simple comparison: consider two neighbors who buy similar homes in the same storm-prone area. One makes a 20% down payment and is not required to carry mortgage insurance. The other makes a 5% down payment and pays PMI each month. If a storm damages both roofs, each homeowner files a claim with their homeowners insurance company — mortgage insurance plays no role in either repair. But if one borrower later defaults on the loan, mortgage insurance may reduce the lender’s loss on that specific loan. Homeowners insurance never protects the lender against missed payments, and mortgage insurance never repairs a home.
When Each Policy Is Required
Homeowners insurance is required by nearly every mortgage lender as a condition of the loan, and it typically needs to stay in force for as long as the mortgage exists. Mortgage insurance, by contrast, depends on specific loan characteristics.
Factors That Commonly Trigger Mortgage Insurance
- A down payment below a lender’s or loan program’s threshold (often below 20% on conventional loans)
- A high loan-to-value (LTV) ratio
- Participation in certain government-backed loan programs
- Specific lender or investor requirements
Loan-to-value ratio is calculated by dividing your mortgage amount by the home’s value. For example, a $360,000 loan on a $400,000 home results in a 90% LTV. Generally, the higher the LTV, the more likely mortgage insurance will be required, and the higher its cost may be.
Where These Costs Fit in Your Monthly Payment
Many mortgage payments are commonly broken into five components, often abbreviated as PITI plus mortgage insurance:
- Principal — reduces the amount you originally borrowed and builds home equity
- Interest — the lender’s charge for financing the loan
- Property taxes — collected by local government and often paid through escrow
- Homeowners insurance — your property and liability protection
- Mortgage insurance — required only under certain loan conditions
Many lenders collect property taxes and insurance premiums through an escrow account, paying smaller monthly amounts instead of requiring one large annual bill. If your homeowners insurance premium increases at renewal, or your local property tax assessment changes, your total monthly payment can shift even on a fixed-rate mortgage — the interest rate itself has not changed, but the escrow portion has.
Example Monthly Payment Breakdown
| Expense | Example Amount |
|---|---|
| Principal | $620 |
| Interest | $1,180 |
| Property taxes | $320 |
| Homeowners insurance | $140 |
| Mortgage insurance | $95 |
| Total monthly payment | $2,355 |
This example is for illustration only. Actual payments vary based on loan amount, interest rate, location, and individual insurance costs.
How Much Each One Costs
Homeowners insurance and mortgage insurance are priced using entirely different variables, which is another reason they should never be treated as interchangeable expenses.
What Influences Homeowners Insurance Premiums
- Home value and rebuild/replacement cost
- Location and local weather or disaster risk
- Home age, construction type, and roof condition
- Coverage limits and deductible amount
- Claims history
What Influences Mortgage Insurance Costs
- Loan amount
- Down payment size
- Loan-to-value ratio
- Loan program and term
- Borrower’s credit profile, in some cases
| Cost Factor | Homeowners Insurance | Mortgage Insurance |
|---|---|---|
| Based on home value | Yes | No |
| Based on loan amount | No | Yes |
| Affected by down payment | No | Yes |
| Affected by property location | Yes | Limited |
| May change over time | Yes | Yes |
Because pricing structures differ so much, comparing “which is more expensive” in general terms is less useful than reviewing your own loan estimate and insurance quotes side by side.
Can You Remove Mortgage Insurance?
Unlike homeowners insurance, which most owners maintain for as long as they hold the property, mortgage insurance is sometimes temporary. Whether and how it can be removed depends heavily on your loan type.
Ways Mortgage Insurance May End
- Building equity through regular payments — as your principal balance drops, your loan-to-value ratio improves.
- Home appreciation — if your home’s market value rises, your equity position may improve faster than payments alone would produce, though appreciation is never guaranteed.
- Refinancing — a new loan with a lower loan-to-value ratio may eliminate mortgage insurance, though refinancing carries its own closing costs that should be weighed against the savings.
- Automatic termination rules — some conventional loans include automatic mortgage insurance cancellation once a specific equity threshold is reached, based on the original amortization schedule.
- Borrower-requested removal — many lenders allow you to formally request cancellation once you believe you’ve reached the required equity level, sometimes requiring a new appraisal.
Government-backed loans handle this differently, and on some programs mortgage insurance may last for the life of the loan regardless of equity. Because rules vary this much, the only reliable source of truth is your loan documents or a direct conversation with your servicer.
Common Mistakes to Avoid
- Assuming mortgage insurance protects you. It protects the lender’s investment in the loan, not your home or your family’s finances.
- Letting homeowners insurance lapse. If your policy expires while you have a mortgage, your lender can purchase “force-placed” coverage on your behalf, which is often more expensive and may offer less protection than a policy you choose yourself.
- Assuming mortgage insurance will disappear automatically. On some loan programs it will not, and you may need to take action, such as requesting removal or refinancing.
- Choosing homeowners insurance based on price alone. The cheapest policy may leave you underinsured for your actual rebuild cost or personal property value.
- Refinancing solely to drop mortgage insurance without checking the math. Closing costs can outweigh the savings if you don’t stay in the home long enough to break even.
Practical Tips for Homeowners
- Review your homeowners insurance declarations page once a year, especially after renovations, so your coverage keeps pace with your home’s current value.
- Keep a household inventory (photos, receipts, serial numbers) to make any future personal property claim faster and more accurate.
- Ask your lender in writing exactly which type of mortgage insurance applies to your loan and under what conditions it can be removed.
- Track your loan-to-value ratio periodically, especially if home values in your area are rising, since that can accelerate your path to removing PMI.
- Before refinancing to eliminate mortgage insurance, calculate the break-even point by comparing closing costs to your monthly savings.
Frequently Asked Questions
Is mortgage insurance the same as homeowners insurance?
No. Homeowners insurance protects your property and personal liability. Mortgage insurance protects the lender if you default on the loan. They are separate products with separate purposes, even though both may appear on the same mortgage statement.
Do I have to pay mortgage insurance for the life of my loan?
It depends on the loan type. Many conventional loans allow PMI to be removed once you reach a certain equity threshold. Some government-backed loan programs require mortgage insurance for the full loan term regardless of equity. Check your specific loan documents.
Can I shop around for mortgage insurance the way I shop for homeowners insurance?
Generally, no. Mortgage insurance is typically arranged by the lender as part of the loan structure, and you usually cannot choose your own provider the way you can with homeowners insurance.
What happens to my mortgage insurance if I refinance?
A refinance can remove, continue, or in some cases introduce mortgage insurance, depending on your new loan’s loan-to-value ratio and program. It’s worth comparing total loan costs, not just the interest rate, before deciding.
Does a higher credit score lower my mortgage insurance cost?
On many loan programs, a stronger credit profile can result in a lower mortgage insurance rate, though the loan-to-value ratio and down payment size are usually the biggest cost drivers. Ask your lender for specifics tied to your loan program.
Will my homeowners insurance cover flood or earthquake damage?
Typically not. Most standard homeowners policies exclude flood and earthquake damage, which require separate, specific policies. If you live in a higher-risk area, ask your insurer directly whether you need additional coverage.
Can my lender force-place insurance on me?
Yes. If your homeowners insurance lapses while you have an active mortgage, your lender can purchase a policy on your behalf and bill you for it. This “force-placed” coverage is often more expensive and may provide less protection than a policy you select yourself.
Does paying off my mortgage early affect either policy?
Paying down your loan faster builds equity more quickly, which can help you qualify for mortgage insurance removal sooner. Homeowners insurance, however, is unrelated to your loan balance — you’ll still need it for as long as you own the home, even after the mortgage is paid off.
Is mortgage insurance tax-deductible?
Tax rules around mortgage insurance premiums have changed over time and depend on your individual tax situation. Consult a qualified tax professional or the current IRS guidance for accurate, up-to-date information.
What’s the difference between PMI and MIP?
PMI (Private Mortgage Insurance) is generally associated with conventional loans. MIP (Mortgage Insurance Premium) is associated with certain government-backed loan programs and often follows different removal rules than PMI.
Does homeowners insurance cover my mortgage payments if I lose my job?
No. Homeowners insurance does not cover missed mortgage payments due to job loss or financial hardship. That is a separate concern from property protection, and homeowners facing hardship should contact their loan servicer directly to discuss options.
Final Thoughts
Homeowners insurance and mortgage insurance share a name but serve two very different financial purposes. One protects your home, belongings, and personal liability. The other reduces your lender’s risk on the loan itself and, in many cases, is a temporary cost tied to your down payment and equity position.
Knowing which policy does what helps you read your closing documents accurately, understand exactly what your monthly payment covers, and recognize when you may be eligible to remove mortgage insurance and lower your costs. Because rules vary by lender and loan program, always confirm the specifics of your own mortgage with your loan servicer or a licensed insurance professional before making decisions based on general guidance.