
It usually isn’t arbitrary. Errors and omissions (E&O) insurance, also called professional liability insurance, is priced around a detailed evaluation of the specific business: its industry, revenue, client contracts, claims history, and the coverage limits it’s requesting. Understanding what actually goes into that evaluation makes it possible to compare quotes intelligently instead of just picking the cheapest number on the page.
Quick Answer: How Much Does E&O Insurance Cost?
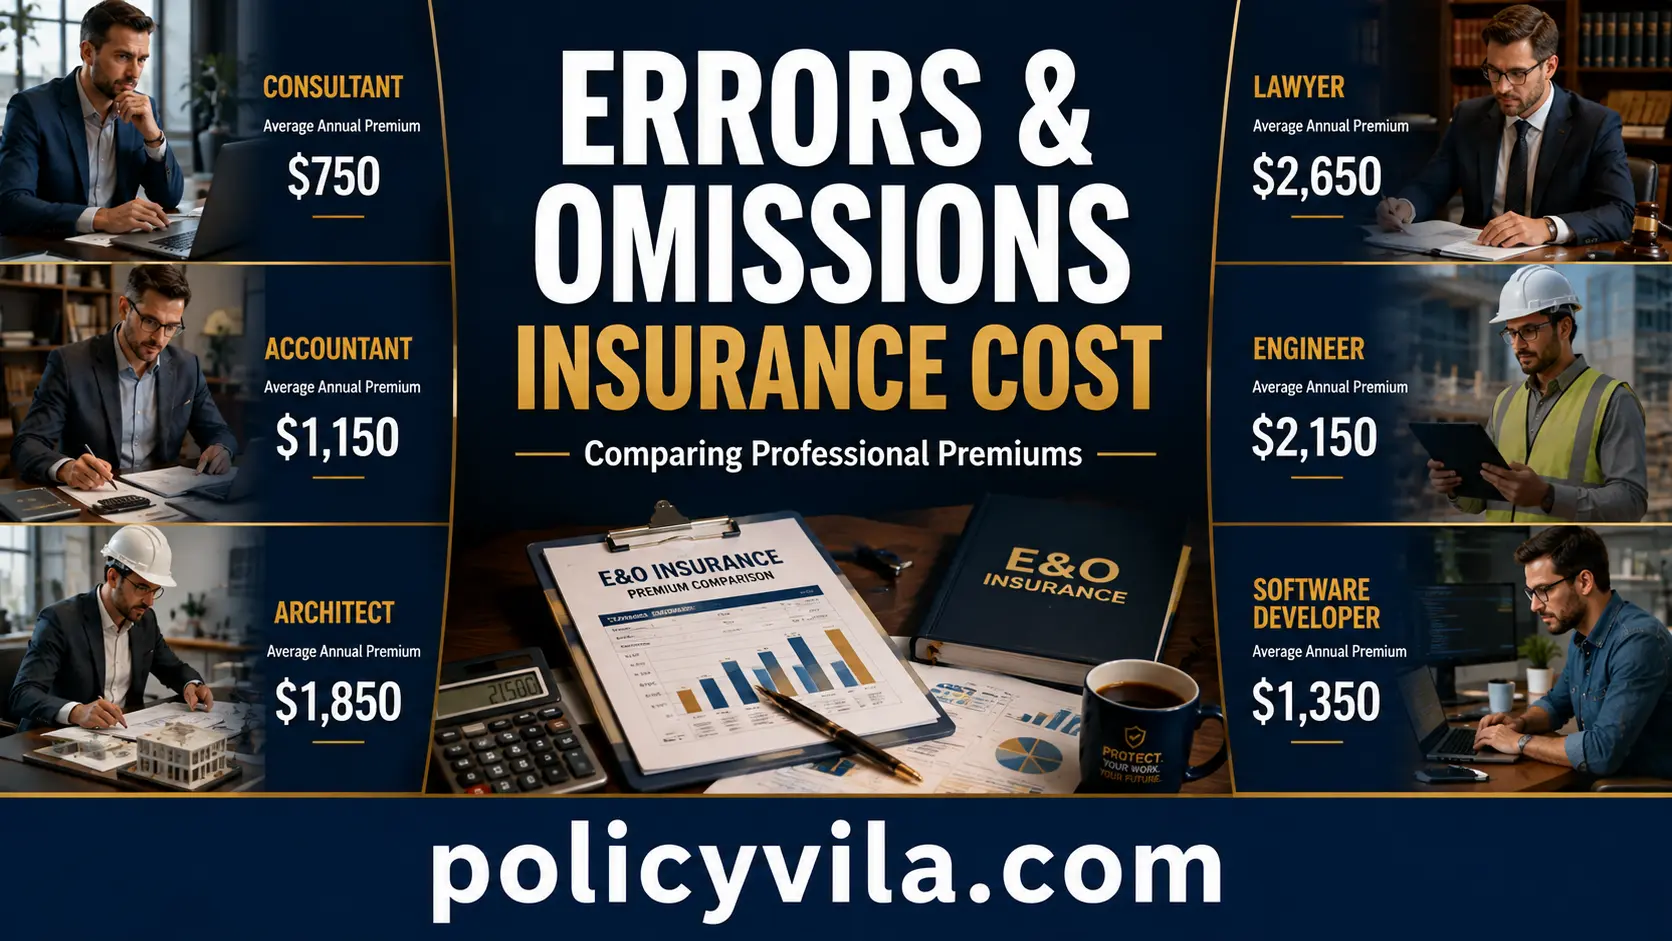
Industry data from several insurance marketplaces puts typical small-business E&O premiums somewhere in the range of $500 to $3,000 a year (roughly $40 to $250 a month), with a commonly cited median in the $700–$1,050 range. Lower-risk service businesses — consulting, design, writing — tend to sit toward the bottom of that range, while higher-risk professions such as engineering, architecture, accounting, and law commonly pay $3,000 to $12,000 or more per year. These figures come from published industry data, not a personalized quote — your actual premium depends on your specific profession, revenue, claims history, location, and the coverage limits you select.
Table of Contents
- The Premium Isn’t Random
- What E&O Insurance Actually Costs
- Why Industry Drives Pricing First
- Claim Frequency vs. Claim Severity
- Revenue, Business Size, and Growth
- Coverage Limits and Deductibles
- How Claims History Affects Future Pricing
- Location, Structure, and Other Underwriting Factors
- Business Practices That Can Support a Lower Premium
- E&O vs. General Liability
- Pros and Cons of Carrying E&O Coverage
- How to Compare Quotes Beyond the Premium
- Common Mistakes When Shopping for E&O Coverage
- Checklist Before You Choose a Policy
- Frequently Asked Questions
The Premium Isn’t Random
An E&O premium reflects an insurer’s estimate of how likely the business is to face a professional negligence claim, and how expensive that claim could become to defend or settle. Rather than a flat rate, insurers typically evaluate a combination of variables during underwriting, including:
- Type of professional services provided
- Years in business and industry experience
- Annual revenue
- Number of employees
- Client profile and typical contract size
- Geographic operations
- Previous claims
- Requested policy limits and deductible
Two businesses can request identical coverage limits and still land on very different premiums, because the insurer isn’t just pricing the policy — it’s pricing the business behind it.
What E&O Insurance Actually Costs
Published data from several business-insurance marketplaces converges on a similar general pattern, even though the exact figures vary by source and by year. Small businesses commonly pay somewhere in the $500–$3,000 annual range, with medians reported in the neighborhood of $700–$1,050 depending on the study and the mix of industries sampled. Higher-risk professions — engineering, architecture, accounting, finance, and law — regularly run $3,000 to $12,000 or more annually, while lower-risk service businesses like consulting or graphic design often land toward the lower end.
These are industry-wide figures, not a quote for any specific business — treat them as a rough planning range while you gather actual quotes, not as a number to hold an insurer to. Most small businesses that carry E&O coverage choose $1 million per-claim and $1 million aggregate limits, since that tends to satisfy the majority of client contract requirements, though your own required limit may differ based on your contracts and industry standards.
Why Industry Drives Pricing First
Before revenue or employee count, insurers usually look first at the nature of the professional services provided — often using an industry classification system to place the business into a risk category for pricing purposes. A bookkeeping error might mean correcting financial records. An engineering calculation error could delay a multimillion-dollar construction project. Both are professional mistakes, but the financial consequences differ enormously, and pricing reflects that difference from the start.
| Profession | Typical Relative Exposure |
|---|---|
| Graphic designer, freelance writer, social media manager | Lower |
| Marketing agency, PR firm, business or HR consultant | Moderate |
| IT/technology consultant, insurance agency | Moderate to high |
| CPA or accounting firm | High |
| Architect | High |
| Engineering firm | Very high |
| Law firm | Very high |
This table reflects general industry patterns, not guaranteed pricing for any specific business — actual exposure still depends on the individual firm’s client base, contract sizes, and operations.
Claim Frequency vs. Claim Severity
Underwriters generally weigh two separate measurements when pricing a profession: how often claims tend to happen (frequency), and how expensive those claims tend to be on average when they do (severity). Some professions see relatively frequent, lower-dollar disputes. Others see claims rarely, but at much higher financial stakes when they occur. Both dimensions factor into the final price — a profession doesn’t need frequent claims to carry a high premium if the claims it does see tend to be severe.
Revenue, Business Size, and Growth
Revenue isn’t treated as profit by underwriters — it’s treated as a signal of business activity. Higher revenue generally means more completed projects, larger client contracts, and more opportunities for a mistake to occur, which is why it factors into pricing even though it isn’t the whole picture.
Business size matters too, but not in the simple way many owners assume. A solo consultant managing million-dollar client engagements can present more professional liability exposure than a twenty-person firm doing lower-risk administrative work — insurers are pricing exposure, not headcount. As a business grows — new services, larger contracts, more employees, operations across multiple states — its professional liability profile typically shifts as well, which is why periodic policy reviews matter more than a “set it and forget it” approach to coverage.
Coverage Limits and Deductibles
Two businesses with similar revenue, industry, and claims history can still land on very different premiums once you factor in what they’re actually buying.
| Coverage Choice | General Premium Effect |
|---|---|
| Higher per-claim or aggregate limit | Generally increases premium |
| Lower per-claim or aggregate limit | Generally decreases premium |
| Higher deductible | May reduce premium, increases out-of-pocket cost per claim |
| Lower deductible | May increase premium, reduces out-of-pocket cost per claim |
| Added endorsements (cyber, media liability, IP, etc.) | Generally increases premium |
The per-claim limit caps what the insurer pays for a single claim; the aggregate limit caps total payouts across all claims during the policy period. A commonly chosen deductible for smaller E&O policies is around $2,500, though the right number depends on your cash reserves and how comfortable you’d be paying it on short notice. Choosing the lowest available deductible just to minimize a hypothetical out-of-pocket cost isn’t automatically the smartest move if it meaningfully raises your ongoing premium — weigh both numbers against your actual finances.
How Claims History Affects Future Pricing
A single prior claim doesn’t automatically make a business’s next premium dramatically higher, and a clean claims history doesn’t guarantee the lowest quote either. Underwriters generally look past the bare fact that a claim happened, into the surrounding circumstances: what caused it, how severe it was, whether it was resolved quickly, and whether the business changed anything afterward.
Patterns tend to matter more than a single large event. A business with one claim in eight years and clear process improvements afterward is often viewed differently than one with several similar claims in a short period — the second pattern suggests an ongoing operational issue rather than an isolated incident. Industry-wide claim trends can also move pricing broadly, even for businesses that have never filed a claim themselves, if claims are rising across a particular profession or specialty.
Location, Structure, and Other Underwriting Factors
A few additional variables round out most underwriting reviews:
- Location — local litigation trends, state regulations, and typical legal costs can all factor in, and businesses operating across multiple states may face different considerations than a single-location business
- Business structure — sole proprietorship, partnership, LLC, or corporation isn’t usually decisive on its own, but it’s one factor within the broader review
- Coverage history — continuous prior insurance coverage, without gaps or cancellations, can sometimes support more favorable underwriting than a spotty history
Business Practices That Can Support a Lower Premium
Some everyday operational choices quietly shape how underwriters view a business’s exposure, independent of industry or revenue:
- Strong documentation — written contracts, signed approvals, change orders, and clear client communication can make a claim investigation more straightforward if one ever happens
- Clear contracts — agreements that spell out scope of work, deliverables, timelines, and responsibilities reduce the misunderstandings that often turn into disputes in the first place
- Employee training and quality control — internal review steps, peer checks, and consistent procedures can reduce the kind of inconsistent-process mistakes that drive claims
- Cybersecurity practices — increasingly relevant for firms storing client financial or confidential data, since data-handling risk has become part of many professional liability conversations
None of this guarantees a specific discount — underwriting practices vary by insurer — but demonstrating organized, documented business practices generally works in a business’s favor rather than against it.
E&O Insurance vs. General Liability Insurance
| Coverage | What It Generally Addresses |
|---|---|
| Errors and omissions (E&O) / professional liability | Claims that professional advice, services, designs, or recommendations caused a client financial harm |
| General liability | Third-party bodily injury, property damage, and certain other claims unrelated to professional advice |
These aren’t interchangeable, and many businesses that provide professional services carry both — a consulting firm can face a slip-and-fall claim from a visitor to its office (general liability) as easily as a claim that its advice caused a client financial loss (E&O). Confirm with your insurer which risks each policy actually covers rather than assuming one substitutes for the other.
Pros and Cons of Carrying E&O Coverage
| Pros | Cons / Limitations |
|---|---|
| Can help cover legal defense costs even for meritless claims | Adds a recurring annual or monthly expense |
| Often required or expected under client contracts, especially with larger clients | Premiums can rise significantly for higher-risk professions |
| Can protect personal and business assets from a costly negligence claim | Coverage limits mean a very large claim could still exceed the policy |
| Available across a wide range of professions and business sizes | Choosing limits too low to meet client requirements can create contract problems later |
How to Compare E&O Quotes Beyond the Premium
Comparing quotes by the annual premium alone is like comparing office chairs by weight — it’s a number, but not the one that actually tells you what you’re getting.
| What to Compare | Quote A | Quote B |
|---|---|---|
| Annual premium | ||
| Per-claim limit | ||
| Aggregate limit | ||
| Deductible | ||
| Key exclusions | ||
| Endorsements included | ||
| Defense cost structure | ||
| Claims-made or occurrence basis |
Pay particular attention to whether the policy is written on a claims-made basis — common for E&O coverage — since that affects what happens if you switch insurers or stop carrying coverage later, and whether an extended reporting period is available. Ask your insurer directly rather than assuming based on the summary page.
Common Mistakes When Shopping for E&O Coverage
Comparing premiums without comparing limits
Fix: Match per-claim and aggregate limits across quotes before treating a price difference as meaningful.
Assuming general liability already covers professional mistakes
Fix: Confirm with your insurer that professional negligence claims are actually covered — general liability usually doesn’t address them.
Choosing the lowest deductible without checking the premium trade-off
Fix: Compare what a lower deductible actually costs in higher premium against what you’d realistically pay out of pocket at a higher deductible.
Not checking client contract requirements before buying
Fix: Review your contracts for specific limit or coverage requirements before choosing a policy that might not satisfy them.
Letting coverage go stale as the business grows
Fix: Revisit coverage when revenue, services, employee count, or typical contract size changes meaningfully.
Ignoring exclusions
Fix: Ask specifically what’s excluded — particularly around intentional misconduct, contractual liabilities, and prior known issues — before assuming broad coverage.
Checklist Before You Choose a Policy
- Confirm what your typical client contracts require for coverage limits
- Get quotes from more than one insurer using identical limits
- Compare per-claim and aggregate limits, not just the premium
- Choose a deductible you could comfortably pay on short notice
- Review exclusions specific to your profession
- Confirm whether the policy is claims-made or occurrence-based, and what that means for coverage after you switch insurers
- Ask whether cyber, media liability, or other endorsements are relevant to your work
- Revisit coverage annually or after any major change in revenue, services, or staff
Frequently Asked Questions
Why do two businesses in the same industry get different E&O quotes?
Even within the same profession, revenue, client contract size, claims history, requested limits, and location can all differ — and each one factors into the underwriting evaluation separately.
Does E&O insurance cost more for a solo freelancer or a larger firm?
It depends on exposure, not headcount. A solo consultant handling large, high-stakes client contracts can face a higher premium than a larger firm doing lower-risk work, since insurers price the potential claim severity of the work itself.
Can bundling E&O with other coverage lower the cost?
Sometimes. Carriers may offer a discount when E&O is bundled with cyber liability or a business owner’s policy, though the actual savings depend on the insurer and your specific coverage needs — ask directly rather than assuming a bundle is automatically cheaper.
Does a higher deductible always save meaningful money?
Not necessarily by a large margin — the premium reduction from raising a deductible varies by insurer and policy. Compare actual quotes at different deductible levels rather than assuming a fixed savings rate.
What is a claims-made policy, and why does it matter for E&O insurance?
A claims-made policy generally covers claims made while the policy is active, regardless of when the underlying incident occurred, often with the option to extend reporting after the policy ends. This matters because switching insurers or letting a policy lapse can affect coverage for past work — ask your insurer how this applies to your specific situation.
Does one claim guarantee a much higher premium at renewal?
Not automatically. Insurers generally look at the circumstances — what caused the claim, its severity, and whether the business made changes afterward — rather than treating a single incident as an automatic red flag.
How much E&O coverage do most small businesses actually carry?
A $1 million per-claim and $1 million aggregate limit is a common baseline that tends to satisfy many client contracts, though your appropriate limit depends on your typical project size, industry, and client requirements.
Is E&O insurance required by law?
Generally, no state broadly mandates E&O coverage for all professions, though specific licensing boards, industries, or client contracts may require it. Check your profession’s licensing requirements and your client agreements directly.
Can improving business practices actually lower an E&O premium?
It can support more favorable underwriting over time, since documentation, clear contracts, and quality-control practices reduce the kind of preventable errors that lead to claims — though the exact effect on pricing varies by insurer and isn’t guaranteed.
How often should a business review its E&O coverage?
An annual review is a reasonable baseline, and it’s worth revisiting sooner after any significant change — new services, a jump in revenue, larger client contracts, or additional employees — since these can shift the business’s actual exposure.
Final Thoughts
Errors and omissions insurance pricing isn’t a mystery once you know what insurers are actually evaluating: the nature of your professional work, your revenue and growth trajectory, your claims history, and the specific limits and deductible you’re requesting. None of these factors work in isolation — a low-revenue business in a high-stakes profession can pay more than a larger business doing lower-risk work.
The lowest premium on a page isn’t automatically the best value, and the highest premium doesn’t automatically mean the strongest protection. Compare quotes using identical limits, understand what each policy excludes, and revisit your coverage as your business changes — that combination will tell you far more than the number at the top of any single quote.