
Car Insurance Deductible vs. Premium: Understanding the Real Trade-Off
A renewal notice arrives showing a higher monthly premium. Scanning the options, one line stands out: raising the deductible would bring the price back down. At first glance, this looks like a simple choice — pay less every month, or accept a bigger bill if something happens to the car.
It’s not quite that simple. The real question is whether the monthly savings are worth a larger potential out-of-pocket cost after a covered loss — and that answer depends as much on your own finances as it does on the numbers on the quote.
Quick Answer: Deductible vs. Premium
Your premium is the recurring cost of keeping a policy active. Your deductible is the amount you’re responsible for paying toward certain covered losses before your insurer pays the rest. The National Association of Insurance Commissioners (NAIC) confirms the general relationship: higher deductibles are generally associated with lower premiums, and a policy with a $1,000 deductible typically costs less than the same policy with a $500 deductible. But the “better” choice isn’t universal — it depends on how much you’d actually save, what you could comfortably pay out of pocket after a claim, and whether the coverage you’re comparing is genuinely equivalent.
Table of Contents
- The Two Numbers That Shape Your Bill
- What Actually Sets Your Premium
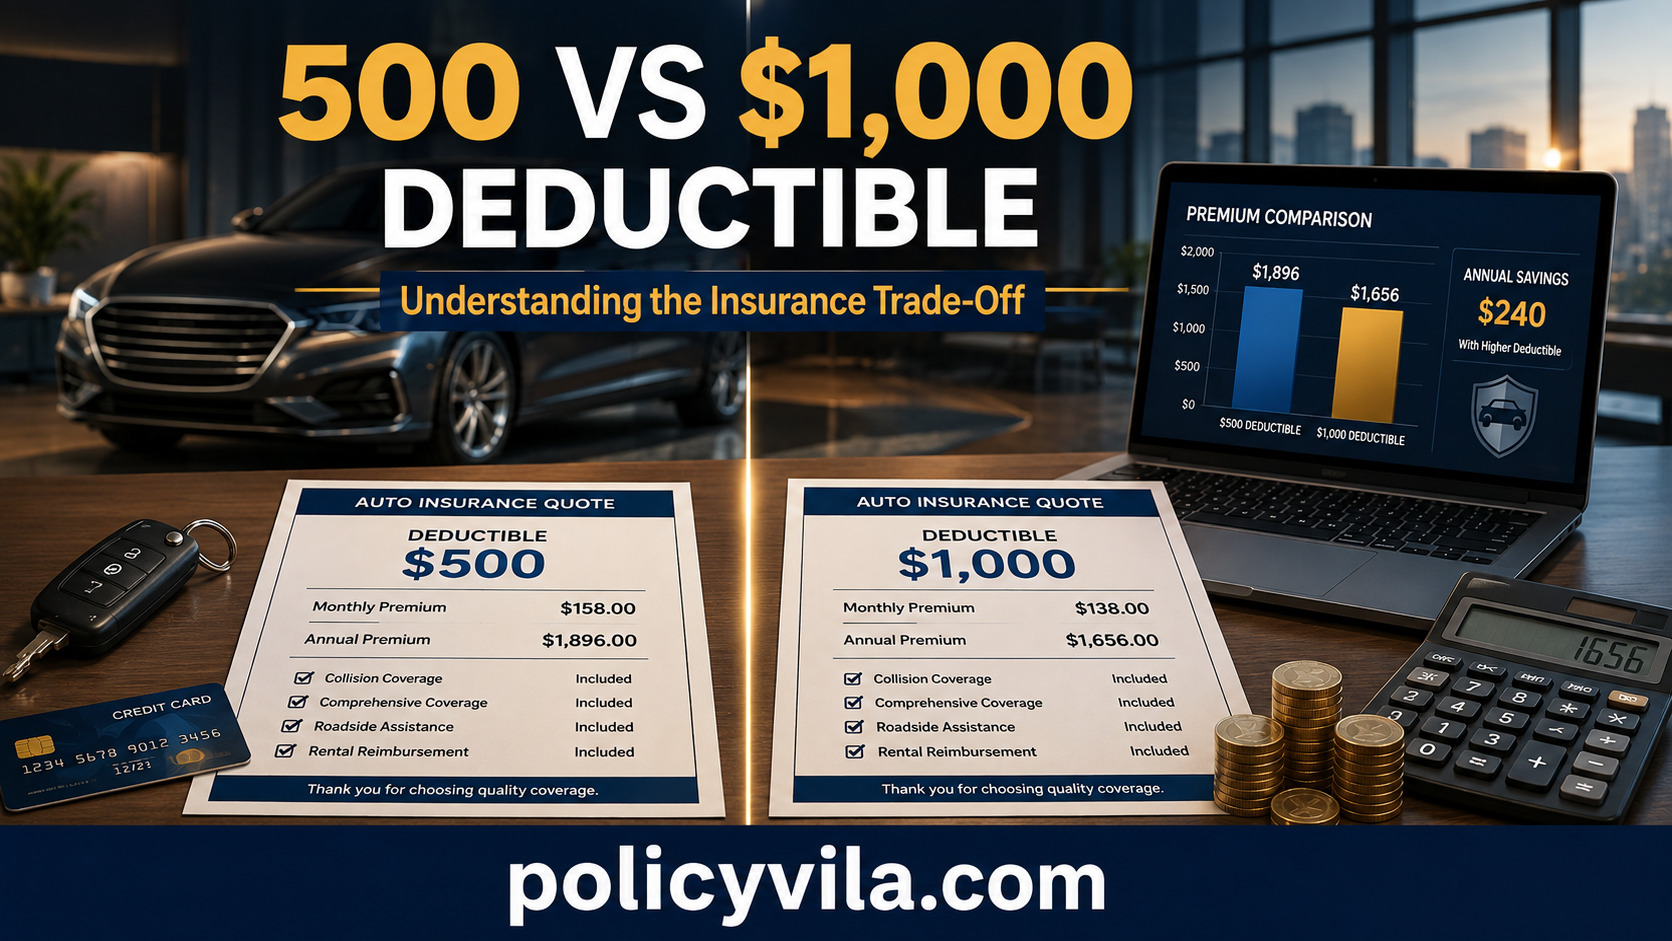
- A Worked Example: $500 vs. $1,000 Deductible
- Why Emergency Savings Changes the Answer
- Collision, Comprehensive, and Liability Aren’t the Same Conversation
- How Vehicle Value and Financing Change the Calculation
- Pros and Cons of Choosing a Higher Deductible
- How to Compare Two Quotes Fairly
- Common Mistakes That Make a Cheap Policy Look Cheaper
- The Annual Policy Review
- Checklist Before You Change Your Deductible
- Frequently Asked Questions
The Two Numbers That Shape Your Bill
A premium and a deductible do very different jobs inside the same policy.
| Feature | Premium | Deductible |
|---|---|---|
| What it represents | The cost of maintaining coverage | What you pay toward certain covered losses before insurance pays the rest |
| When it’s paid | On the policy’s payment schedule | Only when a covered claim triggers it |
| Applies to every payment period? | Yes | No — only when relevant to a claim |
| Main financial effect | Recurring, predictable expense | Potential, unpredictable out-of-pocket expense |
A policy with a lower premium can still have a higher deductible or a different coverage structure. A policy with a higher premium isn’t automatically better either — coverage limits, exclusions, and other terms still matter. NAIC’s consumer guidance frames this directly: raising your deductible is one legitimate way to lower your premium, provided you’re comfortable absorbing more of the loss yourself if a claim happens.
What Actually Sets Your Premium
There’s no universal auto insurance price. Insurers evaluate a range of characteristics, and every insurer’s pricing model differs somewhat. Commonly considered factors include:
- Driving history
- Location
- Vehicle characteristics
- Coverage selections and limits
- Claims history
- Deductible selections
NAIC notes that insurers commonly check claims history through databases such as the Comprehensive Loss Underwriting Exchange (CLUE), and that consumers have a right to a free copy of their own CLUE report. That’s one reason two drivers with similar vehicles can receive very different quotes — the deductible is only one variable in a larger pricing model, not a simple menu where every $500 increase produces an identical discount.
A Worked Example: $500 vs. $1,000 Deductible
Consider a hypothetical driver comparing two otherwise comparable policies:
| Option A | Option B | |
|---|---|---|
| Deductible | $500 | $1,000 |
| Monthly premium | $150 | $130 |
| Annual premium | $1,800 | $1,560 |
| Annual premium savings | — | $240 |
| Additional deductible exposure | — | $500 |
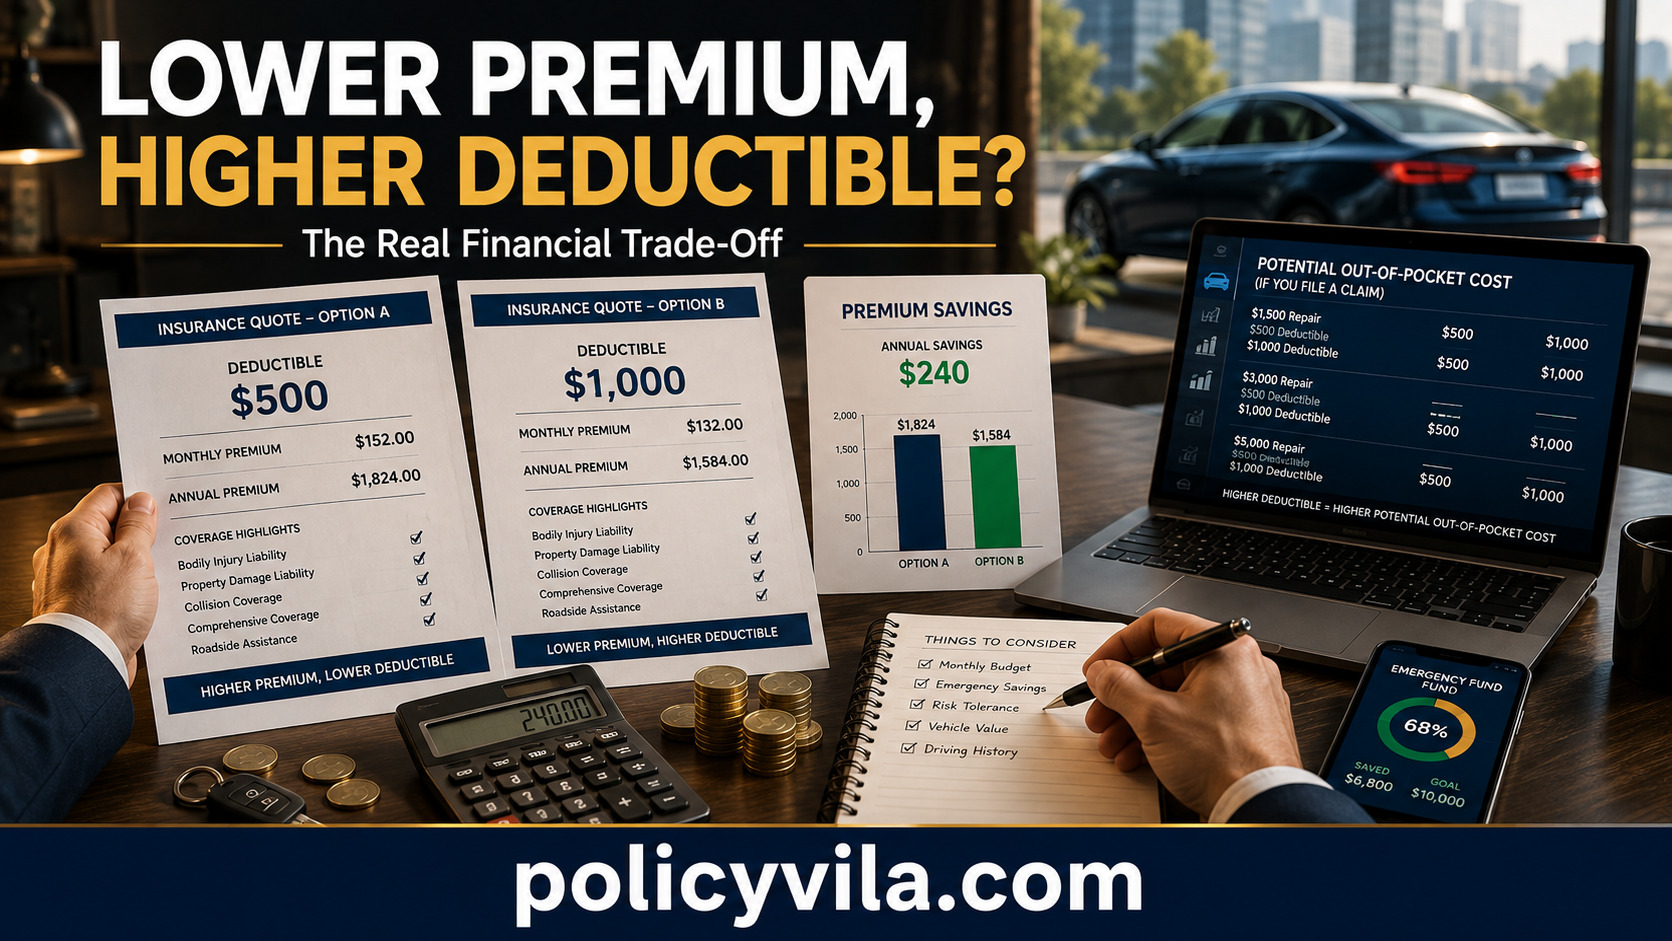
Choosing Option B saves this hypothetical driver $240 a year in exchange for $500 more exposure if a covered claim happens where the deductible applies. That doesn’t automatically make Option B better or worse — the driver isn’t “losing” $500 just by picking the higher deductible, since it only becomes relevant if an applicable claim actually occurs.
One way to frame the trade-off: at $240 in annual savings, it would take a little over two years of savings to match the extra $500 of exposure. But claims don’t happen on a schedule. A driver might go five years without a claim, or face one next month. The math is a framework for thinking about the trade-off — not a formula that produces a single correct answer.
Before treating any premium difference as a real saving, check whether the two quotes are actually comparable: same coverage limits, same deductibles applied to the same coverage types, and similar exclusions. A cheaper quote isn’t a genuine bargain if it’s quietly providing less protection.
Why Emergency Savings Changes the Answer
The same deductible can mean very different things to two different households.
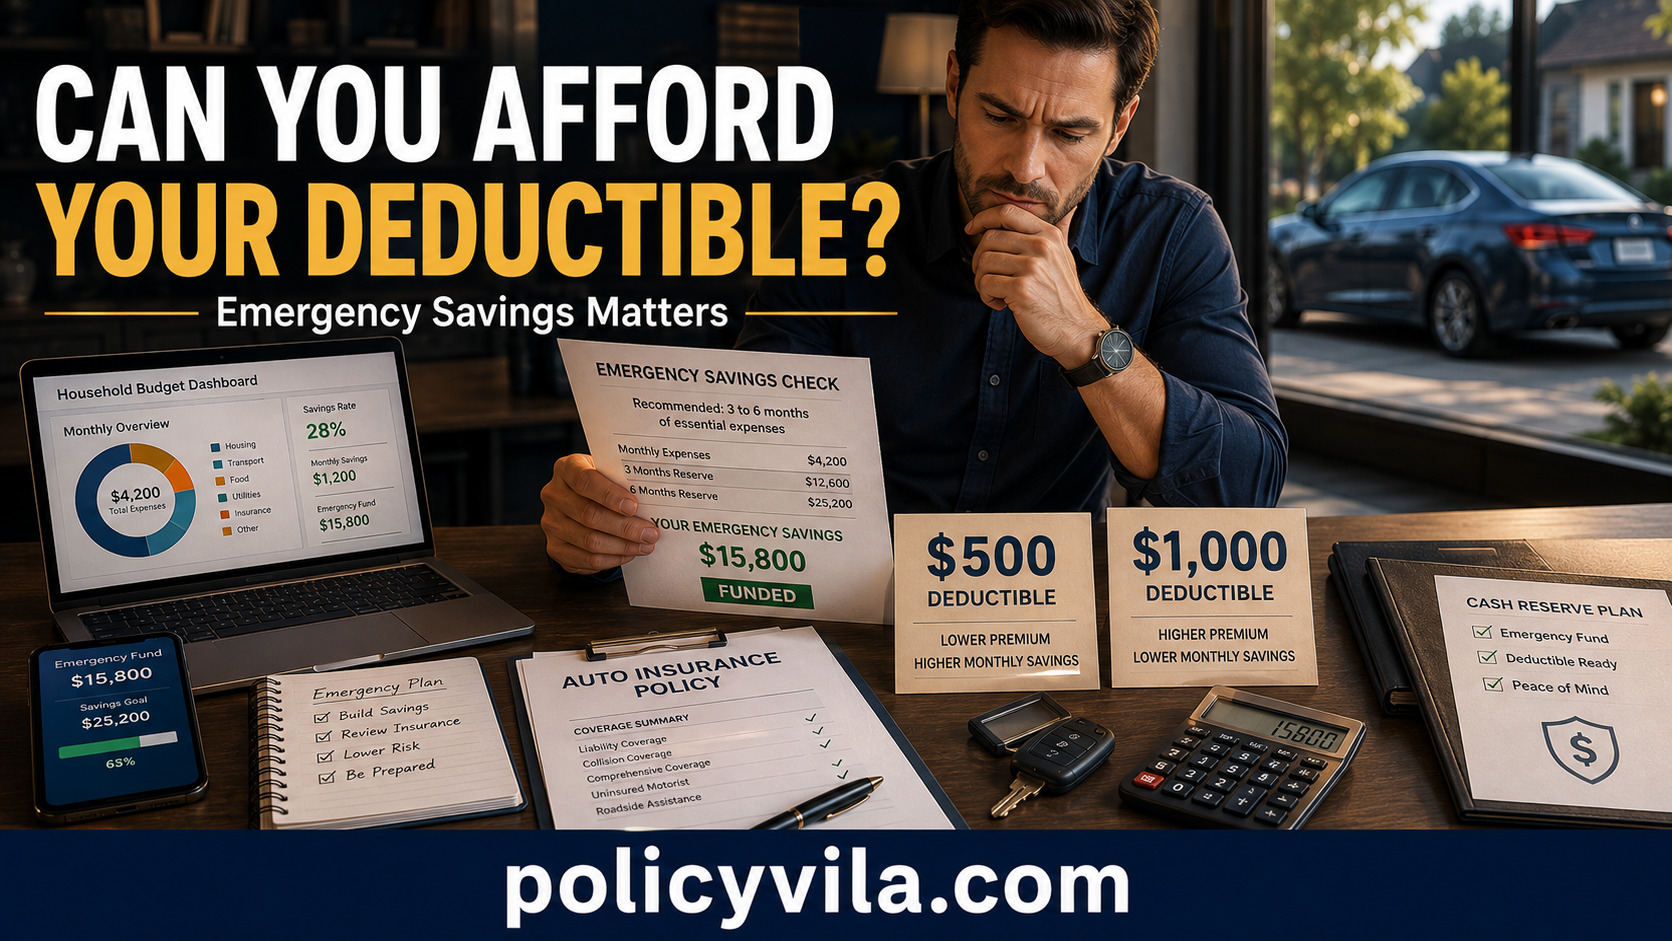
A driver with limited emergency savings and tight monthly obligations could face a real cash-flow problem if a $1,000 deductible suddenly came due. A driver with a larger reserve and stable income might absorb the same deductible without much disruption. Neither situation dictates a universally correct deductible — it means the decision has to be evaluated against your own finances, not just the premium quote.
A useful gut-check: would paying this deductible mean using a credit card, missing another bill, or draining savings you’d rather keep intact? If the honest answer is yes, the lower premium may not be worth what it’s asking you to risk.
Collision, Comprehensive, and Liability Aren’t the Same Conversation
Deductibles don’t apply uniformly across every part of a policy.
| Coverage | General Purpose | Deductible Typically Applies? |
|---|---|---|
| Collision | Covered damage to your vehicle from a collision | Often, depending on the policy |
| Comprehensive | Certain non-collision losses — theft, hail, windstorm, flood, fire, or hitting an animal | Often, though at a different dollar amount than collision |
| Liability | Covered injury or property damage you cause to others | Generally structured differently from a standard vehicle-damage deductible |
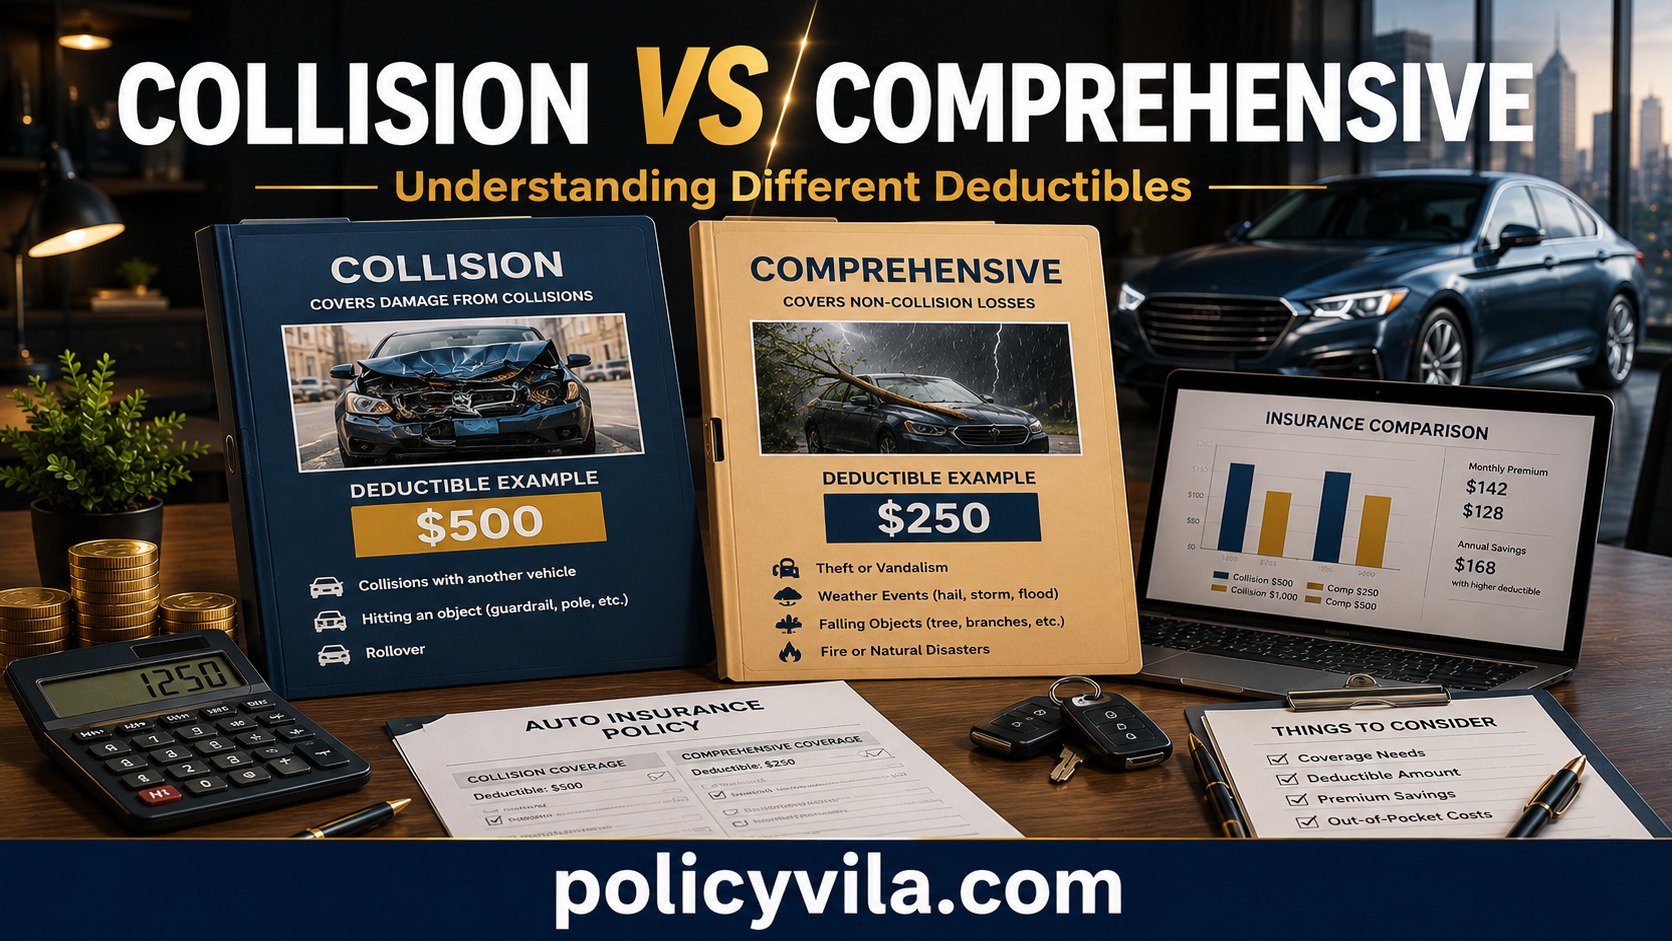
A single policy might carry a $500 collision deductible and a $250 comprehensive deductible at the same time — NAIC’s consumer guidance notes that some insurers don’t even apply a deductible to certain comprehensive claims, like a cracked windshield. That’s why “what’s my deductible” isn’t always a complete question; a more useful one is “what’s the deductible for each specific coverage I have.”
Liability coverage works differently still. If you’re found responsible for another person’s injury or property damage, that claim is typically handled through your liability limits, not a standard collision or comprehensive deductible. Don’t assume a single deductible number applies to every type of claim your policy could face.
How Vehicle Value and Financing Change the Calculation
An older vehicle that’s lost significant market value deserves a second look at collision and comprehensive coverage. If a car is only worth a few thousand dollars, a high deductible paired with that coverage might leave little financial benefit in a total-loss scenario, though dropping the coverage entirely isn’t automatically the right call either — weigh current vehicle value, premium cost, and what you’d actually receive in a claim.
Financing changes the picture further. NAIC notes that while collision and comprehensive coverage generally aren’t required by state law, lenders commonly require them for financed or leased vehicles — so the deductible decision may not be entirely yours to make while a loan is outstanding. It’s also worth knowing that standard auto policies typically don’t cover the gap between a vehicle’s market value and what’s still owed on a loan; that gap is what guaranteed auto protection (GAP) insurance is designed to address, and it’s a separate product from your regular deductible and premium.
Pros and Cons of Choosing a Higher Deductible
| Pros | Cons / Limitations |
|---|---|
| Can meaningfully lower your recurring premium | Increases what you owe out of pocket after an applicable covered claim |
| Frees up monthly cash flow if you rarely file claims | Can create a real financial strain if emergency savings are limited |
| Rewards drivers with a clean claims history and stable finances | The premium reduction isn’t guaranteed to be proportional to the deductible increase |
| Simple lever to adjust cost without changing coverage limits | A very high deductible can make filing smaller claims impractical |
How to Compare Two Quotes Fairly
Picture two hypothetical quotes: Quote A at $150 a month with a $500 collision deductible and $250 comprehensive deductible, and Quote B at $130 a month with a $1,000 collision deductible and $500 comprehensive deductible. Quote B looks cheaper at first glance, but it isn’t a cheaper version of the same policy — several variables changed at once.
Step 1: Line up the annual cost
Multiply each monthly premium by 12 so you’re comparing full-year numbers, not just the monthly sticker price.
Step 2: Match the deductibles to the same coverage type
Compare collision deductibles to collision deductibles, and comprehensive to comprehensive — not a blended or averaged number.
Step 3: Confirm the coverage limits are equal
A lower quote sometimes reflects lower liability or physical-damage limits rather than genuinely better pricing.
Step 4: Review exclusions and conditions
Two policies can look similar until you read what each one specifically excludes.
Step 5: Weigh the savings against your own finances
Only after the coverage is confirmed equivalent does it make sense to ask whether the premium difference is worth the added deductible exposure for your situation.
Common Mistakes That Make a Cheap Policy Look Cheaper
Looking only at the monthly payment
Fix: Convert to an annual figure and weigh it against the deductible difference, not just the smaller monthly number.
Ignoring the deductible entirely
Fix: Ask for the specific deductible on every coverage type, not just a general figure.
Assuming every deductible is the same across coverage types
Fix: Confirm collision and comprehensive deductibles separately — they’re often different amounts.
Assuming a deductible applies to every kind of claim
Fix: Remember that liability coverage typically works through limits, not a standard vehicle-damage deductible.
Comparing quotes with different coverage limits
Fix: Match liability and physical-damage limits before comparing price at all.
Skipping the exclusions
Fix: Read what each policy specifically excludes — a lower price sometimes means narrower protection.
Forgetting your own emergency savings
Fix: Ask whether you could pay the deductible tomorrow without disrupting your regular finances.
Not checking your lender’s requirements
Fix: If your car is financed or leased, confirm what minimum coverage and deductible range your lender actually allows before assuming you have full flexibility.
The Annual Policy Review
NAIC specifically recommends reviewing auto insurance policies once a year to confirm the coverage still matches your circumstances. A useful annual review covers:
- Vehicle information and any changes to it
- Drivers listed on the policy
- Coverage selections and liability limits
- Collision and comprehensive deductibles
- Premium and payment schedule
- Major changes in household circumstances or vehicle use
The purpose isn’t necessarily to chase the lowest possible premium every year — it’s making sure you actually understand what you’re paying for and what financial exposure remains if something goes wrong.
read also: Public Liability Insurance for Self-Employed in 2026: Costs, Coverage & How to Choose
Checklist Before You Change Your Deductible
- Know your current monthly and annual premium
- Know your current collision and comprehensive deductibles separately
- Confirm coverage limits are identical across any quotes you’re comparing
- Review exclusions and conditions on each policy
- Calculate the real annual savings, not just the monthly difference
- Check whether you could comfortably pay the higher deductible tomorrow
- Confirm any lender requirements if the vehicle is financed or leased
- Consider your vehicle’s current market value before adjusting physical-damage coverage
- Pull your CLUE report if you’re unsure what claims history insurers are seeing
Frequently Asked Questions
What is a car insurance deductible?
It’s the amount you’re responsible for paying toward certain covered losses before your insurer pays the remaining covered amount, subject to the policy’s terms, limits, and exclusions.
What is a car insurance premium?
It’s the amount you pay to keep your policy active, according to your policy’s payment schedule — monthly, semi-annually, annually, or another arrangement.
Does a higher deductible always lower the premium by a predictable amount?
Not by a fixed formula. Insurers apply their own pricing models, so a $500 increase in deductible won’t necessarily produce the same discount from one insurer to the next. Compare actual quotes rather than assuming a standard rate of savings.
Can collision and comprehensive coverage have different deductibles on the same policy?
Yes, and it’s common. A policy might carry a $500 collision deductible alongside a $250 comprehensive deductible, and some insurers waive the deductible entirely for specific comprehensive claims like windshield damage.
Does liability coverage have a deductible like collision or comprehensive?
Generally, no — liability claims are typically handled through your liability limits rather than a standard vehicle-damage deductible. Review your specific policy language to confirm how it applies to your coverage.
Should I choose a higher deductible if I have a clean driving record?
A clean record lowers the statistical likelihood you’ll need to pay the deductible, but it doesn’t eliminate the risk entirely. Weigh the likelihood against whether you could comfortably absorb the deductible if an unexpected claim did happen.
Can my lender require a specific deductible if my car is financed?
Lenders commonly require collision and comprehensive coverage on financed or leased vehicles, and some loan agreements specify maximum deductible amounts. Check your financing contract before assuming you have full freedom to raise your deductible.
Is it worth paying a deductible on an older car with low market value?
It depends on the vehicle’s current value relative to the premium you’re paying for collision and comprehensive coverage. If the car is worth little, the potential payout in a total-loss claim may not justify the ongoing cost — compare current market value against premium cost directly rather than assuming either answer.
What is GAP insurance, and is it the same as my deductible?
No — GAP insurance is a separate product that covers the difference between a vehicle’s market value and what’s still owed on a loan if the car is totaled. Your standard deductible and GAP coverage address different financial gaps.
How can I check what claims history insurers see when pricing my policy?
Insurers commonly use claims databases such as the Comprehensive Loss Underwriting Exchange (CLUE) to review your claims history, and you’re entitled to request a free copy of your own CLUE report if you want to see what’s on file.
Should I change my deductible every time I get a renewal notice?
Not necessarily. An annual review is worthwhile, but the right deductible depends on your current savings, driving record, and vehicle — a change only makes sense if your circumstances or the actual numbers have shifted.
Final Perspective
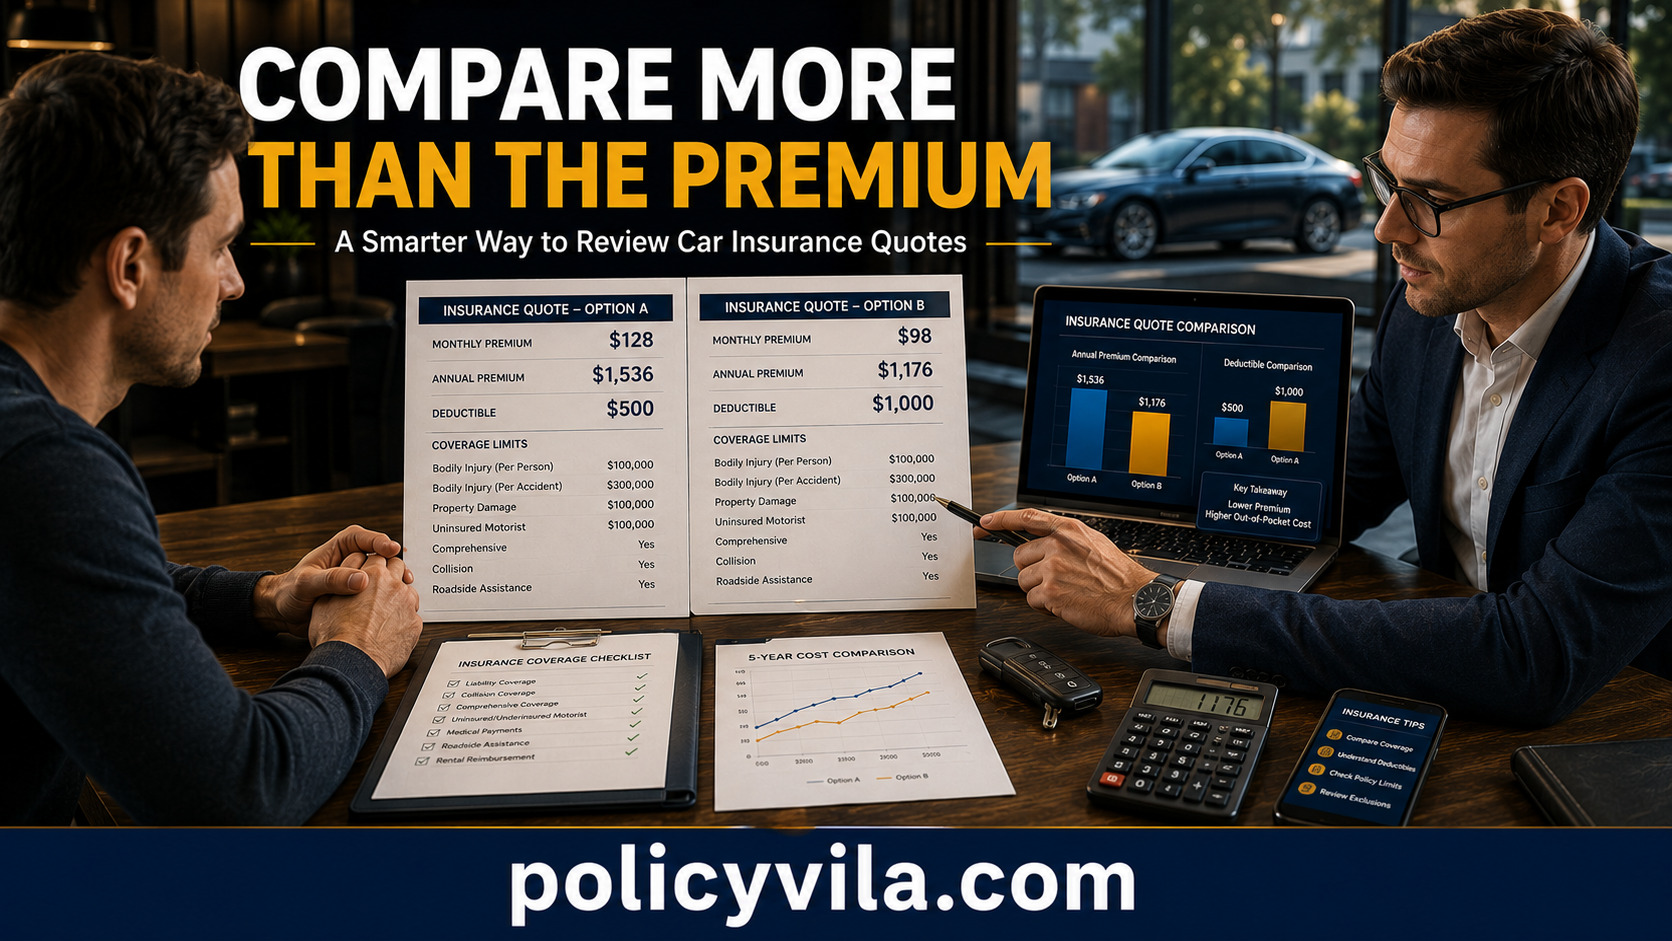
The simplest way to compare two auto insurance options is to look at the monthly premium. The smarter comparison goes further: the annual premium, the deductible attached to each specific coverage, the coverage limits, the exclusions, and — just as important — your own ability to absorb an unexpected out-of-pocket expense.
A lower premium delivers a real, predictable saving. A lower deductible reduces what you might owe if something goes wrong. Neither number tells the whole story by itself, and the cheapest monthly premium isn’t automatically the cheapest choice once the full trade-off is on the table.