
This guide explains what refinance rates are, why they move, how the refinancing process actually unfolds step by step, the different refinancing options available, how each affects your monthly payment, and how to calculate whether a specific offer is genuinely worth pursuing. It also covers common mistakes, practical comparison tips, and detailed answers to the questions homeowners ask most often before signing a new loan.
Quick Answer
A mortgage refinance replaces your existing home loan with a new one, ideally with better terms. Refinancing tends to make financial sense when the new interest rate is meaningfully lower than your current rate, you plan to stay in the home long enough to recover the closing costs, and the new loan structure supports your actual goal — whether that’s a lower payment, a shorter payoff timeline, more predictable payments, or cash from your equity. A lower rate alone doesn’t guarantee savings; the closing costs, loan term, and how long you keep the loan matter just as much.
Table of Contents
- What Are Mortgage Refinance Rates?
- Why Refinance Rates Change
- How the Refinancing Process Works
- Documents Lenders Typically Request
- Types of Mortgage Refinancing
- Fixed-Rate vs. Adjustable-Rate Refinancing
- How Refinance Rates Affect Your Monthly Payment
- Understanding Refinance Closing Costs
- Calculating Your Break-Even Point
- When Refinancing Is Likely to Help
- When Refinancing May Not Be Worth It
- How Refinancing Affects Your Credit and Equity
- Common Refinancing Mistakes
- Practical Tips for Comparing Offers
- Frequently Asked Questions
- Final Thoughts
What Are Mortgage Refinance Rates?
Mortgage refinance rates are the interest rates lenders offer when you replace an existing mortgage with a new loan. Instead of financing a home purchase, a refinance pays off your current mortgage and establishes new terms based on your present financial profile — not the circumstances that applied when you first bought the home.
Lenders typically evaluate several factors before setting your refinance rate:
- Credit score
- Income stability and employment history
- Current mortgage balance and remaining term
- Home equity and loan-to-value (LTV) ratio
- Debt-to-income ratio
- Property type and occupancy status
- Current market conditions
Because these factors can shift over time, the rate you’re offered today could be higher, lower, or roughly the same as your original mortgage rate. A borrower who has paid down debt, improved their credit score, or watched their home appreciate in value since their original purchase is often in a stronger position to receive competitive refinance pricing.
Purchase Rates vs. Refinance Rates
| Feature | Purchase Mortgage | Mortgage Refinance |
|---|---|---|
| Purpose | Buy a home | Replace an existing mortgage |
| Existing loan | None | Pays off current loan |
| Rate basis | Purchase market conditions | Current refinance market and borrower profile |
| Down payment concept | Cash contributed at purchase | Existing equity plays a similar role |
The gap between purchase and refinance rates is usually modest, but it can vary by lender and loan program, so it’s worth asking directly rather than assuming the two are identical.
Why the Word “Rate” Can Be Misleading
When lenders advertise a refinance rate, that number typically reflects the interest rate under ideal conditions — a strong credit score, a low loan-to-value ratio, and a standard loan amount. Your actual quoted rate may differ once your specific financial profile is reviewed. This is why comparing multiple, personalized quotes matters more than comparing advertised rates alone.
Why Refinance Rates Change
Refinance rates can shift daily, sometimes more than once in a single day, because they respond to a mix of economic and market forces rather than any single factor.
Inflation
When inflation rises, lenders often seek higher interest rates to offset the declining purchasing power of future loan repayments. When inflation eases, borrowing costs can become more favorable, though many other variables factor in as well.
Treasury Yields
Refinance rates tend to track the direction of U.S. Treasury yields, particularly the 10-year note, even though the two don’t move in perfect lockstep. Rising yields often coincide with higher refinance rates, and falling yields with lower ones. Investors buy and sell mortgage-backed securities based partly on how they compare to Treasury returns, which links the two markets closely.
Federal Reserve Policy
The Federal Reserve does not set mortgage rates directly. It influences short-term interest rates through monetary policy, which can indirectly affect broader financial markets, Treasury yields, and eventually mortgage pricing. A Fed rate change doesn’t automatically translate into an equivalent move in refinance rates, which is a common point of confusion.
Economic Conditions and Credit Markets
Strong economic growth can push inflation and rates higher, while slower growth sometimes leads investors toward safer assets and more competitive mortgage pricing. Lender funding costs in the broader credit markets also get passed on to borrowers to some degree. Banking-sector stress, investor confidence, and global financial events can all ripple into refinance pricing even when nothing has changed locally in the housing market.
Housing Market Activity
When refinancing demand surges — often after a period of rate declines — lenders may adjust pricing based on processing capacity and competitive positioning. This is one reason rates can move even without a corresponding shift in the broader economy.
Your Personal Financial Profile
Market-wide trends set the general range, but your individual rate depends on your credit score, income stability, debt-to-income ratio, home equity, and loan amount. Two people refinancing on the same day can receive different rates because their financial profiles differ.
Because so many variables are involved, no one can reliably predict where rates will move next. Rather than trying to time the market, it’s usually more productive to evaluate whether refinancing makes sense for your specific situation right now, using your current numbers rather than a forecast of where rates might go.
Summary Table: What Moves Refinance Rates
| Factor | Typical Effect |
|---|---|
| Rising inflation | Tends to push rates higher |
| Rising Treasury yields | Often coincides with higher rates |
| Fed policy tightening | Indirect upward pressure |
| Slower economic growth | Can support more competitive pricing |
| Improved personal credit profile | May qualify you for a lower individual rate |
| Higher home equity | May improve loan options and pricing |
How the Refinancing Process Works
Refinancing follows a process similar to your original mortgage application, with the key difference that you already own the property and have an existing loan history the new lender can review.
- Review your current mortgage. Note your balance, rate, remaining term, monthly payment, and whether your loan has a prepayment penalty.
- Define your goal. A lower payment, a shorter term, a switch from an adjustable to a fixed rate, or access to home equity each point toward a different refinance type.
- Compare multiple lenders. Rates, fees, and terms vary between institutions, so a single quote rarely tells the full story.
- Submit your application with income documentation, tax records, bank statements, and your current mortgage statement.
- Complete a home appraisal if your lender requires one, to confirm current market value and available equity.
- Go through underwriting, where the lender verifies your credit, income, and property details against its lending guidelines.
- Review your Loan Estimate carefully, comparing the new rate, APR, closing costs, and monthly payment against your existing mortgage.
- Close the loan. The new mortgage pays off the old one, and you begin payments under the new terms.
What Happens Immediately After Closing
Once your refinance closes, your previous mortgage is paid off and officially closed. You’ll typically receive a payoff confirmation from your old lender and a welcome packet from your new servicer outlining your new payment due date, account number, and how to set up autopay if you choose. It’s worth reviewing your first one or two statements closely to confirm the interest rate, loan balance, and escrow amounts match what you agreed to at closing.
Typical Timeline
| Stage | Typical Timeframe |
|---|---|
| Application | 1–2 days |
| Document review | Several days |
| Appraisal (if required) | Varies by lender and location |
| Underwriting | Several days to a few weeks |
| Closing | Scheduled after approval |
[Relevant image: homeowner reviewing refinance loan estimate documents]
Rate Locks
Because refinance rates can move daily, many lenders offer the option to “lock” your rate for a set period once you decide to proceed, protecting you from increases while your loan moves through underwriting. Lock periods vary and sometimes carry an extension fee if closing is delayed beyond the original window. Ask your lender directly how their lock policy works and what happens if your closing date slips.
Documents Lenders Typically Request
Having paperwork ready in advance can shorten your refinance timeline considerably. Common documents include:
- Government-issued identification
- Recent pay stubs, typically covering the last 30 days
- W-2 forms or tax returns from the past one to two years
- Bank and investment account statements
- Your current mortgage statement
- Proof of homeowners insurance
- Documentation of any additional income, such as bonuses or rental income
Self-employed borrowers are often asked for additional documentation, such as profit-and-loss statements or two years of business tax returns, since income verification tends to be more involved without W-2 pay stubs.
Types of Mortgage Refinancing
Rate-and-Term Refinance
This is the most common refinance type. It replaces your existing mortgage with a new interest rate, a new term, or both — without letting you borrow additional cash against your equity. Homeowners typically consider this option when rates have improved, their credit profile has strengthened, or they want to shorten their loan term or switch from an adjustable to a fixed rate.
Potential benefits: a lower interest rate, a reduced monthly payment, or a shorter payoff timeline.
Things to weigh: closing costs still apply, and extending your term to lower the payment can increase total interest paid over the life of the loan.
Cash-Out Refinance
A cash-out refinance replaces your mortgage with a larger loan and pays you the difference in cash, based on your available equity. Homeowners use this for home improvements, debt consolidation, education expenses, or other major planned costs.
Potential benefits: access to equity without selling the home, and a single monthly payment instead of juggling multiple financing sources.
Important considerations: your total mortgage debt increases, your remaining equity cushion shrinks, and your monthly payment may rise. Because it increases your overall debt load, a cash-out refinance is worth treating as part of a broader financial plan rather than a quick source of spending money.
Cash-In Refinance
The opposite of cash-out: you bring a lump sum to closing to pay down the balance, which lowers your loan-to-value ratio.
Potential advantages: a smaller loan balance, potentially lower interest costs, and improved qualification odds — including possibly eliminating mortgage insurance if your new LTV clears the required threshold.
This approach requires significant upfront cash, so it tends to suit homeowners who have savings available and specifically want to strengthen their equity position rather than access it.
Streamline Refinance
Some loan programs offer streamlined refinancing that reduces paperwork or waives a full appraisal for eligible borrowers. Eligibility rules vary significantly by program and lender, so confirm the specifics before assuming you qualify. The purpose of a streamline option is to make the process more efficient for qualifying borrowers, not to change the fundamental economics of refinancing.
| Refinance Type | Primary Purpose | May Suit |
|---|---|---|
| Rate-and-Term | Change rate or term | Homeowners seeking a better rate or structure |
| Cash-Out | Access home equity | Borrowers with a specific, planned expense |
| Cash-In | Reduce loan balance | Homeowners with savings who want lower LTV |
| Streamline | Simplify the process | Borrowers on qualifying loan programs |
Questions to Ask Before Choosing a Refinance Type
- What specific financial goal am I trying to achieve?
- Am I trying to lower my monthly payment, reduce total interest, or free up cash?
- How long do I realistically expect to stay in this home?
- Will the closing costs be worth it given that timeline?
Fixed-Rate vs. Adjustable-Rate Refinancing
A fixed-rate refinance keeps the same interest rate for the entire loan term, making your principal-and-interest payment predictable for as long as you hold the loan. An adjustable-rate refinance (ARM) starts with a fixed introductory rate for a set period, after which the rate adjusts periodically based on market conditions.
| Feature | Fixed-Rate Refinance | Adjustable-Rate Refinance |
|---|---|---|
| Interest rate | Stays the same | Changes after the introductory period |
| Payment predictability | High | Lower after adjustment begins |
| Protection from rising rates | Yes | No |
| Initial rate | Often somewhat higher | Often somewhat lower |
| Best suited for | Long-term homeownership | Shorter expected time in the home |
A Fixed-Rate Refinance May Fit If You:
- Plan to stay in your home for many years
- Prefer predictable monthly payments
- Want protection against future rate increases
- Build your budget around consistent expenses
An Adjustable-Rate Refinance May Be Worth Exploring If You:
- Expect to sell or refinance again before the introductory period ends
- Understand and can absorb the risk of a future payment increase
- Want a lower initial payment and have a specific short-term plan
Neither option is universally “better.” A fixed-rate refinance trades a possibly higher starting rate for long-term certainty. An ARM trades that certainty for a lower introductory cost. Choosing an ARM should be based on realistic plans for how long you’ll keep the loan, not just the appeal of a lower starting payment.
How Refinance Rates Affect Your Monthly Payment
Three factors primarily drive your new monthly payment:
- Interest rate — a lower rate generally reduces your payment and total interest paid over time.
- Loan amount — a smaller remaining balance lowers payments; a cash-out refinance raises the balance and, often, the payment.
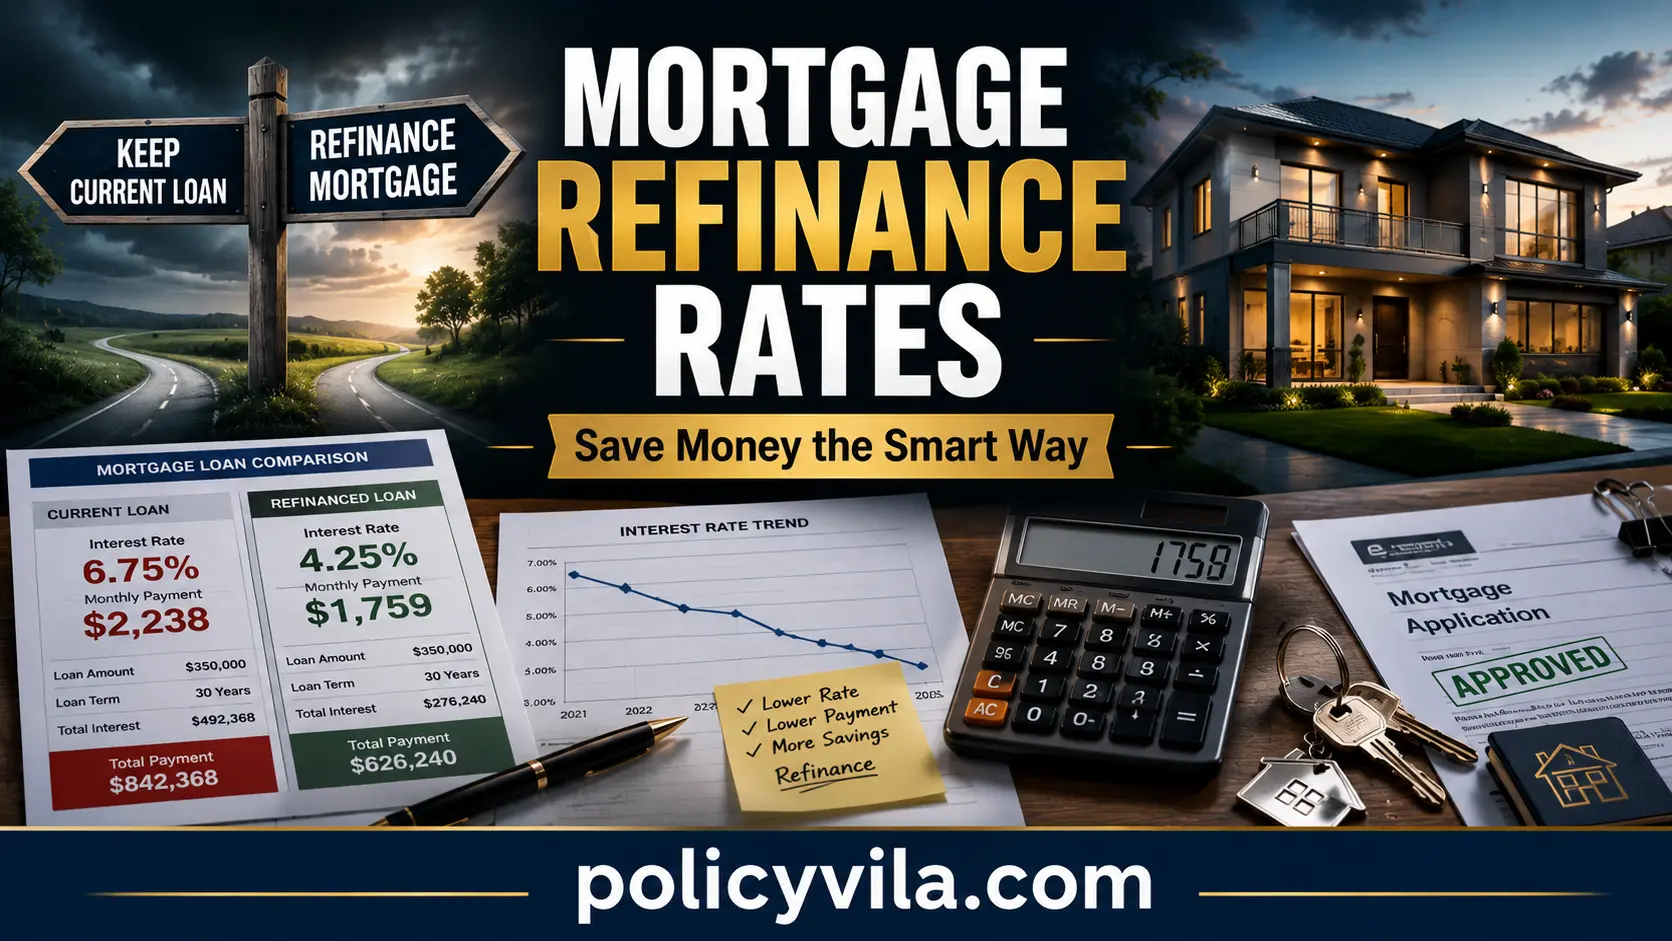
- Loan term — a longer term (e.g., 30 years) usually lowers the monthly payment but increases total interest paid; a shorter term (e.g., 15 years) raises the payment but reduces lifetime interest cost.
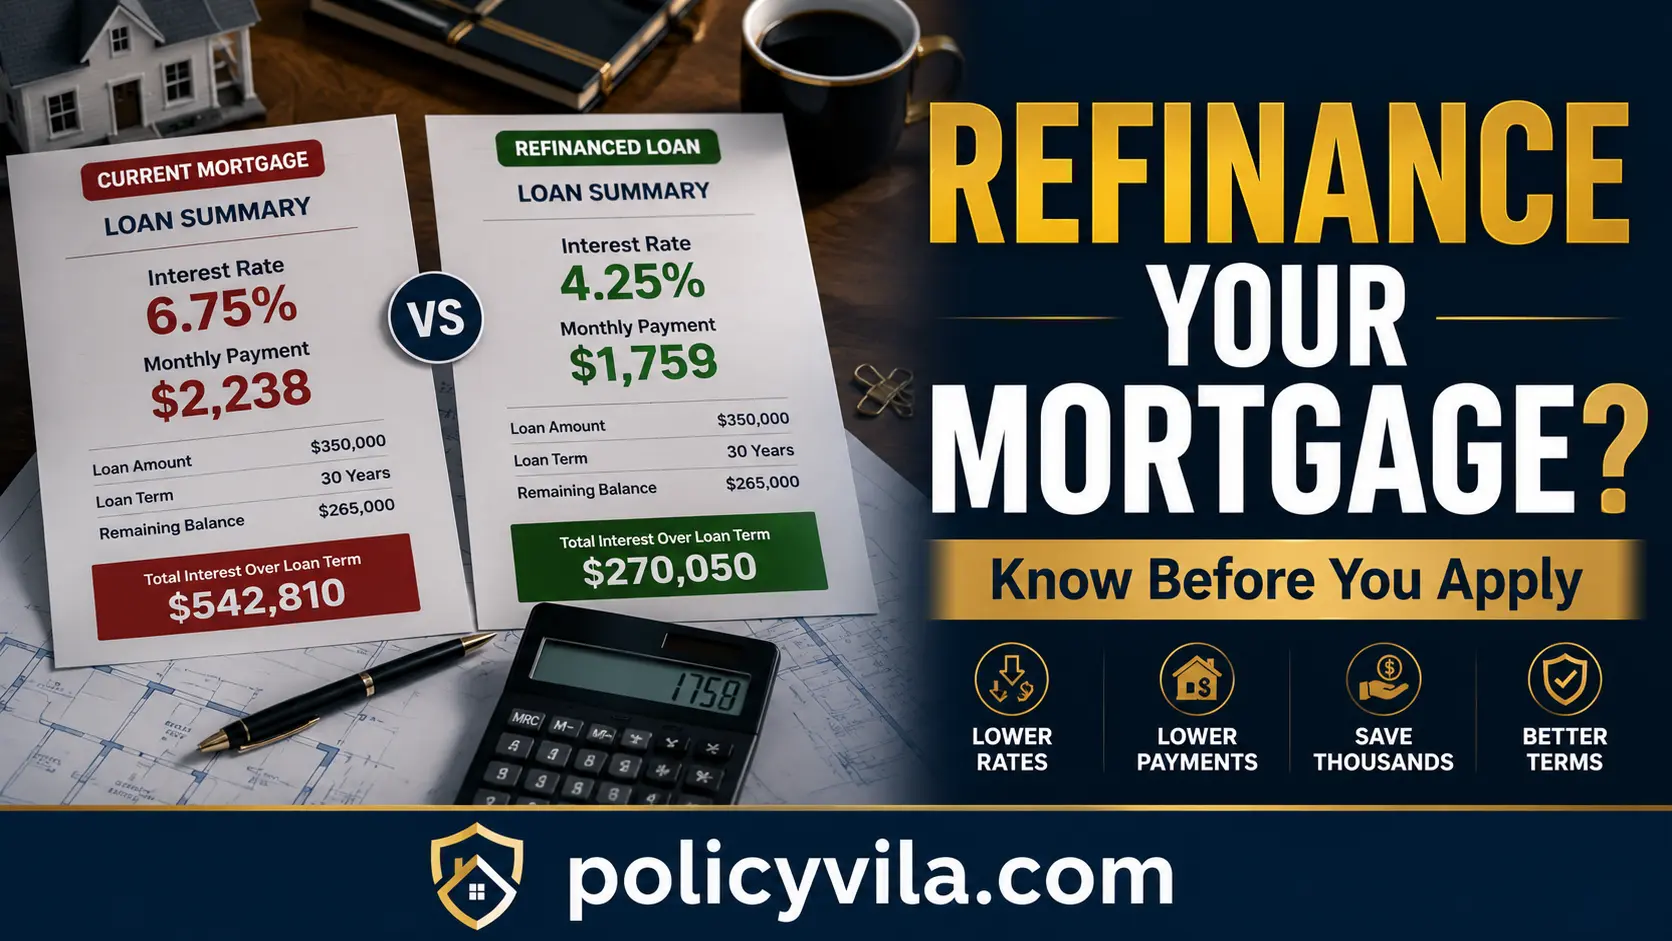
| Loan Option | Monthly Payment | Total Interest Over Time |
|---|---|---|
| 15-year refinance | Higher | Usually lower |
| 30-year refinance | Lower | Usually higher |
A lower monthly payment doesn’t automatically mean a cheaper loan. Extending the term, or rolling closing costs into the new balance, can shrink your monthly bill while increasing what you pay in total. Always compare the full loan cost, not just the payment amount.
What Else Shows Up in Your Payment
Beyond principal and interest, your monthly mortgage payment may include property taxes, homeowners insurance, mortgage insurance if applicable, and HOA fees where relevant — often collected through an escrow account. A refinance can change these components too, particularly if your new loan-to-value ratio affects whether mortgage insurance is required.
How Refinancing Can Change Household Cash Flow
A lower monthly payment can free up room in your budget for savings, investing, or paying down other debt. A shorter term with a higher payment, by contrast, can help you build equity faster and become mortgage-free sooner, even though it tightens monthly cash flow in the near term. Which approach fits better depends on your broader financial priorities, not just the size of the payment itself.
Understanding Refinance Closing Costs
Refinancing isn’t free. Typical closing costs include lender origination fees, appraisal fees, title search and insurance fees, recording fees, and sometimes prepaid items like property taxes or homeowners insurance placed into a new escrow account.
| Common Cost | What It Covers |
|---|---|
| Origination fee | Lender’s cost for processing and underwriting the loan |
| Appraisal fee | Professional estimate of current home value |
| Title search and insurance | Confirms clear ownership and protects against title defects |
| Recording fee | Local government charge to record the new mortgage |
| Prepaid escrow items | Initial funding for taxes and insurance held by the new lender |
Some lenders offer “no-closing-cost” refinances, which typically fold the costs into a slightly higher interest rate or a larger loan balance rather than eliminating them. This can make sense if you don’t plan to keep the loan long enough to benefit from paying costs upfront, but it’s worth comparing the total cost either way rather than assuming “no closing costs” means a free refinance.
Calculating Your Break-Even Point
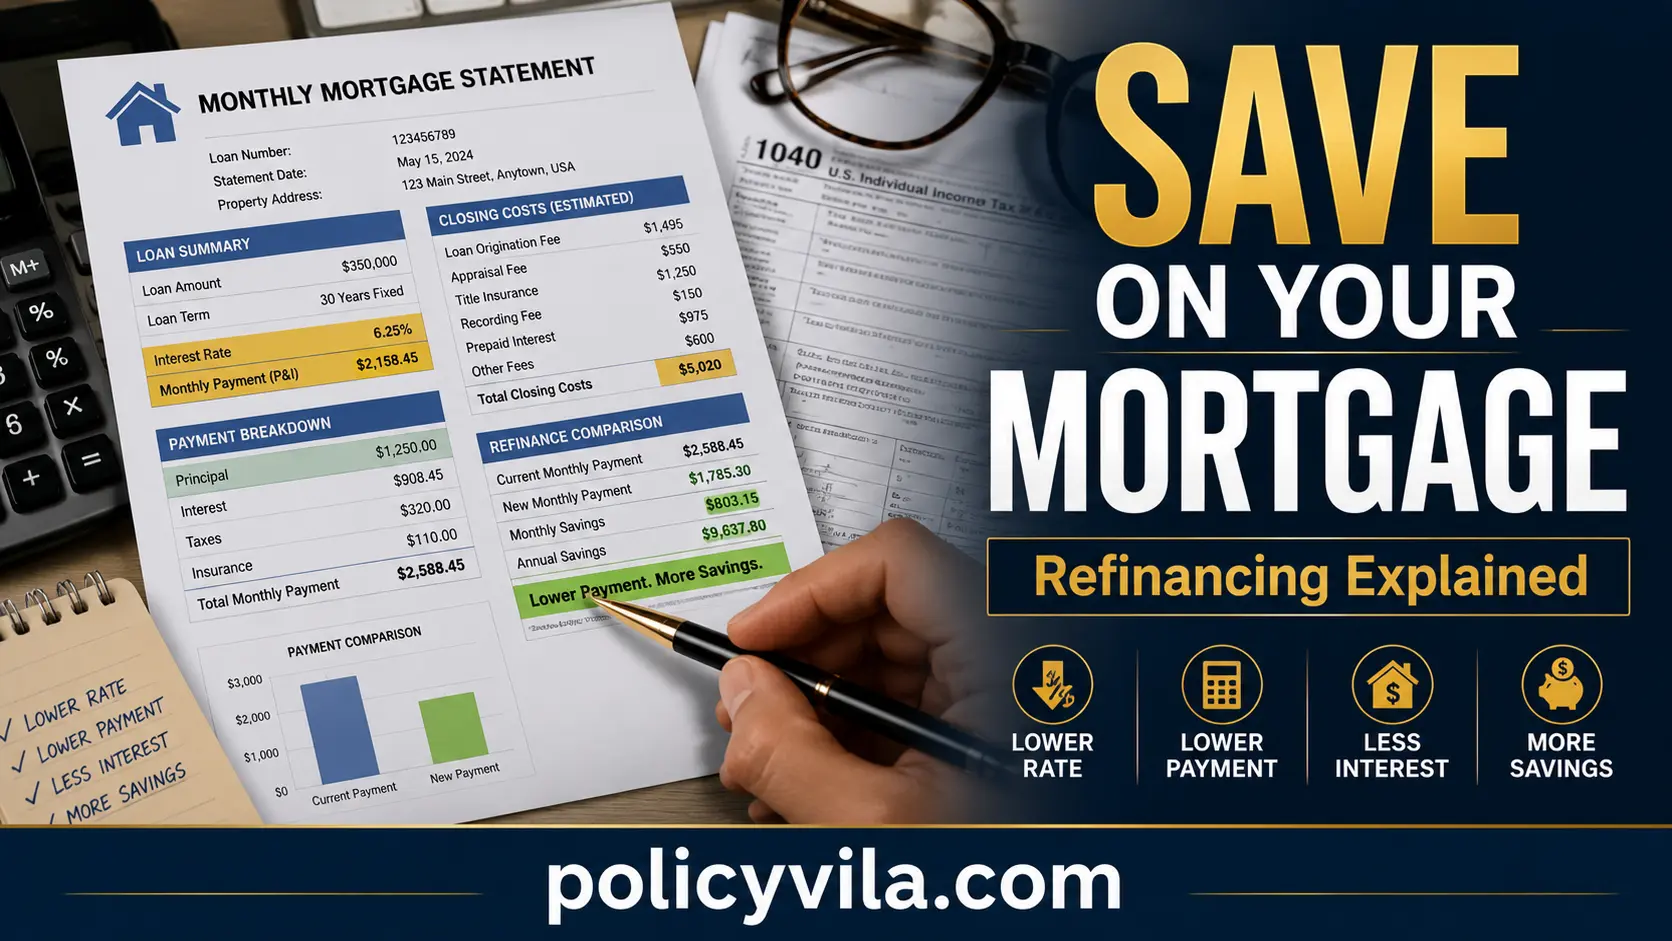
The break-even point is the moment your monthly savings equal your total closing costs. Beyond that point, refinancing starts to actually save you money.
Simple Break-Even Formula
Break-even period (months) = Total closing costs ÷ Monthly payment savings
For example, if closing costs total $6,000 and your new loan saves you $150 per month, the break-even point is 40 months — a little over three years. If you plan to stay in the home well beyond that point, the refinance is more likely to pay off. If you expect to move or refinance again sooner, the savings may never materialize.
This calculation is a simplified estimate. It doesn’t account for changes in loan term, taxes, or how much of each payment goes toward principal versus interest, so treat it as a starting point rather than a complete financial analysis. For a more precise picture, compare total amortized interest across the full remaining term of your current loan versus the new one.
A Worked Example
Suppose a homeowner has $300,000 remaining on their mortgage at a higher rate than what’s currently available. After comparing offers, they find a refinance option with a lower rate, resulting in a payment that’s $180 lower per month, with total closing costs of $5,400. Dividing $5,400 by $180 gives a break-even point of 30 months, or two and a half years. If this homeowner expects to stay in the home for at least that long, the numbers suggest the refinance is likely worthwhile. If they expect to sell within a year or two, the closing costs may outweigh the savings.
When Refinancing Is Likely to Help
- Your rate is meaningfully lower than your current one, and the savings outweigh closing costs within a reasonable timeframe.
- You want a more predictable payment and plan to move from an adjustable-rate mortgage to a fixed rate.
- Your credit profile has improved since your original mortgage, potentially qualifying you for better terms.
- You want to pay off the loan faster by shortening the term, even if the monthly payment rises.
- You plan to stay in the home long enough to clear the break-even point comfortably.
- Your home equity has grown enough to eliminate mortgage insurance through a rate-and-term or cash-in refinance.
When Refinancing May Not Be Worth It
- You plan to move within a few years, before the break-even point arrives.
- The rate difference is small, meaning closing costs may take a long time to recover.
- Your credit or financial situation has weakened since your original mortgage, which could result in a less favorable offer than expected.
- You’re close to paying off your current mortgage, since restarting the amortization schedule can increase total interest paid even at a lower rate.
- A prepayment penalty on your current loan would offset most or all of the potential savings.
In these situations, it can still be worth requesting quotes to see the actual numbers rather than assuming refinancing is off the table entirely — but go in expecting that the math may not favor a new loan.
How Refinancing Affects Your Credit and Equity
Applying for a refinance typically triggers a hard credit inquiry, which can cause a small, temporary dip in your credit score. Opening a new loan account and closing the old one can also affect the average age of your credit accounts. These effects are generally modest and tend to fade with consistent on-time payments over time.
Your home equity position can shift depending on the refinance type. A rate-and-term refinance generally leaves your equity roughly the same, aside from any costs rolled into the loan. A cash-out refinance reduces your equity because you’re borrowing more against the home. A cash-in refinance increases your equity because you’re contributing extra funds at closing.
Common Refinancing Mistakes
- Accepting the first offer without comparing lenders. Rates, fees, and terms can vary meaningfully between institutions.
- Focusing only on the interest rate and ignoring the APR, which reflects fees and gives a more complete cost picture.
- Choosing a lower payment without checking the total cost. Extending your term or rolling in costs can raise what you pay over time.
- Refinancing without calculating the break-even point, especially if a move is likely within a few years.
- Overlooking how a cash-out refinance affects your equity position and monthly payment.
- Not asking about rate lock terms, which can leave you exposed to rate increases during a delayed closing.
- Ignoring prepayment penalties on the existing loan, which can quietly erode expected savings.
Practical Tips for Comparing Offers
- Request Loan Estimates from at least three lenders on the same day so rate comparisons are apples to apples.
- Compare APR, not just the advertised interest rate, since APR reflects most lender fees.
- Ask each lender for an itemized closing cost breakdown before committing.
- Calculate your personal break-even point using your actual closing costs and expected monthly savings.
- Confirm whether your new loan-to-value ratio changes your mortgage insurance requirement.
- Ask directly whether a “no-closing-cost” option is available and how it affects your rate.
- Clarify how long your quoted rate is locked and what happens if closing is delayed.
Frequently Asked Questions
Is there a minimum time I need to wait after buying a home before refinancing?
Some loan programs impose a seasoning period before you can refinance, particularly for cash-out refinances. Requirements vary by lender and loan type, so check with your servicer for the specific rule that applies to your mortgage.
Can I refinance more than once?
Yes, there’s generally no limit on how many times you can refinance, provided you meet each lender’s qualification requirements. Each refinance involves its own closing costs, so repeated refinancing only makes sense if the savings justify the expense each time.
Will refinancing restart my loan term from scratch?
It can, depending on the term you choose. If you refinance a loan with 22 years remaining into a new 30-year loan, you effectively extend your payoff timeline unless you choose a shorter term or make extra payments.
Does refinancing affect my credit score?
A refinance application typically triggers a hard credit inquiry, which can cause a small, temporary dip in your score. Consistent on-time payments after refinancing tend to support your credit over the longer term.
Can closing costs be rolled into the new loan?
Many lenders allow this. It reduces upfront cash needed at closing but increases your loan balance and the total interest you’ll pay, so weigh that trade-off carefully.
What’s the difference between refinancing and a home equity loan?
A refinance replaces your existing mortgage entirely with a new loan. A home equity loan or line of credit is a separate loan on top of your existing mortgage. Which makes more sense depends on your current rate, how much equity you want to access, and whether you want one loan or two.
Do I need a new appraisal every time I refinance?
Not always. Some streamline refinance programs waive the appraisal requirement for eligible borrowers, while conventional rate-and-term and cash-out refinances often require one to confirm current home value.
How much can rates change between application and closing?
Quoted rates typically have a limited validity window, and market conditions can shift before closing. Ask your lender whether you can lock your rate, and for how long, once you decide to move forward.
Is a lower payment always a sign of a good refinance?
Not necessarily. A lower payment achieved by extending your loan term or financing closing costs can increase your total interest paid, even though the monthly number looks better. Compare total loan cost, not just the payment.
What documents should I have ready before applying?
Typically: government-issued ID, recent pay stubs, W-2s or tax documents, bank statements, your current mortgage statement, and proof of homeowners insurance. Having these ready can speed up underwriting.
Can I switch lenders when I refinance, or do I need to stay with my current one?
You’re free to refinance with any lender willing to offer you a loan, not just your current mortgage servicer. Comparing outside lenders alongside your existing one is one of the most effective ways to find competitive terms.
What happens to my escrow account when I refinance?
Your existing escrow balance is typically refunded to you after your old loan is paid off, while your new lender sets up a fresh escrow account funded through your new monthly payments and any required upfront deposit at closing.
Does a cash-out refinance count as taxable income?
Cash-out refinance proceeds are generally treated as loan proceeds rather than income, but tax treatment can depend on your specific circumstances. Consult a qualified tax professional for guidance relevant to your situation.
Can I remove a co-borrower through refinancing?
Yes, refinancing is one of the more common ways to remove a co-borrower from a mortgage, since the new loan is underwritten based on whoever remains on the application. This often comes up during divorce or after a change in ownership arrangement.
Is refinancing worth it if rates have dropped by less than half a percentage point?
It depends entirely on your loan balance, remaining term, and closing costs. A small rate reduction can still be worthwhile on a large remaining balance with low closing costs, while the same rate drop might not clear the break-even point on a smaller loan. Running the actual numbers is the only reliable way to know.
Final Thoughts
Mortgage refinance rates are only one piece of the decision. Closing costs, loan term, how long you plan to stay in the home, your credit profile, and your specific financial goal — lower payment, shorter payoff, fixed-rate stability, or cash access — all determine whether a refinance actually benefits you.
Rather than chasing the lowest advertised rate, compare complete loan packages across multiple lenders, calculate your break-even point using your own numbers, and match the refinance type to what you’re actually trying to accomplish. A refinance that works well for one homeowner may not make sense for another with a different timeline or financial situation, so treat every offer as a starting point for your own calculation rather than a decision already made for you.