
Quick Answer
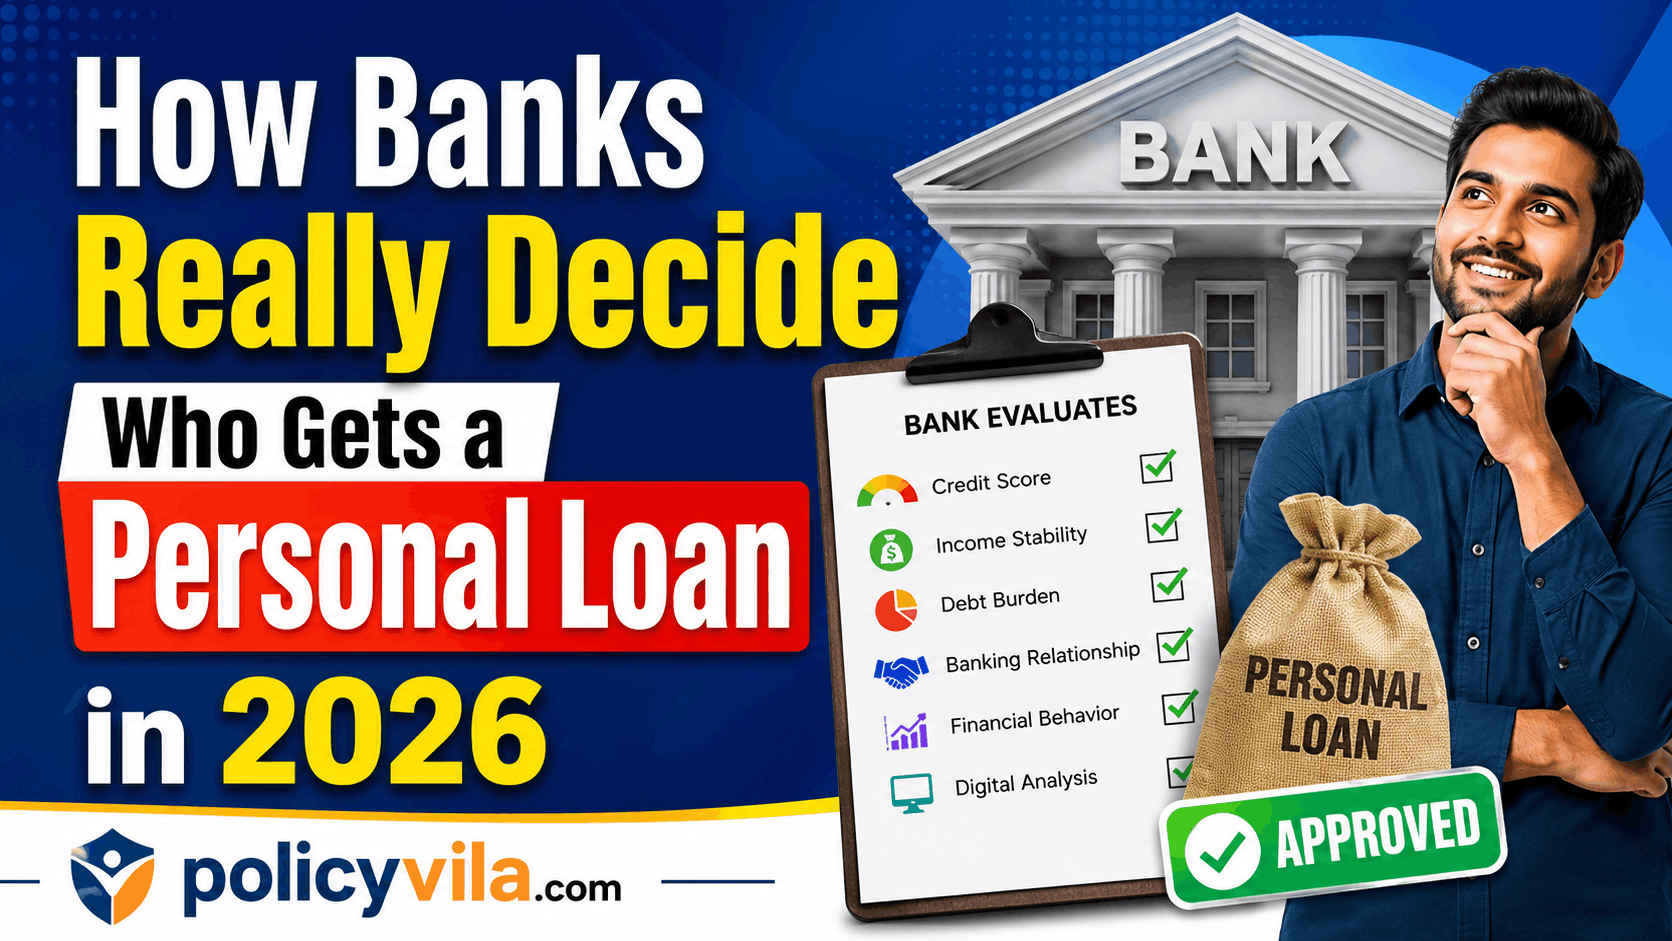
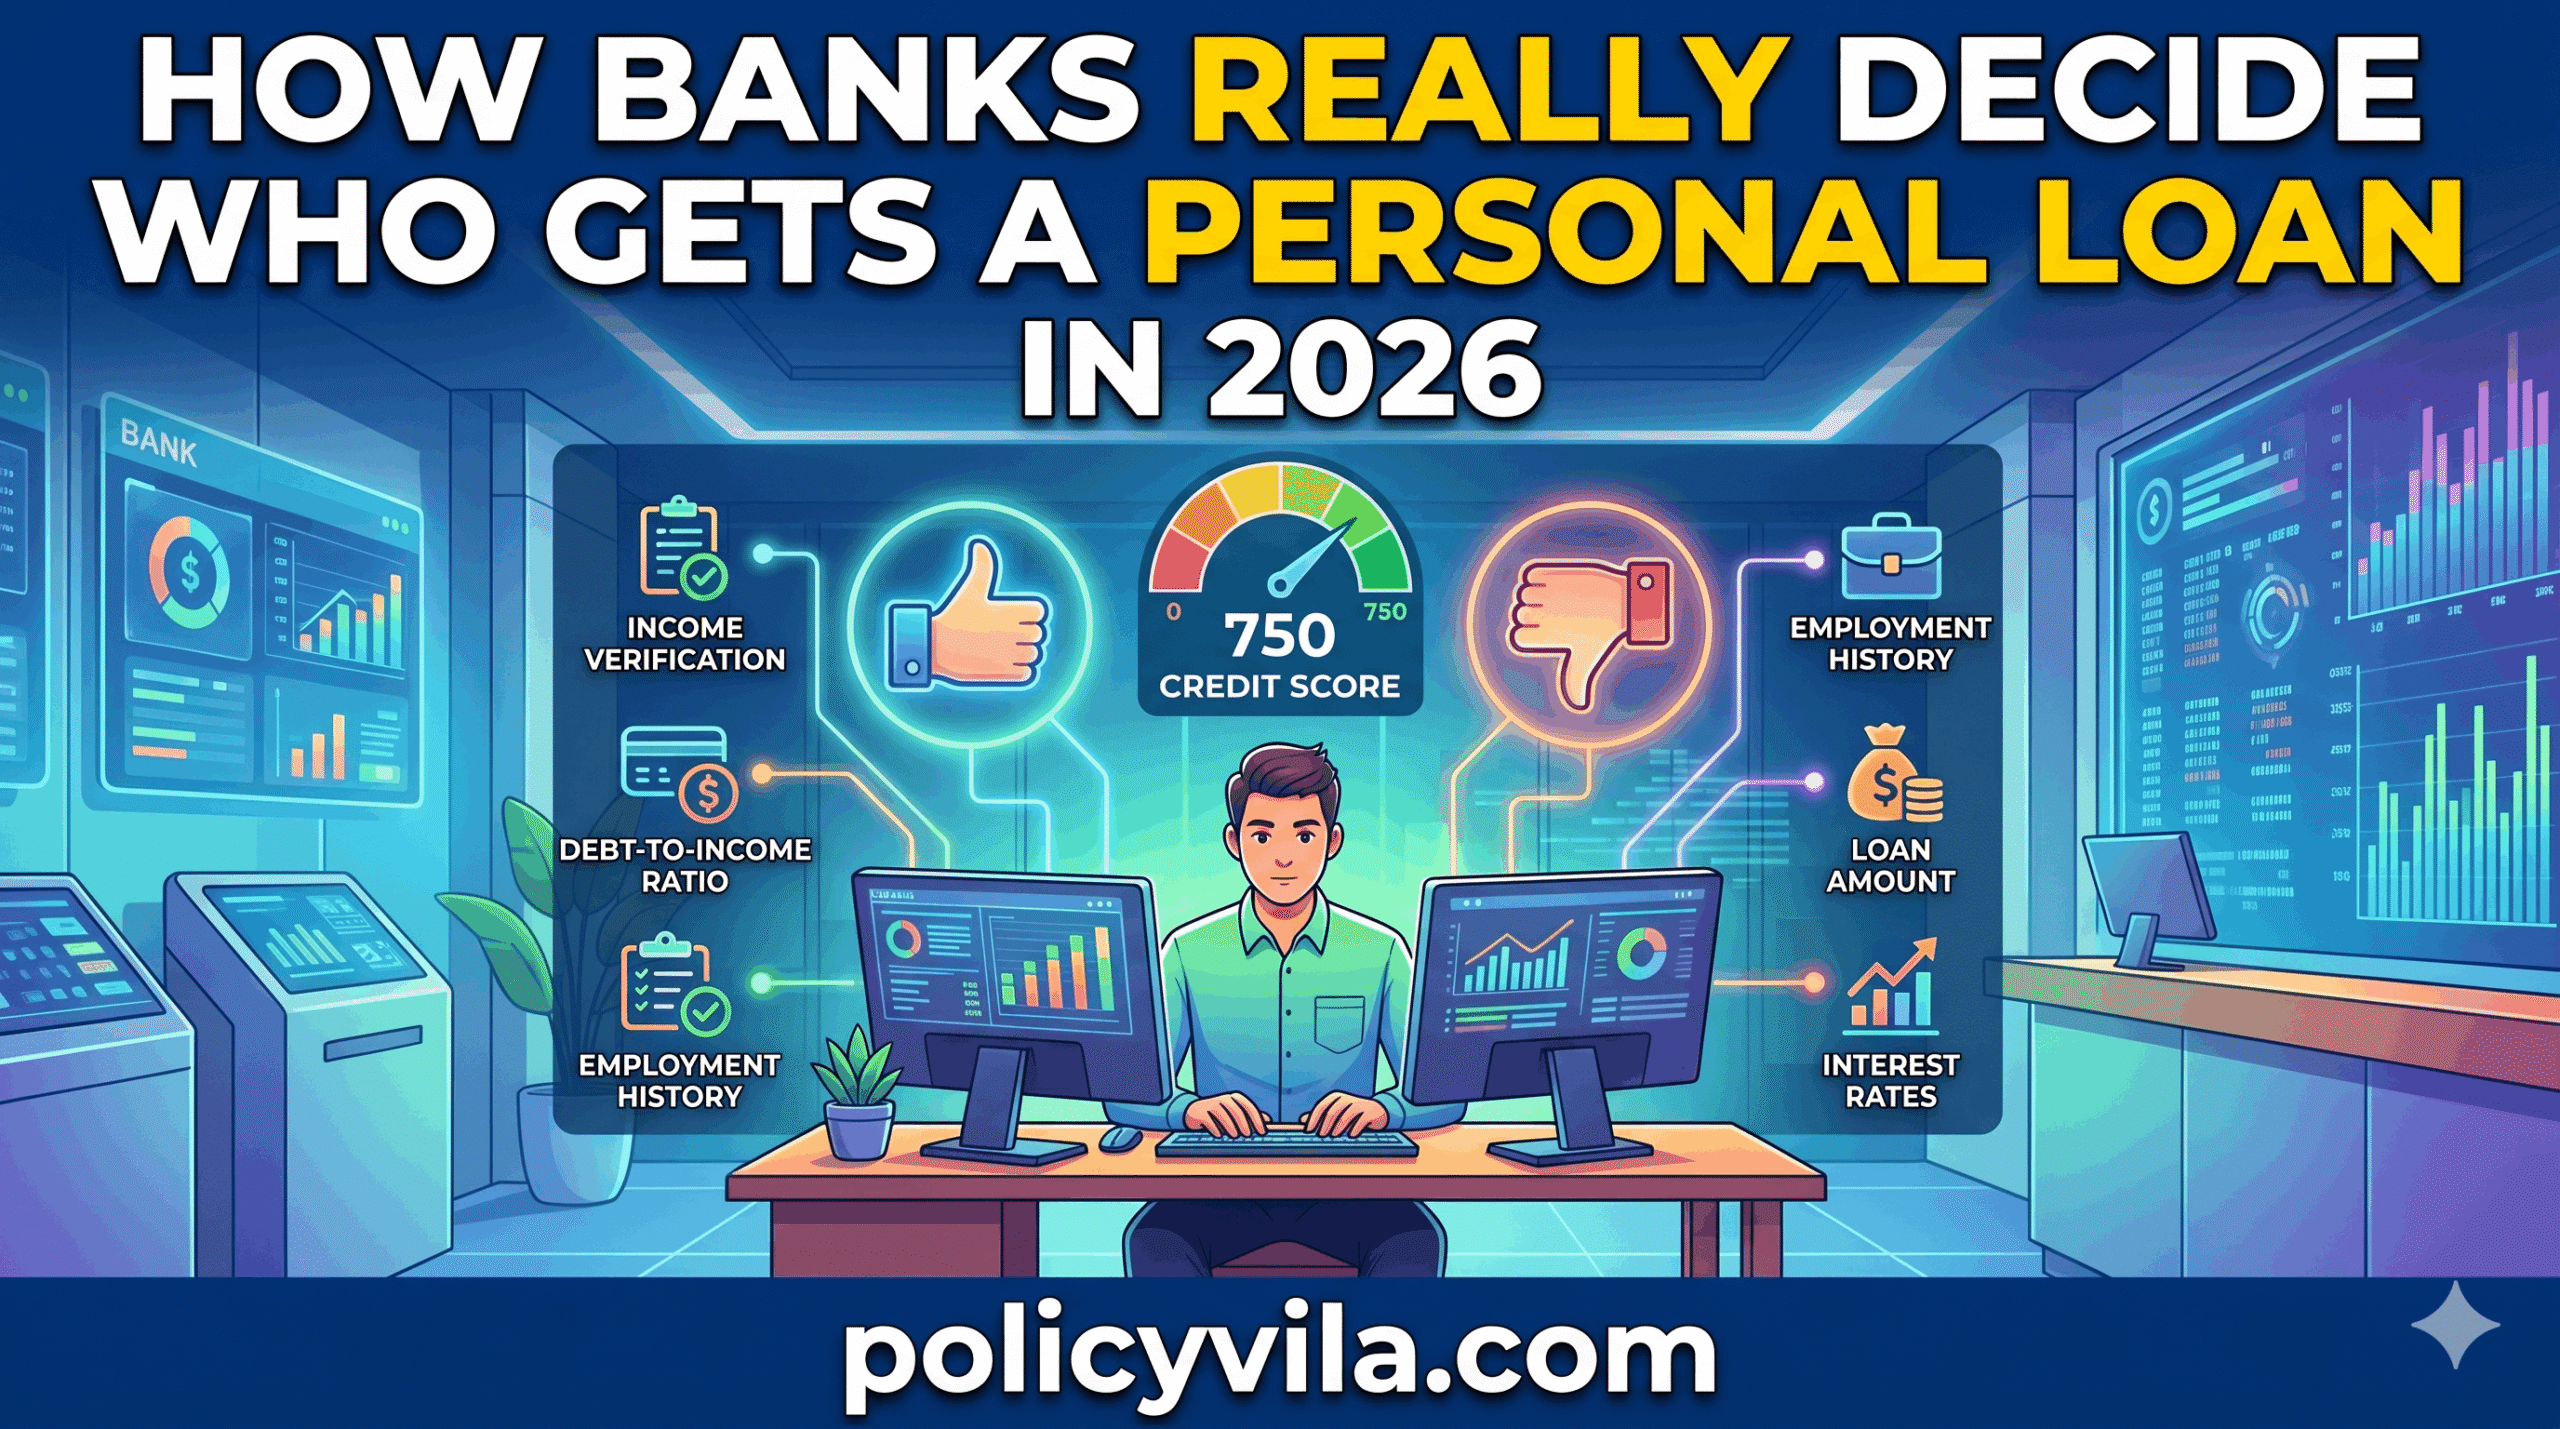
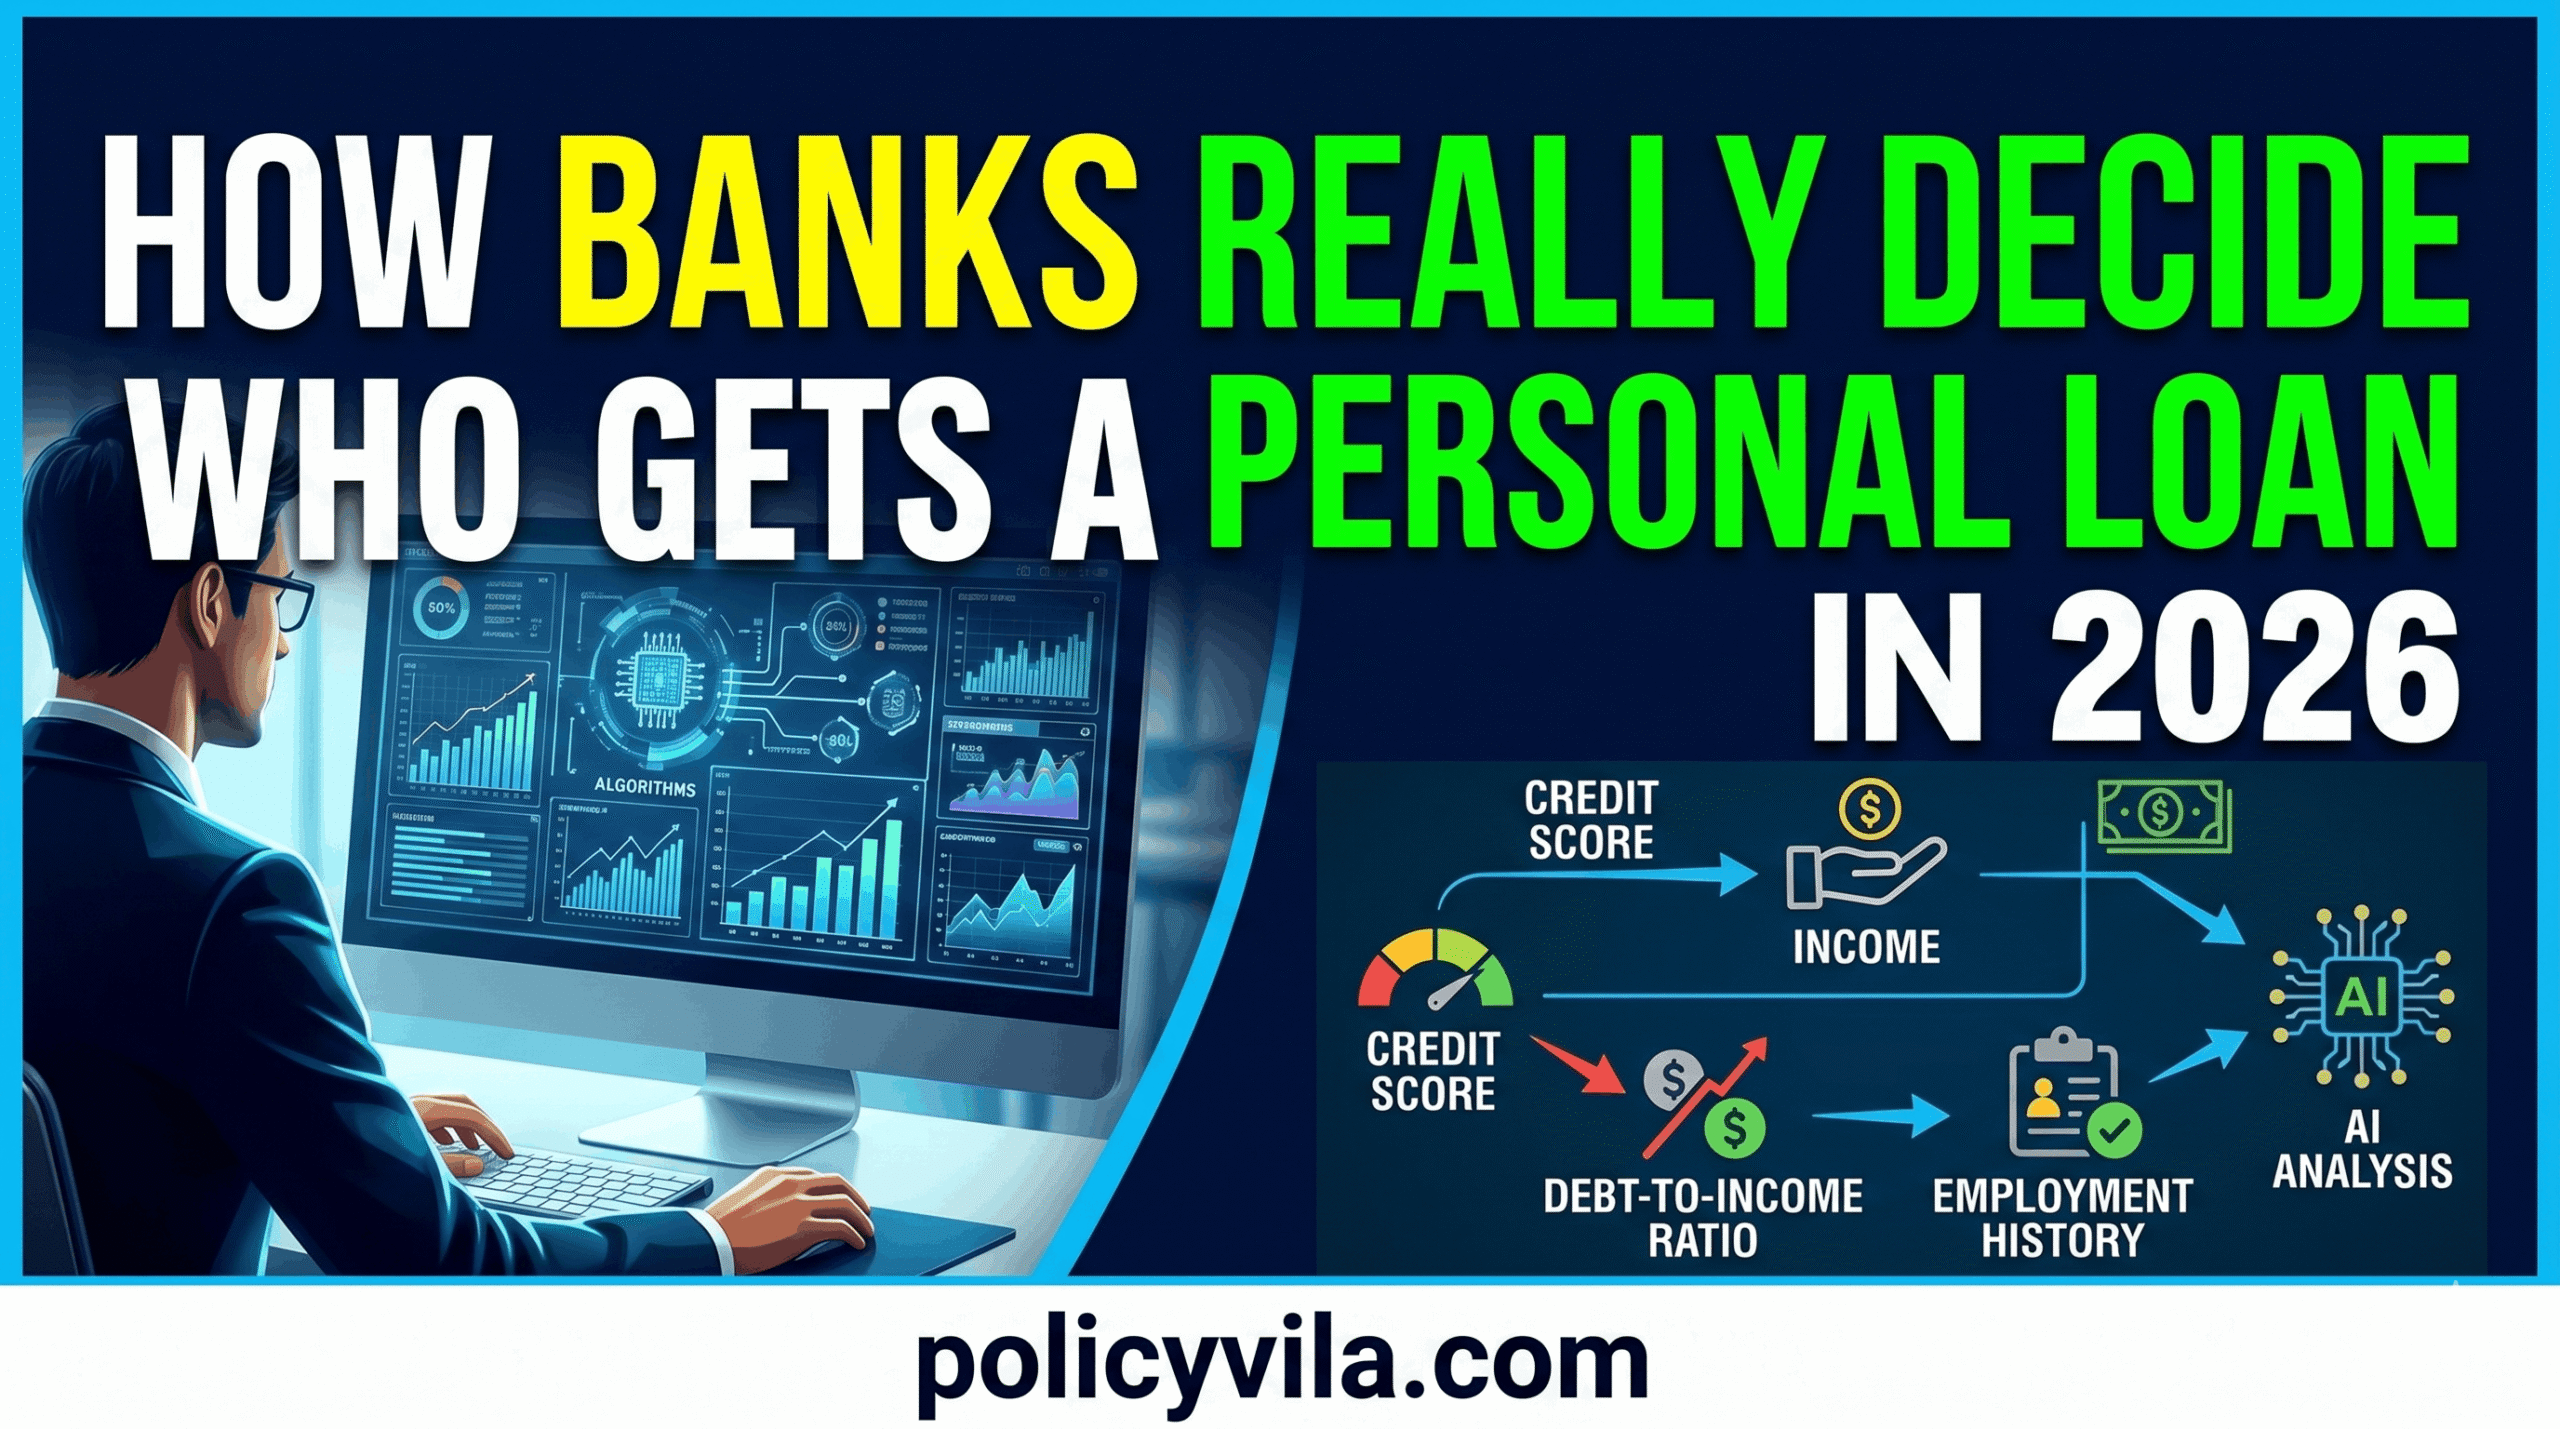
Banks evaluate personal loan applications using a combination of credit score, credit history and repayment behavior, income stability (not just income size), existing debt load measured through the debt-to-income ratio, and — for many digital lenders — transaction and cash-flow patterns pulled from your banking activity. Two applicants with identical incomes can get different outcomes if one has a longer track record of on-time payments and a lower debt load. Improving approval odds usually comes down to strengthening these factors before you apply, not finding a lender with looser criteria.
Table of Contents
- The Factors Banks Actually Weigh
- Credit Score: The Starting Point, Not the Whole Picture
- Why Credit Behavior Matters as Much as the Score
- Income Stability vs. Income Size
- Debt Burden and the Debt-to-Income Ratio
- Banking Relationship and Account History
- Digital Financial Analysis and AI Underwriting
- How to Strengthen Your Application Before You Apply
- Mistakes That Commonly Lead to Rejection
- Frequently Asked Questions
- Final Thoughts
The Factors Banks Actually Weigh
| Factor | What It Signals to the Lender |
|---|---|
| Credit score | A quick summary of past borrowing and repayment behavior |
| Credit behavior over time | Whether responsible habits are consistent or recent/inconsistent |
| Income stability | How reliably you’ll be able to make payments going forward |
| Debt-to-income ratio | How much room your budget has for an additional payment |
| Banking relationship history | Account longevity, balance patterns, and prior repayment record with that institution |
| Transaction and cash-flow data | Real spending and saving patterns, used increasingly by digital lenders |
No single factor above determines the outcome on its own — a strong showing in one area can offset a weaker one elsewhere, which is part of why applicants with similar incomes can see different results.
Credit Score: The Starting Point, Not the Whole Picture
Your credit score is typically the first thing a lender pulls, since it summarizes prior repayment history, credit utilization, account age, and recent credit inquiries into a single number. A higher score generally signals lower risk and can translate into better interest rates, while a lower score often leads to closer scrutiny, a smaller approved amount, or a higher rate to offset the perceived risk.
That said, the score is a summary, not the full story — which is why lenders also look at the behavior behind it.
Why Credit Behavior Matters as Much as the Score
Two applicants can carry similar credit scores and still receive different decisions, because the score doesn’t fully capture the pattern behind it. Lenders often look separately at:
- How consistently payments have been made on time, not just whether the current balance is in good standing
- How long accounts have been open, since a longer track record is generally viewed as more reliable than a score built up quickly
- How many new credit applications or accounts have opened recently, since a sudden burst can read as financial strain
- Credit utilization trends over time, not just a single snapshot
An applicant with a long history of steady, on-time payments is generally viewed more favorably than one with a similar score built mostly from recent improvement after past difficulties.
Income Stability vs. Income Size
A high income doesn’t automatically translate into a stronger application if that income is unpredictable. Lenders are ultimately trying to answer one question: will this person reliably be able to make the same payment every month for the life of the loan? Consistency answers that question more directly than the total dollar amount.
Factors reviewed here typically include how long you’ve been with your current employer, whether income is salaried, contract, or self-employed, and how regular deposits look over several months of statements. Self-employed applicants and those with variable income often need to provide more extensive documentation — tax returns, multiple months of bank statements — to demonstrate that income, while variable, has a stable long-term pattern.
Debt Burden and the Debt-to-Income Ratio
Lenders use the debt-to-income (DTI) ratio — total monthly debt payments divided by monthly income — to judge how much room your budget realistically has for a new payment. This includes existing loan installments, minimum credit card payments, and other recurring debt obligations, compared against verified income.
A high DTI can lead to a reduced loan amount, different terms, additional verification requests, or a decline — even for applicants with a solid credit score — because it suggests less cushion if income drops or an unexpected expense comes up. Paying down existing balances, avoiding new debt shortly before applying, and lowering credit card utilization are the most direct ways to improve this ratio before submitting an application.
Banking Relationship and Account History
Some lenders — particularly the bank where you already hold an account — factor in your broader relationship with the institution: how long the account has been open, how consistent deposits and balances have been, and whether you’ve repaid previous products (credit cards, prior loans) with them responsibly.
A long-standing account with steady activity gives a lender more data to assess risk accurately, which can translate into faster processing or pre-approved offers. This is one reason applying with an institution where you already bank sometimes moves faster than applying cold with a new lender.
Digital Financial Analysis and AI Underwriting
Many lenders, especially digital-first ones, now supplement traditional credit data with automated analysis of transaction history: how regularly income is deposited, spending consistency, savings patterns, and unusual activity that might flag risk or, in some cases, fraud. This lets some lenders process applications faster and, in certain cases, extend credit to applicants with a thin traditional credit file but strong observable cash-flow habits.
It cuts both ways, though — erratic account activity, frequent overdrafts, or large unexplained withdrawals can also raise flags during this kind of automated review, even when the credit score itself looks fine.
How to Strengthen Your Application Before You Apply
- Check your credit report for errors before applying — an incorrect late payment or account can be disputed and corrected, sometimes improving your score meaningfully.
- Pay down revolving balances to lower credit utilization, which affects both your score and how lenders read your debt burden.
- Avoid opening new credit accounts in the months before applying, since a cluster of recent inquiries can read as financial stress.
- Gather income documentation early, especially if self-employed — recent tax returns and several months of bank statements speed up verification.
- Calculate your own DTI ahead of time so you know roughly what loan amount is realistic before a lender tells you.
- Apply with a bank or credit union where you have an existing relationship if the terms are competitive, since account history can work in your favor.
Mistakes That Commonly Lead to Rejection
- Applying to multiple lenders in a short window. Each hard inquiry can affect your score, and a cluster of them can look like financial distress rather than comparison shopping.
- Overestimating what a given income can support. Requesting a loan amount that pushes your DTI too high is one of the more common reasons for a reduced offer or denial.
- Assuming a high income offsets a thin or inconsistent credit history. Lenders weigh both, and a strong income alone rarely compensates for an unreliable repayment record.
- Not reviewing your credit report beforehand. Errors go unnoticed and unresolved simply because no one checked before applying.
- Ignoring the specific lender’s stated criteria. Minimum credit score and income requirements vary by lender, and applying somewhere you clearly don’t qualify wastes a hard inquiry.
Frequently Asked Questions
Does applying to several lenders at once hurt my credit score?
It can. Multiple hard inquiries in a short period may lower your score slightly and can look like financial stress to a new lender, though some credit scoring models group loan-shopping inquiries within a short window (often 14–45 days) as a single event. Spacing out applications is generally safer if you’re not doing focused rate-shopping.
Can I get approved with a thin credit history?
It’s harder but not impossible, particularly with lenders that weigh banking and transaction data alongside traditional credit files. Steady income deposits, low overdraft activity, and a stable account history can partly offset a limited credit file with certain lenders.
What debt-to-income ratio is considered acceptable?
This varies by lender, but many prefer a DTI under roughly 35–40% including the new loan payment. Ratios above that don’t automatically disqualify an applicant, but they typically invite more scrutiny or a smaller approved amount.
Does a pre-approval guarantee final approval?
No. Pre-approval is typically based on a preliminary check and self-reported information; final approval depends on verified documentation and a full underwriting review, which can still change the outcome or terms.
How much does self-employment affect approval chances?
Self-employed applicants aren’t inherently riskier, but they usually need to provide more documentation — often two years of tax returns and several months of bank statements — to demonstrate consistent income, since there’s no employer verification to rely on.
Will closing old credit cards improve my chances?
Not necessarily, and it can backfire — closing an account reduces your total available credit, which can raise your utilization ratio and shorten your average account age, both of which can lower your score rather than help it.
Final Thoughts
Personal loan approval in 2026 comes down to a full financial picture rather than any single number. Credit score matters, but so does the consistency behind it; income matters, but stability often matters more than size; and existing debt load, banking history, and — increasingly — transaction-level data all factor into the decision.
The most reliable way to improve your odds is to address these areas before applying: check your credit report for errors, pay down high-utilization balances, avoid a burst of new credit inquiries, and have income documentation ready. None of this guarantees approval, since every lender sets its own thresholds, but it gives you a realistic picture of where you stand and removes the most common, avoidable reasons for rejection.
3 thoughts on “How Banks Really Decide Who Gets a Personal Loan in 2026”