
Quick Answer
Term life insurance is usually the better fit if your main goal is replacing income or covering a mortgage for a defined period, since it delivers far more death benefit per premium dollar. Whole life insurance tends to make more sense in narrower cases: permanent estate-planning needs, a dependent who will require lifelong financial support, or a specific wealth-transfer strategy. For most households in their 20s, 30s, and 40s buying coverage to protect a family’s income, term insurance is the more cost-effective starting point — but the right answer depends on your specific obligations and budget, not on a blanket rule.
Table of Contents
- Why Life Insurance Still Matters
- How Term Life Insurance Works
- How Whole Life Insurance Works
- Term vs. Whole Life: Side-by-Side Comparison
- When Term Life Insurance Fits Best
- When Whole Life Insurance Fits Best
- Costs That Are Easy to Overlook
- Choosing by Life Stage
- Common Mistakes to Avoid
- Myths vs. Facts
- Frequently Asked Questions
- Final Thoughts
Why Life Insurance Still Matters
Life insurance isn’t only for older adults or high earners. If anyone depends on your income — a spouse, children, or aging parents — a sudden loss of that income can create serious financial strain on top of the emotional one.
The clearest case for coverage is income replacement: if a working parent earning $80,000 a year dies unexpectedly, the family doesn’t just lose a paycheck, they lose decades of future earnings that mortgage payments, childcare, and college savings were built around. Life insurance is also commonly used for mortgage protection, so a surviving spouse isn’t forced to sell the home, and for covering shared debts like car loans or credit balances that don’t disappear with the borrower.
It also plays a role in estate planning for some households — a death benefit can give heirs immediate cash while other assets are still being settled, which matters most for business owners or anyone with assets that aren’t easy to divide or liquidate quickly.
How Term Life Insurance Works
Term life insurance covers you for a fixed period — typically 10, 15, 20, 25, or 30 years. If you die during that term, your beneficiaries receive the death benefit. If the term ends while you’re still living, coverage stops unless you renew (usually at a much higher rate) or convert it to a permanent policy, if your policy allows that option.
Most buyers choose a term length that matches a specific obligation: a 30-year term paired with a 30-year mortgage, or a 20-year term timed to end around when children are expected to be financially independent.
Term insurance tends to appeal to young families, first-time buyers, and anyone prioritizing a large death benefit over a lower budget, because a healthy applicant in their late 20s or 30s can typically buy several hundred thousand dollars of coverage for a modest monthly premium.
How Whole Life Insurance Works
Whole life insurance is a type of permanent coverage designed to last your entire life, as long as premiums are paid. Each premium payment is split between two components: funding the death benefit and contributing to a cash value account that accumulates over time.
That cash value can potentially be borrowed against or withdrawn, and some policyholders incorporate it into longer-term financial planning. It’s worth being clear-eyed about the pace of that growth, though: in the early years of a policy, a large share of each premium goes toward insurance costs, administrative fees, and commissions rather than cash value, so account growth is usually slower than new buyers expect.
The trade-off for permanent coverage and a cash value feature is cost — whole life premiums are commonly several times higher than a term policy with the same death benefit, and they generally stay high for life rather than ending after a set number of years.
Term vs. Whole Life: Side-by-Side Comparison
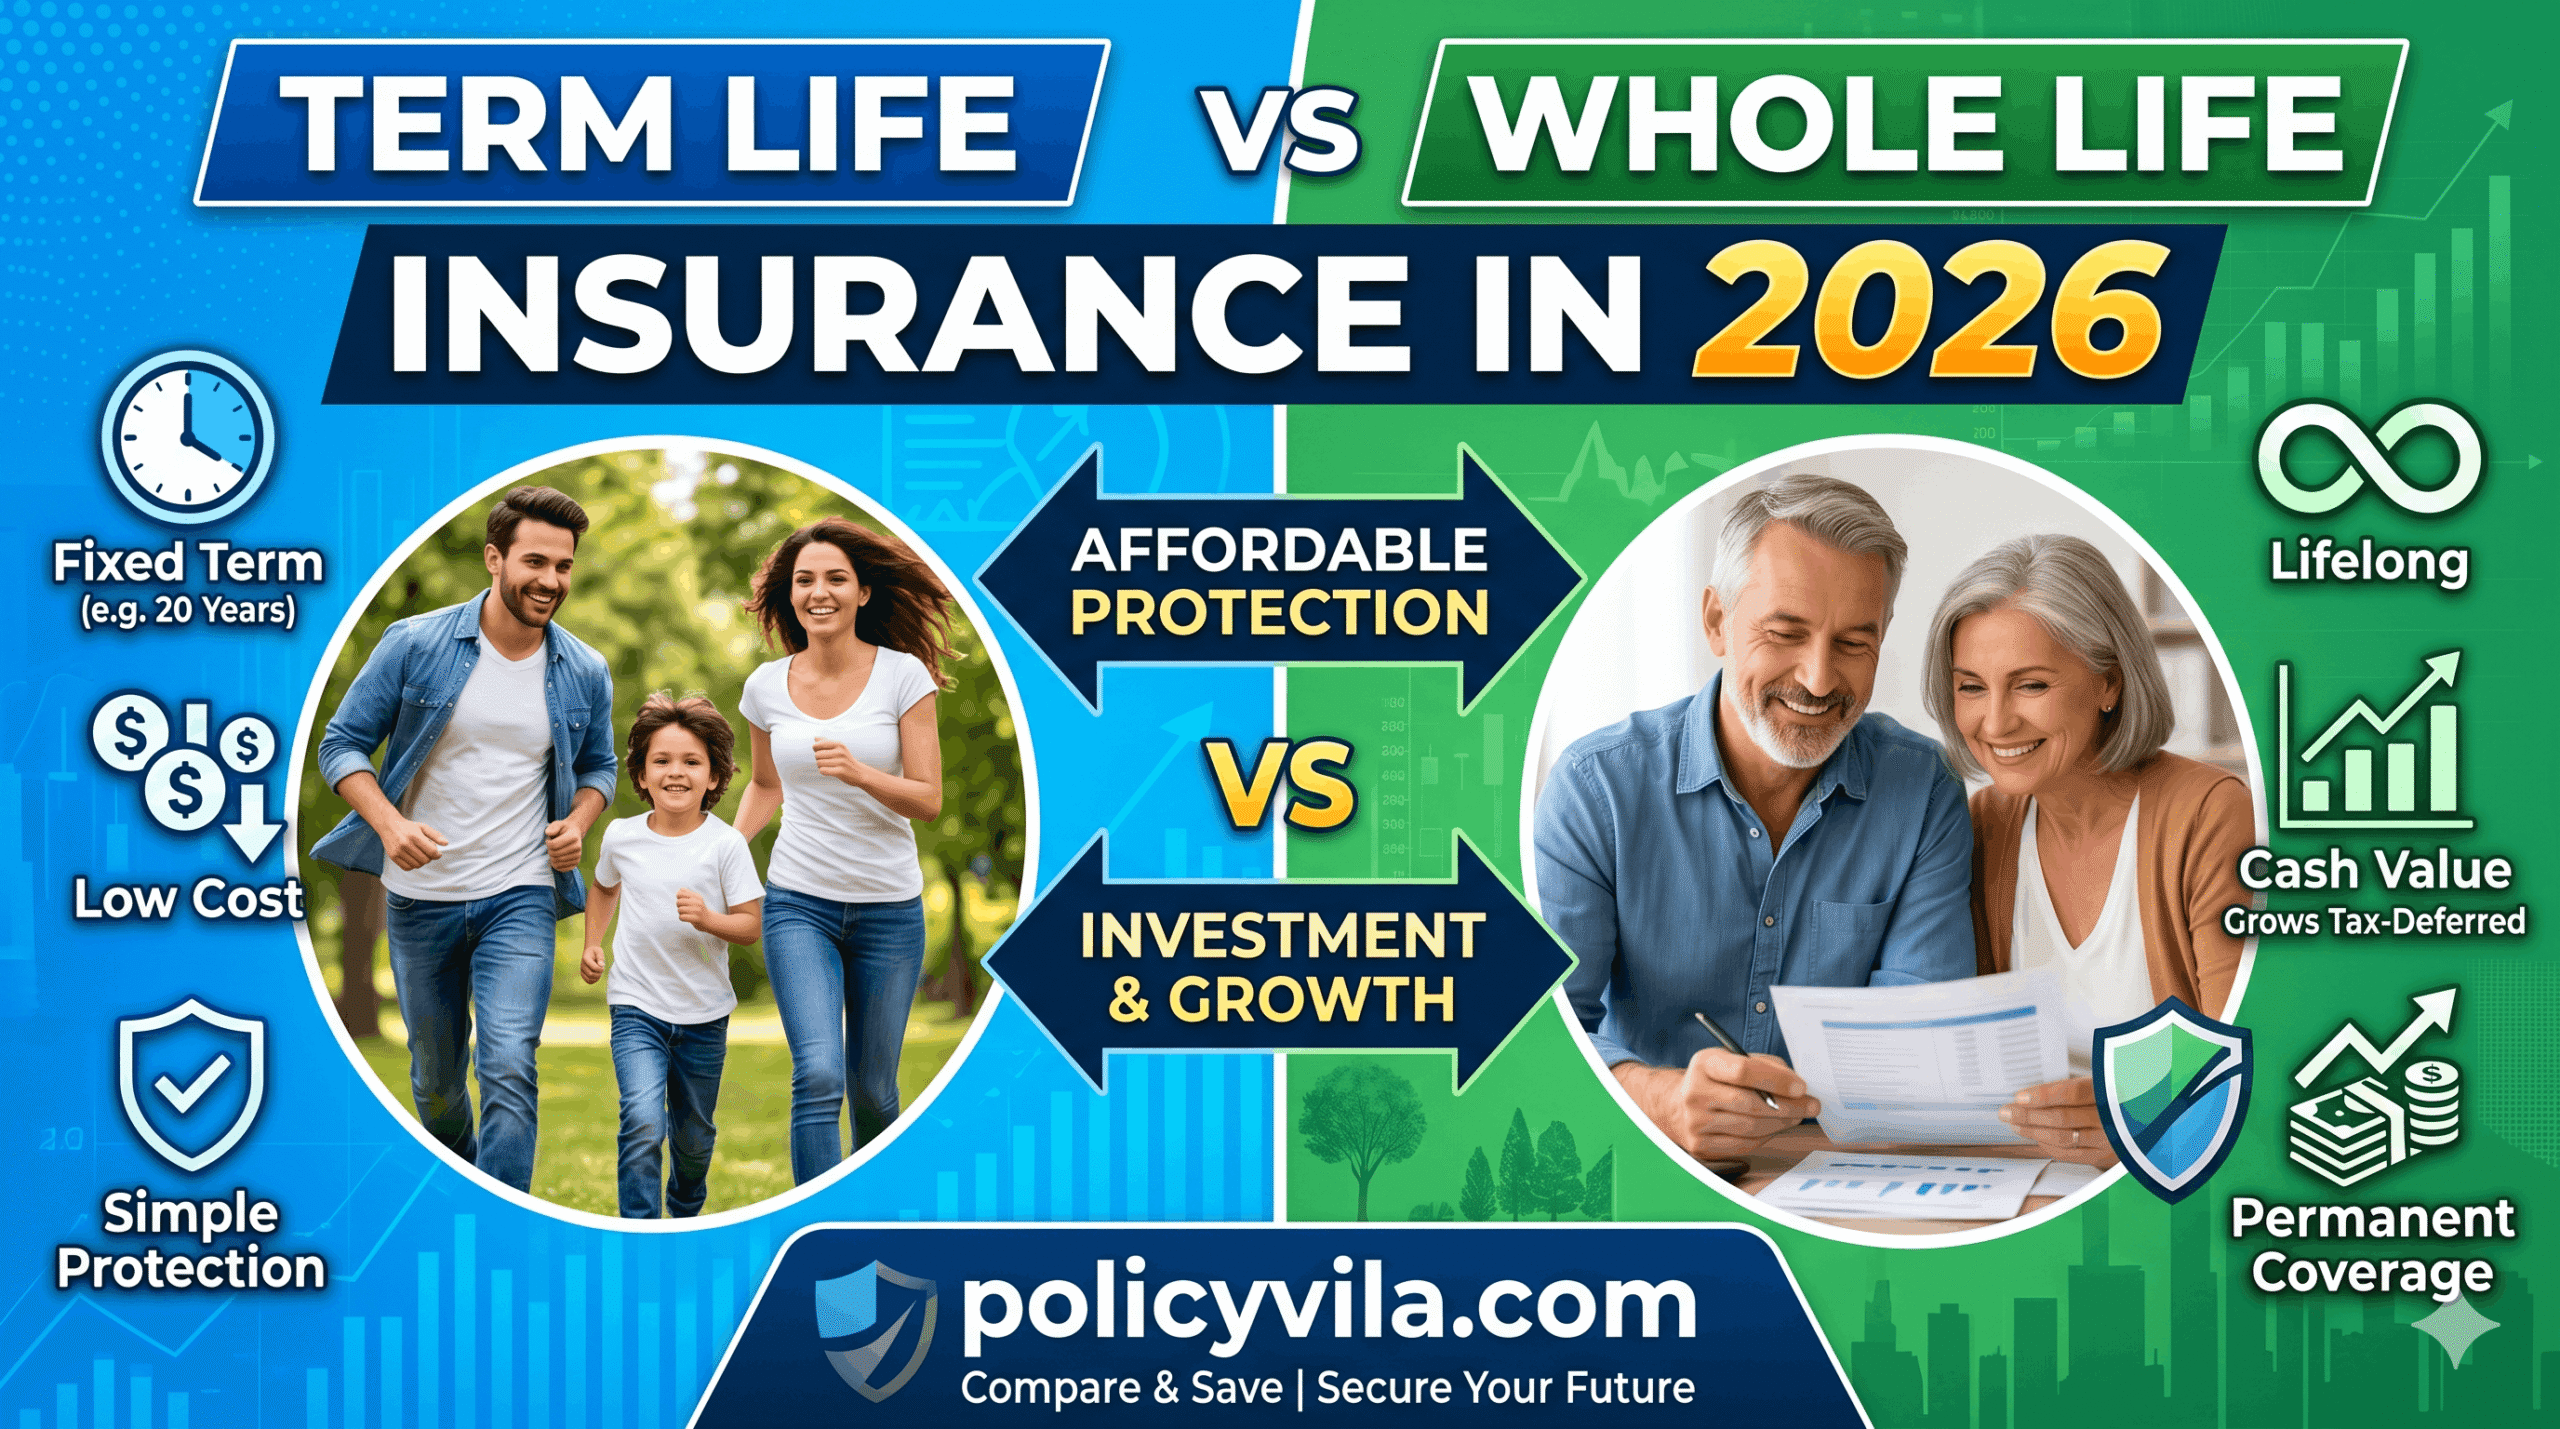
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Coverage length | Fixed term (commonly 10–30 years) | Lifetime, as long as premiums are paid |
| Premiums | Lower, fixed for the term | Significantly higher, generally fixed for life |
| Cash value | None | Builds over time, slowly at first |
| Death benefit | Paid only if death occurs during the term | Paid whenever death occurs, if premiums are current |
| Complexity | Simple | More complex — requires understanding fees and cash value mechanics |
| Typical use case | Income replacement, mortgage protection, debt coverage | Estate planning, lifelong dependents, wealth transfer |
| Coverage per premium dollar | Higher | Lower |
When Term Life Insurance Fits Best
- Young families: maximum coverage for a limited budget during the years children are financially dependent.
- Homeowners: a term matched to the mortgage payoff schedule protects the home without paying for coverage after the loan is gone.
- Income replacement: for most working adults, term insurance delivers more death benefit per dollar than any permanent option.
- “Buy term and invest the difference”: some buyers choose lower-cost term coverage and direct the premium savings into retirement accounts or other investments instead. This can work well for disciplined savers, but it depends on actually investing the difference rather than spending it — the strategy only pays off if that second half happens.
When Whole Life Insurance Fits Best
- Lifelong dependents: a child or family member who will need financial support indefinitely isn’t well served by coverage that expires after 20 or 30 years.
- Estate planning: a death benefit can help cover estate taxes, equalize inheritances among heirs, or give a family business the liquidity to avoid a forced sale.
- High-net-worth wealth strategies: some households use permanent policies as part of legacy or charitable-giving plans, usually alongside professional financial and legal advice.
- Buyers who value guarantees over growth potential: fixed premiums and a guaranteed death benefit appeal to people who want certainty, even at a higher cost than investing the difference elsewhere might produce.
Whole life insurance isn’t a stronger or weaker product than term — it solves a different problem, and it’s worth choosing deliberately rather than because an agent emphasized the cash value feature.
Costs That Are Easy to Overlook
Policy Fees
Whole life policies typically include administrative and mortality charges that affect both cash value growth and the amount you’d receive if you surrendered the policy early. These aren’t always obvious from a sales illustration, so it’s worth reading the actual policy documents, not just the summary.
Opportunity Cost
If a whole life policy costs $300–$350 more per month than an equivalent term policy, that’s roughly $3,600–$4,200 a year that could otherwise go toward retirement accounts or other investments. That doesn’t automatically make term the better choice, but it’s worth comparing what that money could realistically earn elsewhere against the guarantees whole life provides.
Slower-Than-Expected Cash Value Growth
Because early premiums are weighted toward insurance and administrative costs, cash value typically accumulates slowly in the first several years of a policy. Buyers expecting quick, substantial growth are often surprised by how long it actually takes.
Choosing by Life Stage
Ages 20–30
Early career, student loans, and often a first home purchase make affordability the priority. Term insurance typically makes the most sense here, since it locks in low rates while you’re healthy and leaves more budget for other financial goals.
Ages 30–40
Peak family-responsibility years — mortgage payments, raising children, and building college savings. Term coverage sized to last until children are financially independent or the mortgage is paid off is the most common recommendation, though some buyers with estate-planning goals begin layering in permanent coverage during this stage.
Ages 40–50
Financial situations diverge more here. Term insurance can still make sense for remaining income-replacement or mortgage needs, while whole life becomes more relevant for people focused on estate planning, business succession, or long-term legacy goals. This is usually the point where a conversation with an independent financial professional adds the most value, since the right mix depends heavily on individual circumstances.
Common Mistakes to Avoid
- Waiting to buy coverage. Premiums rise with age, and a new health condition can limit eligibility or raise costs significantly.
- Choosing a policy on price alone. The cheapest premium isn’t useful if the coverage amount falls short of what your family would actually need.
- Underestimating how much coverage is needed. A rough starting point is income replacement plus outstanding debts plus future obligations like college costs, adjusted for what savings and other assets already cover.
- Treating whole life cash value as a primary investment. It can be a useful secondary feature, but comparing its growth against dedicated investment accounts before relying on it is worth the extra step.
- Assuming employer-provided coverage is enough. Group life insurance through work is often modest and typically ends when you leave the job.
- Not comparing quotes across insurers. Underwriting and pricing can vary meaningfully between companies for the same applicant profile.
- Forgetting to update beneficiaries. Marriage, divorce, and new children are all reasons to revisit a beneficiary designation that may otherwise be years out of date.
Myths vs. Facts
| Myth | Fact |
|---|---|
| Life insurance is only for older people. | Buying while young and healthy generally locks in lower premiums. |
| Single people never need coverage. | Some singles carry policies to cover debt, support aging parents, or plan ahead for future dependents. |
| Employer coverage is always sufficient. | Group policies are often limited in size and usually end when employment does. |
| Whole life is always the superior choice. | Which policy fits better depends on your goals, budget, and how long you need coverage. |
| Term insurance is money wasted if you don’t die during the term. | It still paid for real financial protection during the years your family needed it most. |
| Cash value growth makes whole life a strong investment on its own. | Growth is often slow early on and is worth comparing against dedicated investment accounts. |
Frequently Asked Questions
Can I convert a term policy into a whole life policy later?
Many term policies include a conversion option that lets you switch to permanent coverage without a new medical exam, usually within a specific window. Not all policies include this feature, so it’s worth confirming before you buy if it matters to you.
What happens if I outlive my term policy?
Coverage simply ends. Some insurers let you renew on a year-to-year basis at a significantly higher rate, or convert to permanent coverage if the option is available, but there’s no payout and no refund of premiums paid.
Do I get any money back if I stop paying a whole life policy?
Depending on how much cash value has built up, you may be able to surrender the policy for a cash payout, though early surrender values are often lower than the total premiums paid, due to fees and the slow early growth curve.
Is whole life insurance a good replacement for a retirement account?
Generally not as a primary strategy. Retirement accounts like 401(k)s and IRAs typically offer more favorable growth potential and tax treatment for retirement savings specifically; whole life’s cash value is usually better thought of as a secondary, more conservative feature.
How much life insurance coverage do I actually need?
A common starting approach is adding up outstanding debts, remaining income you want to replace, and future costs like college, then subtracting savings and existing coverage. An independent agent or financial planner can refine this based on your specific situation.
Can I hold both a term and a whole life policy at the same time?
Yes. Some households layer a larger term policy for income-replacement years on top of a smaller permanent policy for lifelong needs like final expenses or estate planning.
Does a whole life policy’s premium ever increase?
Most whole life policies are designed with level premiums that don’t increase, which is part of their appeal for buyers who want predictable long-term costs. Confirm this specifically for any policy you’re considering, since structures vary.
What happens to cash value when the policyholder dies?
In most standard whole life policies, beneficiaries receive the death benefit, and the accumulated cash value typically reverts to the insurer rather than being paid out separately — a detail that surprises buyers who assumed both amounts would be paid.
Final Thoughts
There’s no universally correct answer in the term-versus-whole-life debate — the right choice depends on how long you need coverage, what you’re protecting against, and how your budget handles the premium difference. Term insurance generally offers the most coverage per dollar for defined-length needs like income replacement or a mortgage. Whole life insurance serves a narrower but real purpose for permanent obligations, estate planning, and buyers who specifically want lifelong, guaranteed coverage.
Before choosing, it helps to answer a few direct questions: who depends on your income, how much debt would they inherit, how long would they need support, and can you sustain the premium comfortably for as long as the policy requires. Comparing quotes from multiple insurers and reading the actual policy terms — not just a sales summary — remains one of the most effective ways to avoid paying for coverage that doesn’t match what you actually need.
2 thoughts on “Term Life Insurance vs Whole Life Insurance in 2026: The Truth Most Insurance Agents Won’t Tell You”