
Personal loan approval in 2026 runs through automated underwriting, credit scoring models, and income verification systems that weigh far more than a single number. This guide breaks down what lenders actually check, the reasons applications most often get turned down, and what to do differently before applying again.
Quick Answer
Personal loan rejections most commonly come down to a low credit score, a debt-to-income ratio that’s too high, unstable or hard-to-verify income, too many recent credit applications, or a requested loan amount that doesn’t match what the lender believes you can repay. Rarely is it just one factor — most rejections happen when two or three of these overlap at once. Reviewing your credit report, paying down revolving balances, and requesting a realistic amount before reapplying addresses the majority of cases.
What Actually Happens When You Apply
Most applicants assume the process is simple: the bank checks income, then approves or denies. In practice, a loan application typically passes through several distinct checks before a decision comes back.
Identity Verification
Lenders confirm your identification, address, and contact details first. Even small mismatches — an old address still on file, a name spelled differently across documents — can trigger a manual review that slows or complicates things.
Credit Report Review
Your credit report shows existing accounts, payment history, collections, and recent inquiries. This is where a lender gets its first real read on how you’ve handled debt in the past.
Income Verification
Pay stubs, tax returns, or bank statements confirm that you actually earn what the application states. Self-employed applicants typically need to provide more documentation here than salaried employees.
Debt Analysis
Existing obligations — credit cards, other loans, a mortgage — get weighed against income to determine whether a new monthly payment is realistically affordable.
Automated Risk Assessment
Modern lenders run all of this through algorithms that combine credit score, debt-to-income ratio, employment stability, and utilization into a single risk estimate, which ultimately drives the approval decision.
Personal Loan Eligibility at a Glance
| Factor | Generally Favorable | Generally a Concern |
|---|---|---|
| Credit score | 700+ | Below 620 |
| Debt-to-income ratio | Below 35% | Above 45% |
| Credit utilization | Below 30% | Above 75% |
| Employment history | Stable, consistent | Frequent recent changes |
| Recent credit applications | Few | Several within a few months |
| Existing debt load | Manageable | Already extensive |
A weakness in one row rarely sinks an application on its own. Rejections usually happen when several of these line up unfavorably at the same time.
The Reasons Applications Get Rejected
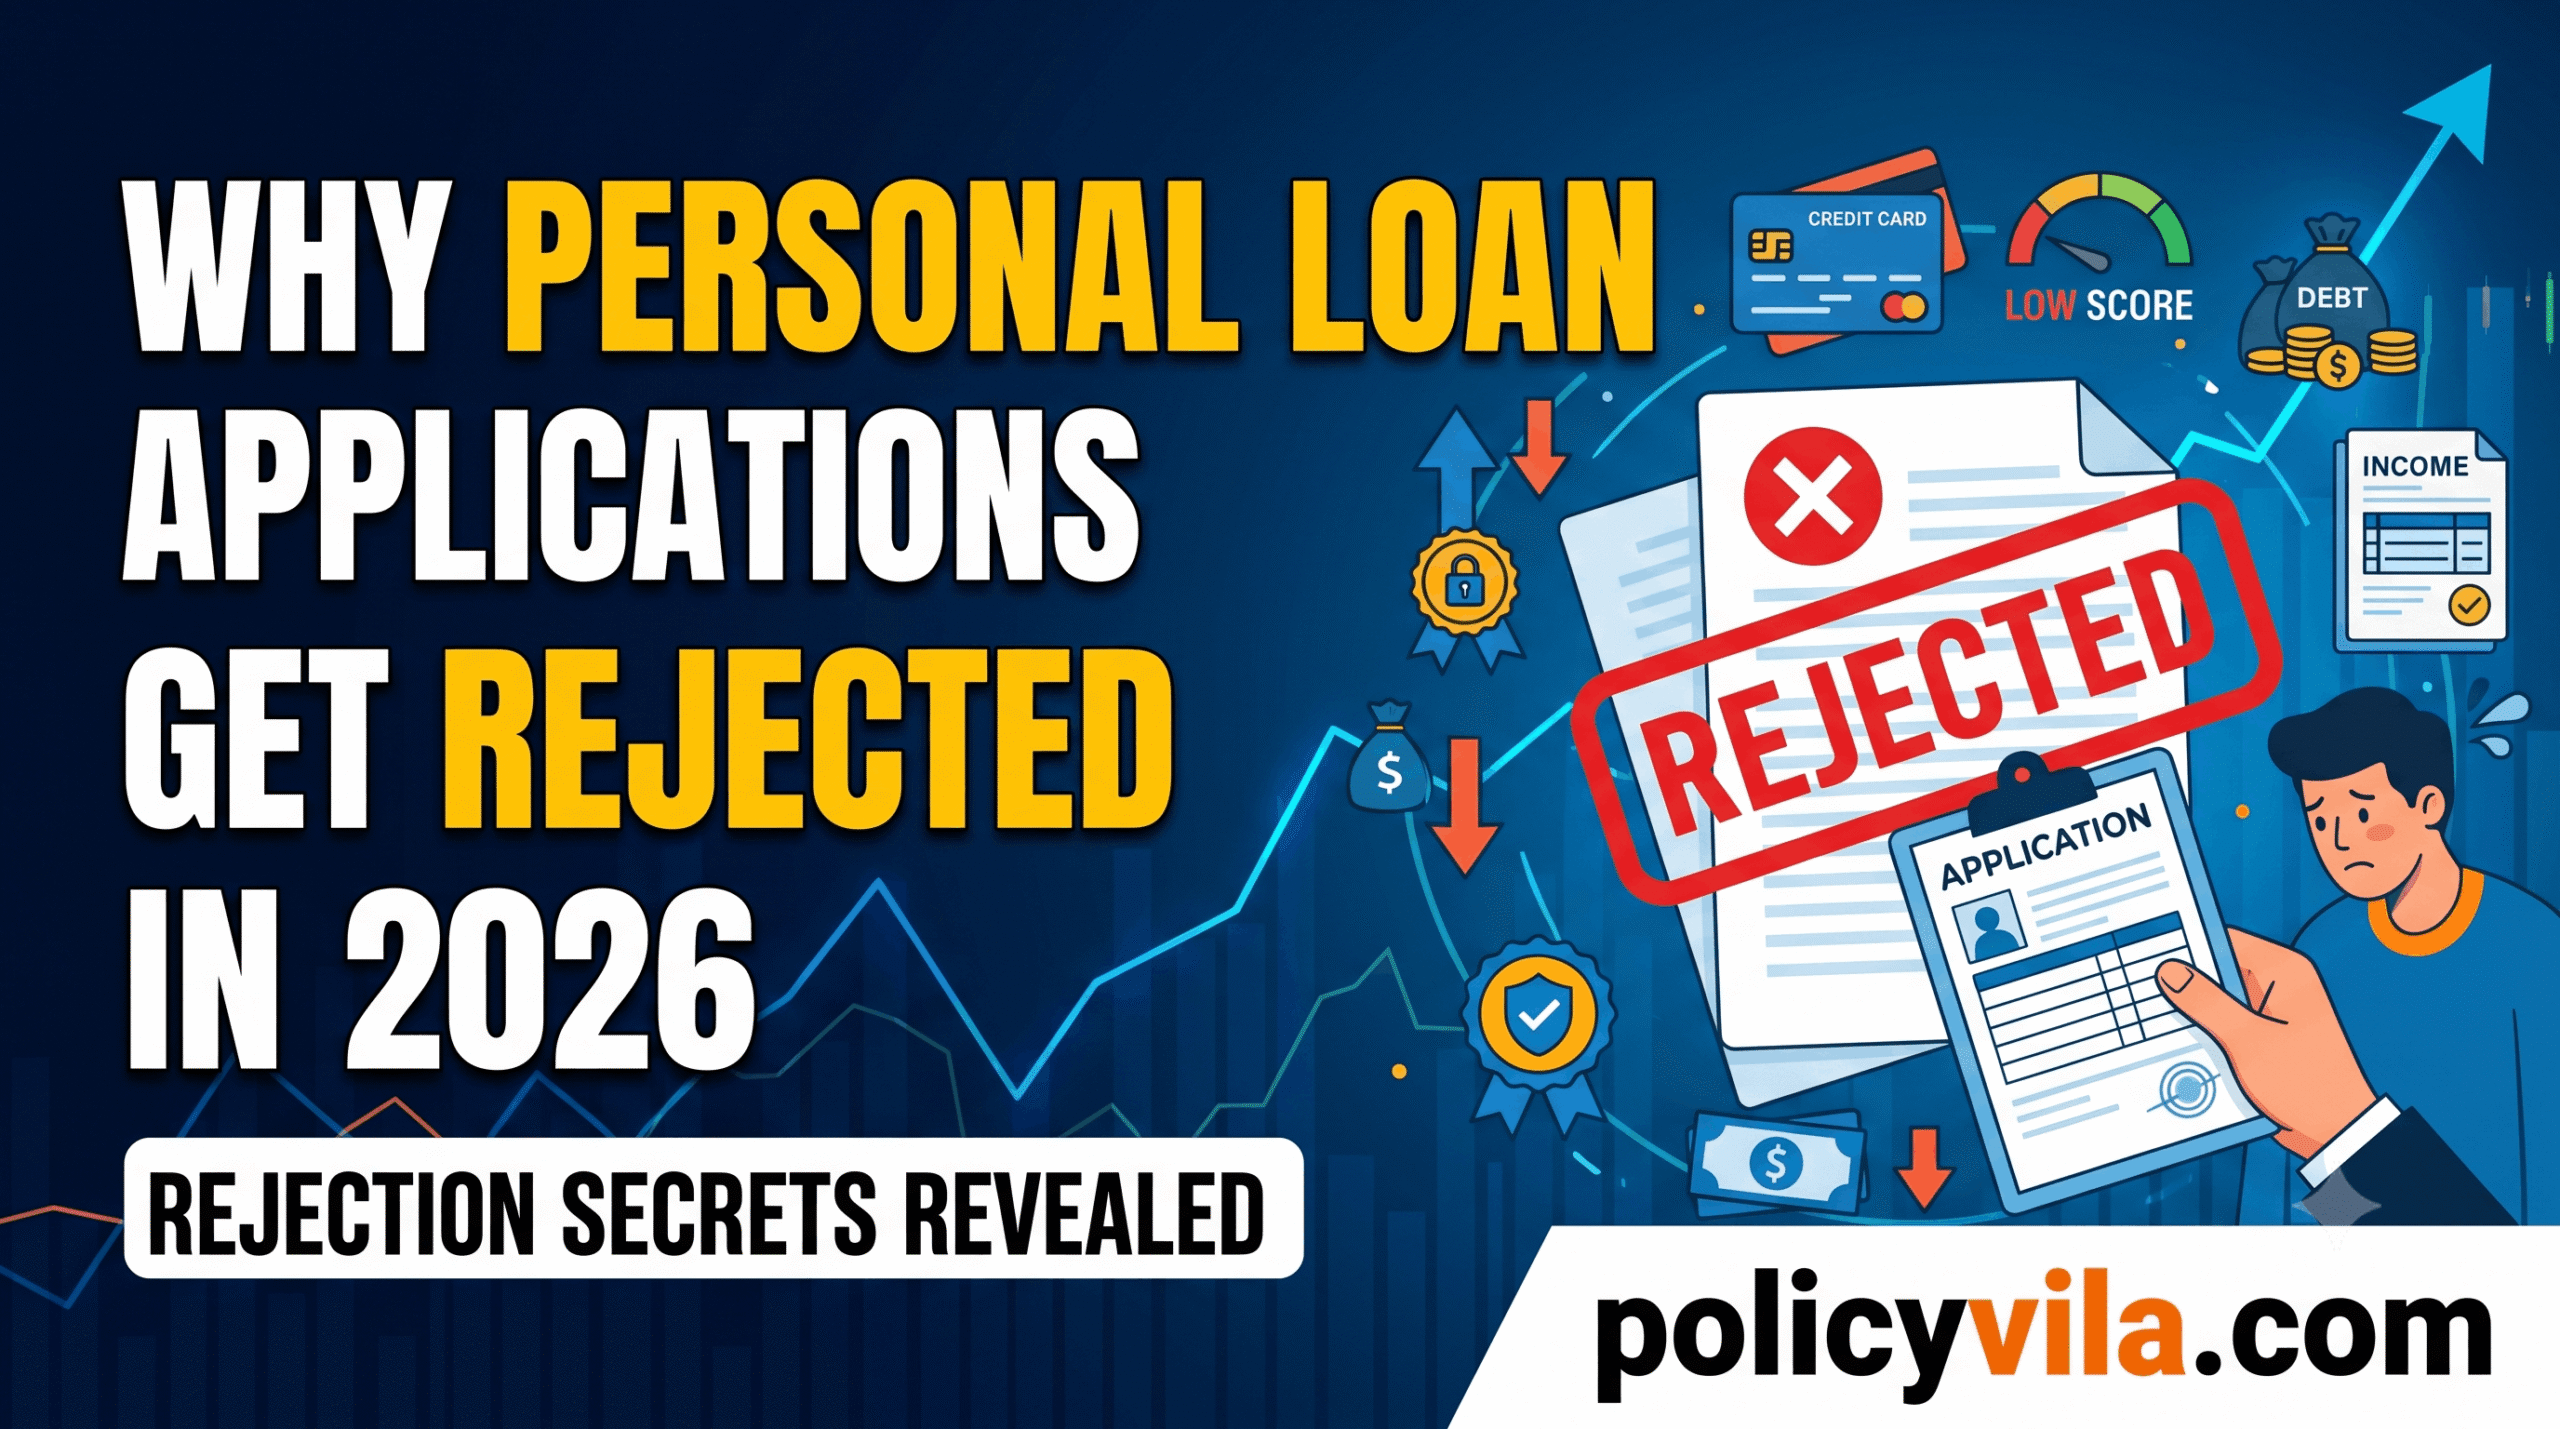
A Low Credit Score
Your score is one of the fastest signals a lender uses to judge repayment risk. Someone with a stable job and five years at the same employer can still be denied if a history of late credit card payments has pulled their score down — the income doesn’t offset what the score is signaling about past behavior.
What helps: Paying on time going forward, lowering balances relative to credit limits, and disputing any inaccurate items on your report. None of this fixes things overnight, but even a modest score increase can shift a borderline application.
A High Debt-to-Income Ratio
This compares your monthly debt payments to your monthly income. Someone earning $6,000 a month who’s already paying $3,400 across a mortgage, auto loan, credit cards, and student loans has little room left for a new payment, regardless of how solid that income looks on paper.
What helps: Paying down existing balances before applying, and avoiding new obligations in the months leading up to an application.
Unstable or Frequently Changing Employment
Several job changes in a short window — even if each move came with a raise — can read as unpredictable future income to a lender evaluating long-term repayment ability.
What helps: Applying once your current role has had time to establish a track record, and being ready to explain any recent transitions if asked.
Too Many Recent Credit Applications
Multiple applications for credit cards, auto loans, and personal loans within a couple of months can look like financial distress, even to a lender that would otherwise view your credit favorably.
What helps: Spacing applications out and only applying when you’re reasonably confident you’ll qualify, using prequalification tools where available.
High Credit Utilization
Someone carrying $18,000 in balances against a $20,000 total limit is at 90% utilization — a red flag even with a perfect payment record, since it suggests limited financial cushion.
What helps: Paying down revolving balances before applying rather than after being denied.
Incomplete or Inconsistent Documentation
An application can meet every substantive requirement and still stall because submitted income documents don’t match what’s listed on the form, or because a request for clarification goes unanswered.
What helps: Double-checking that every document lines up before submitting, and responding quickly if a lender asks for more information.
Income That Doesn’t Support the Requested Amount
Even excellent credit doesn’t guarantee approval if the loan amount requested is out of proportion to income — someone earning $55,000 a year requesting a $60,000 loan is likely to be seen as overextended regardless of credit history.
What helps: Requesting an amount that’s realistic relative to income, or applying with a qualified co-borrower.
Errors on Your Credit Report
Credit reports aren’t always accurate. A collection account that belongs to someone else with a similar name, or an outdated late payment that should have aged off, can drag a score down without the borrower ever having done anything wrong.
What helps: Reviewing your reports before applying and disputing anything inaccurate, with documentation where you have it.
A Short Credit History
A recent graduate with perfect payment habits and low balances can still be turned down simply because there isn’t enough history yet for a lender to evaluate confidently.
What helps: Time is the main fix here, along with keeping accounts open and using credit responsibly while that history builds.
Recent Missed Payments
Even a generally healthy credit profile can be undermined by a handful of late payments in the past year, since payment history carries significant weight in most lending decisions.
What helps: Bringing any delinquent accounts current and setting up automatic payments to prevent a repeat.
Reliance on High-Risk Debt
Payday loans, high-interest installment loans, or debt settlement accounts on a credit report can signal ongoing financial strain to a lender, even when payments on those accounts are current.
What helps: Paying off expensive debt aggressively and building even a small emergency fund to reduce the need for that kind of borrowing going forward.
No Existing Banking Relationship
Applying at an institution where you’ve never held an account means the lender has no deposit history or account behavior to draw on, which can lead to a more cautious decision than an established customer would receive.
What helps: Applying through a bank or credit union where you already have an active account, when that’s an option.
Inconsistencies That Read as Suspicious
Reported income that doesn’t match bank statement deposits, or unexplained large transfers, can trigger a lender’s fraud checks even when there’s an innocent explanation.
What helps: Reporting income accurately and being ready to explain any unusual account activity if asked.
Warning Signs Before You Apply
A handful of these showing up together is a reasonable signal to strengthen your profile before submitting an application rather than after receiving a denial:
- Credit score below what your target lender typically approves
- High balances relative to your credit limits
- Several hard inquiries in the past few months
- One or more missed payments within the past year
- A debt-to-income ratio above roughly 40%
- Incomplete or inconsistent financial documentation
- Employment history with several recent changes
- A requested loan amount that’s large relative to your income
Approved vs. Rejected Applicant Profiles
| Factor | Typical Approved Applicant | Typical Rejected Applicant |
|---|---|---|
| Credit score | Strong and stable | Weak or trending downward |
| Payment history | Mostly on time | Several recent late payments |
| Debt-to-income ratio | Manageable | Already stretched |
| Documentation | Complete and consistent | Missing or mismatched |
| Recent applications | Limited | Several in a short window |
| Requested amount | Proportional to income | High relative to income |
Myths vs. Facts
| Myth | Fact |
|---|---|
| A high income guarantees approval | Lenders weigh credit history, existing debt, and documentation alongside income |
| Rejection always means bad credit | Applications get declined for many reasons beyond the credit score alone |
| Checking your own credit score hurts it | A self-check is a soft inquiry and has no effect on your score |
| Applying to several lenders at once improves your odds | Multiple applications in a short window can itself become a risk signal |
| A loan rejection is a permanent mark against you | Rejections don’t stay on your record and can be overcome with a stronger later application |
| Self-employed applicants can’t qualify | Many lenders approve self-employed borrowers who provide adequate income documentation |
| Closing old accounts helps your application | Older accounts generally strengthen credit history rather than weaken it |
How to Strengthen an Application
Start With Your Credit Report
Pull your reports well before applying, not after a denial. Dispute anything inaccurate and give corrections time to process — this alone resolves a meaningful share of otherwise-avoidable rejections.
Bring Down Revolving Balances
Lower utilization improves both your credit score and how affordable a new payment looks to an underwriter evaluating your overall debt load.
Match the Loan Amount to Your Income
A prequalification check, where the lender offers, can show what you’re likely to qualify for without a hard inquiry, helping you request an amount that fits rather than one that gets flagged as overreaching.
Get Documentation Right the First Time
Make sure pay stubs, bank statements, and the application itself all tell the same consistent story before submitting anything.
Be Selective About Timing
Applying once your employment has had time to stabilize, and after any recent credit inquiries have had a few months to age, generally produces a stronger outcome than applying the moment a need arises.
A 30-Day Preparation Plan
Week 1: Know Where You Stand
Pull your credit reports, check your current score, and list every existing debt and its monthly payment. This is where most people discover the specific issue that’s actually working against them.
Week 2: Reduce the Obvious Risk Factors
Pay down high-utilization balances, bring any overdue accounts current, and hold off on applying for any other credit in the meantime.
Week 3: Build a Stronger Profile
Organize income documentation, calculate your actual debt-to-income ratio, and start or add to an emergency fund if you don’t already have one.
Week 4: Prepare the Application Itself
Compare a few lenders’ stated requirements, settle on a realistic loan amount, and make sure every document you’ll submit is accurate and consistent before you apply.
Frequently Asked Questions
Why would I get rejected if my income is strong?
Income is one input among several. A lender also weighs credit history, existing debt, documentation accuracy, and how the requested amount compares to what you earn — strong income doesn’t offset serious weaknesses elsewhere.
Can I apply again after a rejection?
Yes. Most lenders don’t prevent reapplication; the more useful step is identifying what likely drove the denial and addressing it before trying again.
How long should I wait before reapplying?
It depends on the reason for the rejection. Many advisors suggest waiting at least 30 to 90 days while you improve credit, pay down debt, or correct report errors, rather than reapplying immediately with the same profile.
Does a rejection itself hurt my credit score?
The denial doesn’t directly affect your score, but the hard inquiry generated by the application can cause a small, temporary dip regardless of the outcome.
What credit score do I typically need for approval?
Requirements vary by lender, but scores below roughly 580 usually face the most difficulty, 580–669 gets fair approval odds with less favorable terms, 670–739 is generally workable, and 740 and above typically sees the strongest terms.
Can self-employed applicants qualify?
Yes, though lenders typically require more extensive income documentation — tax returns, profit-and-loss statements, and bank records — than they would from a salaried employee.
Does paying off some debt before applying actually help?
Generally yes, since it directly improves your debt-to-income ratio and often your utilization, both of which are factors a lender weighs heavily.
Is there a single most common reason for rejection?
Not really a single one — the most common pattern is a combination of factors, like a moderate credit score paired with high utilization and a couple of recent inquiries, rather than any one issue in isolation.
Will multiple Buy Now, Pay Later plans affect my approval odds?
They can, particularly if you’re running several at once. Even though BNPL feels different from a traditional loan, it’s still a recurring obligation, and increasingly one that shows up in how lenders assess affordability.
Final Thoughts
A loan rejection rarely comes down to one clean, easily identifiable cause — it’s usually the sum of a few factors that, individually, might not have mattered much. The upside is that nearly every one of those factors is something you can actually work on: a credit report you can correct, a balance you can pay down, an application you can time better.
Treat a denial as information rather than a dead end. Reviewing your credit report, tightening your debt-to-income ratio, and requesting an amount that genuinely fits your income puts you in a meaningfully stronger position the next time you apply.
4 thoughts on “Why Personal Loan Applications Get Rejected: 15 Hidden Reasons Banks Don’t Tell You in 2026”